Derivatives (Formulas)
0.0(0)
Studied by 0 people Call Kai
 Learn
 Practice Test
 Spaced Repetition
 Match
 Flashcards
 Knowt Play
Card Sorting
1/4

There's no tags or description
Looks like no tags are added yet.
Last updated 7:24 PM on 9/23/26
Name | Mastery | Learn | Test | Matching | Spaced | Call with Kai | Chat |
|---|
No analytics yet
Send a link to your students to track their progress
5 Terms
1
New cards

Currency Swaps
What you receive - what you pay is the value.
0.88 × 5,000,000 × 1.06 – 0.91 × 5,000,000 × 0.97
2
New cards
FRA (forward rate agreement) 9×12

3
New cards
he future value of an underlying asset with carry cash flows is equal to the future value of the spot price:
plus carry costs and minus carry benefits.
4
New cards
Adjusted price of a fixed-income futures contract at Time 0 is equal to the
product of the quoted futures price and the conversion factor.
5
New cards
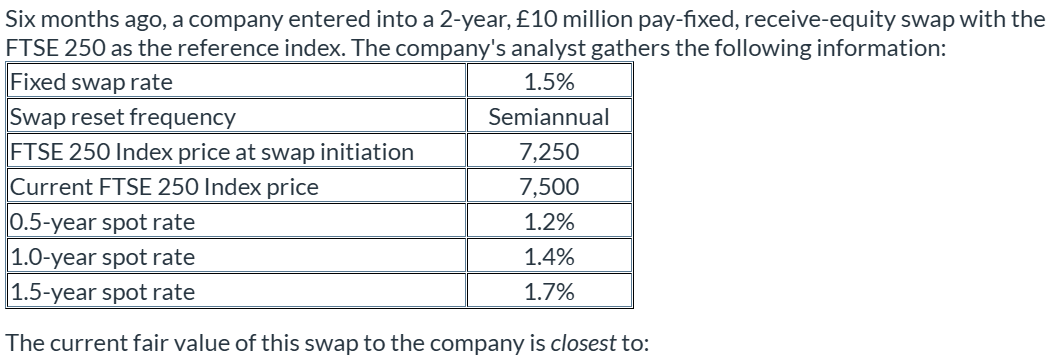
pay-fixed, receive-equity swap
