chp 4 - professional skepticism
 Call Kai
 Learn
 Practice Test
 Spaced Repetition
 Match
 Flashcards
 Knowt Play
1/7

There's no tags or description
Looks like no tags are added yet.
Name | Mastery | Learn | Test | Matching | Spaced | Call with Kai | Chat |
|---|
No analytics yet
Send a link to your students to track their progress
8 Terms
what is professional skepticism
Professional skepticism is an attitude that includes a questioning mind and a critical assessment of audit evidence
characteristics of professional skepticism
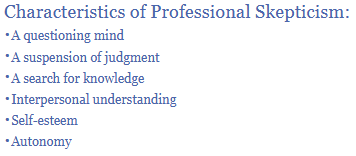
a questioning mind (related to the way an auditor examines evidence)
an attitude that includes a “questioning mind” - an ongoing questioning of whether the information and evidence obtained suggests that a material misstatement due to fraud has occurred
a suspension of judgement (related to the way an auditor examines evidence)
withholding judgment until there is an appropriate level of evidence on which to base a conclusion
a search for knowledge (related to the way an auditor examines evidence)
a sense of general curiosity or interest. Skeptics are interested in knowledge in general and are not necessarily motivated to search simply to verify a specific conclusion or obtain specific information
interpersonal understanding (considers human aspect of auditing)
understanding the motivation and integrity of the individuals who provide evidence.
Ability to identify and consider the many incentives and opportunities available to client personnel to present misleading evidence or to commit fraud, and recommends recognizing the possibility for less than truthful communication
self-esteem (ability of the auditor to act on the information obtained)
enables an auditor to resist persuasion attempts and to challenge another’s assumptions or conclusions - allows them to value their own insights at least as greatly as those of others.
autonomy (ability of the auditor to act on the information obtained)
the ability to objectively evaluate audit evidence to determine if the evidence is sufficient to render a judgment.