Acc 3010 Exam 1
 Call Kai
 Learn
 Practice Test
 Spaced Repetition
 Match
 Flashcards
 Knowt Play
1/47

Earn XP
Description and Tags
Name | Mastery | Learn | Test | Matching | Spaced | Call with Kai | Chat |
|---|
No analytics yet
Send a link to your students to track their progress
48 Terms
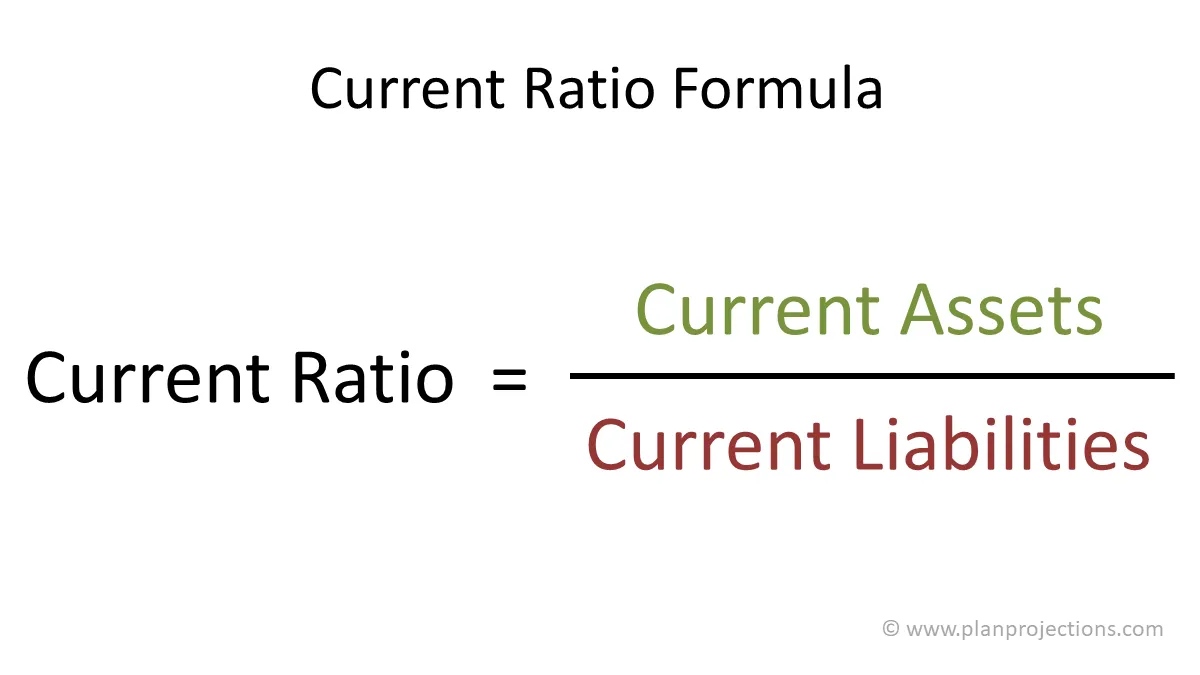
Current Ratio Formula
current assets / current liabilities
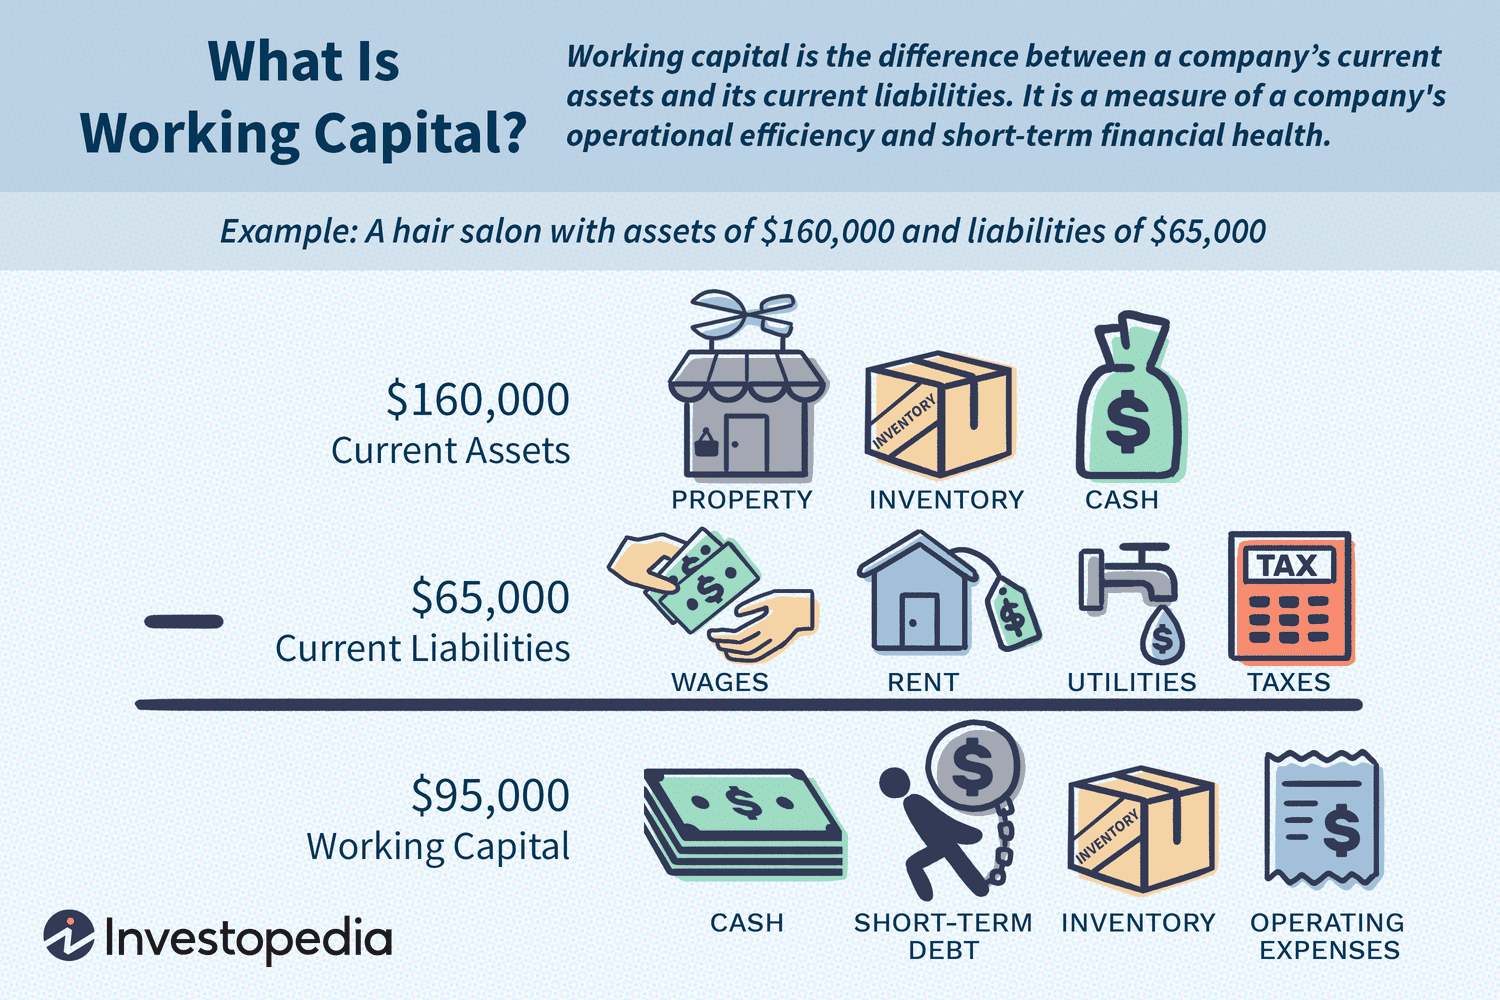
Working Capital Formula
current assets - current liabilities
What does GAAP stand for?
Generally accepted accounting principles

Accounting Equation
A=L+E
know the variations algebraically
Who has the ultimate responsibility for financial statements?
Management
NOT AUDITOR
Balance Sheet Accounts
cash
AR
inventory
prepaid expenses
ppe
investments
long term assets
loans/notes payable
deferred revenue
AP
long term liabilities
common stock
RE
dividends
APIC

Income Statement accounts
revenue
COGS
R&D
Marketing
SGA
other expenses
NOT PREPAID THOSE ARE ASSETS
Net Income
What is an asset
resources
What is a liability
claims to a resource, obligation to others
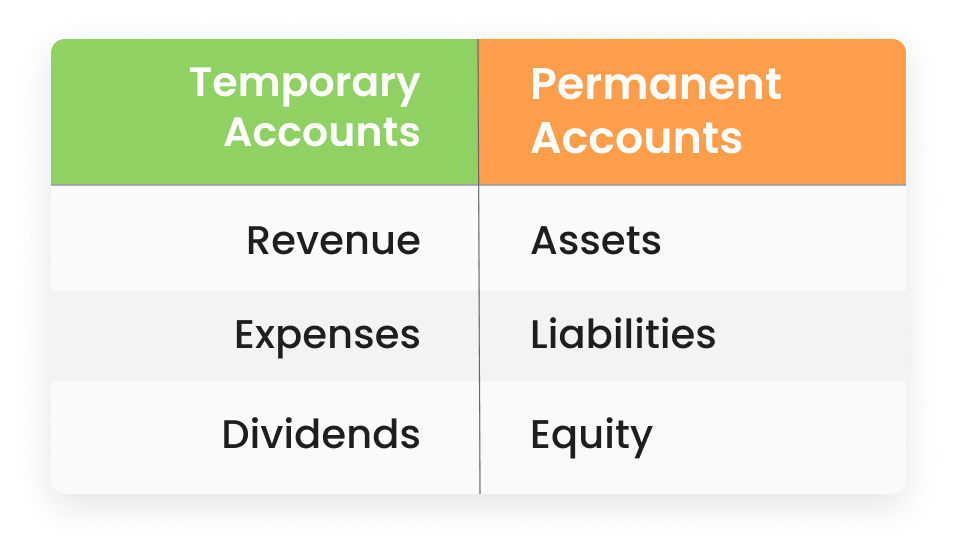
Permanent Accounts
Balance sheet accounts
Temporary accounts
Dividends and Income Statement
R.E.D
Primary objective of accounting
Decision making
lightbulb and money cycle

Internal v External accounting
financial acct is external
managerial is internal
Completeness
complete
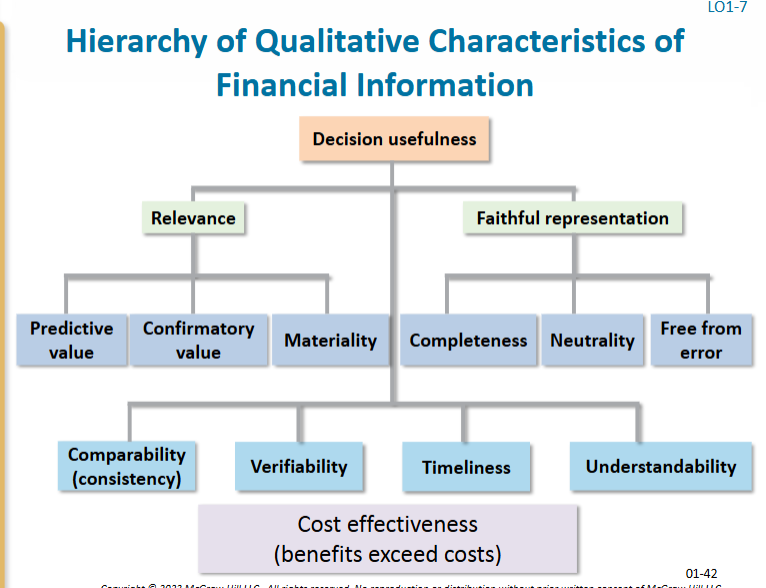
Relevance
applicable in current situation
Faithful representation
trust
was reliability, same thing
jan 1 is more relevant, but april 1 is more reliable (takes time to close books, jan 1 is estimate)
Predictive
Is it useful to prefict future expectations
Confirmatory
allows to confirm expectations
does the numbers make sense of my choice to invest in xyz comp
Materiality
Will it change mind of decision maker
How is money used, does owner take $ to buy 30k car?
All fraud is material
If it is over or under set $ include or not
Is it off enough to look into
Completeness
is it complete, everything recorded
Neutrality
unbiased
Free from error
correct
Comparability
aka consistency
able to compare different years at different comps
can compara data to others
Verifiability
able to be verified
Timeliness
applicable
Understandability
footnotes, is language not overly complex
Constraint to characterisitcs
Cost effectiveness
do the benefits exceed costs
not worth is to fix $20 error when it takes hours
What are the 4 assumptions
going concern
Economic entity
periodicity
monetary unit

Going concern
Concern = business, ongoing business keeps going, NOT A WORRY,
If there is a doubt a comp will go out of business within a year needs to be disclosed (substantial doubt)
Economic entity
draw a border, does it capture everything in it?
able to build reports

Periodicity
divided into time periods
Monetary unit
USA statements are in US $
Recognition v Realization
Recognition
When it goes in financials
service is provided, good is received (GAAP)
accural acct
Realization
Earnings process is judged to be complete
Reasonable certainity to collect asset
CASH CHANGES HANDS
Stock
Can recognize when earned, but not realized until cash is there
Initial v Subsequent Measurement
Initial
bought ppe
Subsequent
depreciation
later in time
Who sets accounting RULES
FASB
Has rule making authority
Who sets accounting LAWS
Statutory authority can make laws
SEC
codification is the only stat. authoirtative liteture
Earning per Share
EPS = NI / # shares outstanding
Liquidity v Solvency
Liquidity
ability to pay current liab with current assets
Solvency
ability to stay in business long term
can be solvent and not liquid
Current v Longterm
current means within a year or reporting period
longterm is over those time periods
Sale of merchandise JE
C.A.R → CoIN
Cash/ AR ##
Rev ##
COGS ##
Inven ##

Allowance for doubtful accouts
contra asset

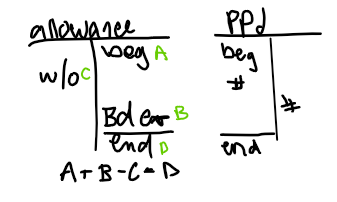
Allowance and Bad debt
t charts and journal entry

BS limitiations
Record assets at historical costs and not their market value
Market value is less reliable than historical cost, but more relevant
Some assets are not on bs
Branding
Nike logo
Employees
Cash equivalents
Immediately or super shortly be converted into cash
Commercial paper
Same thing as tbill for companies
<1 yr collection period
Money market funds
Banks invest in longer term things, higher %
US treasury bill
Short term treasury bond
30, 60, 90, 1 yr
Can be sold for cash at anytime
politics
mid-1990s: accounting for employee stock options
2007: implementation of fair vair accounting standard

Controversy
Govt pressured FASB to follow EU and world acct standards
Convergence with intl standards, not 100% work together but not same
Moving back, not forward
Dakota dog story, always find a way outside of the bounds, add more protections
Works together now, but not same
MAIN CONTROVERSY: revenue recognition and leases
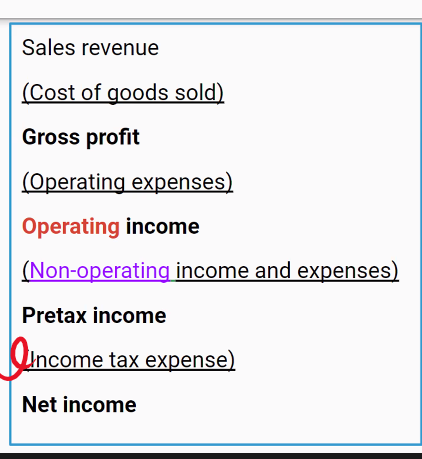
Know how to build BS
A = L + E
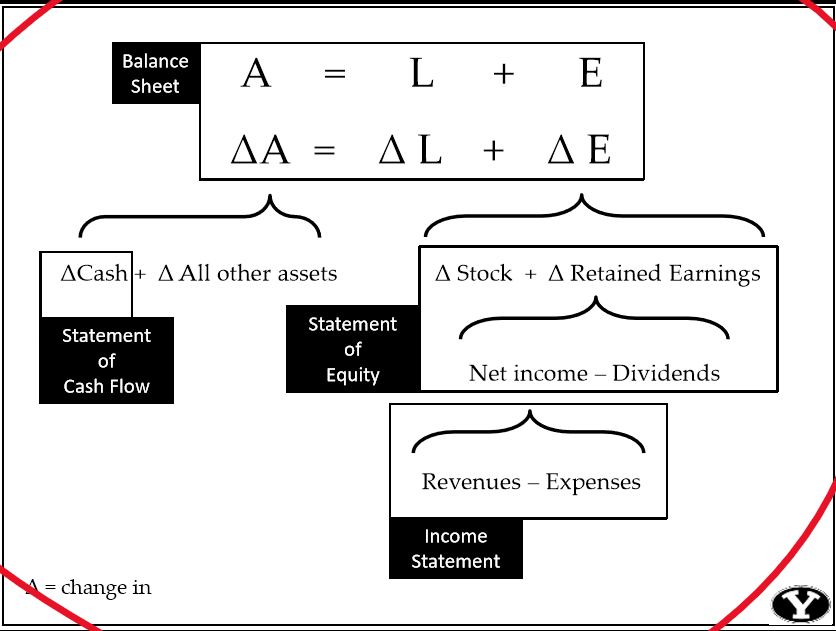
Know how to set up IS
rev - cogs
GP - op exp
op inc - non op exp
EBT - taxes
NI