Econ Unit 1
 Call Kai
 Learn
 Practice Test
 Spaced Repetition
 Match
 Flashcards
 Knowt Play
1/84

There's no tags or description
Looks like no tags are added yet.
Name | Mastery | Learn | Test | Matching | Spaced | Call with Kai | Chat |
|---|
No analytics yet
Send a link to your students to track their progress
85 Terms
Microecon
Study of choices made by individuals
Consumption
Act of individuals with limited incomes choosing to acquire things that generate satisfaction (utility) aka products (goods & services)
Production
Individuals choose to use things to continuously produce products & make avail for people to consume.
4 main grouping of resources necessary to produce products
Labor
Land
Capital
Entrepreneurial ability
Exchange
Indiv. choose to trade less valued items for more valued items
Exchanges can be (2)
Monetary
In-kind
Scarcity of Resources
A state where the quantity of an item is LESS than the quantity of the item people willing to use if priced at 0.
All resources are considered to be
Scarce
When you choose to produce more of ONE product, you produce
LESS of something else (Opportunity cost)
Types of Economies where decisions are made (3)
Centrally planned economy
Market economy
Mixed economy
Centrally Planned Economy
When the people that control the gov decide how econ resources will be allocated
Market Economy
The decisions of indiv. households & managing firms interact in markets to allocate econ resources
Mixed Economy (2)
Most econ decisions result from interaction of buyers & sellers in markets
But gov plays significant role in allocation of resources
Positive Analysis (2)
Concerned with WHAT IS and WHAT IS EXPECTED TO BE
Not whether outcome is good or bad (outcomes you should get)
Normative Analysis (2)
Concerned with WHAT OUGHT TO BE based on certain value system, NOT CONSEQUENCES of choices (believe or don’t)
Mathem. stated as
“Some variable (y) is a function of another variable (x).”
2 possible ways variables are related
y positiv related to x / x positiv rel to y
y neg rel to x / y neg rel to x
Variables either rel
pos or neg, or NOT AT ALL

Pos Rel Graph Pt 1
Move away from origin, x & y increase (upward)
Pos Rel Graph Pt 2
Move towards origin, DOWN, both x & y decrease
Pos Rel def
If size of x increases / decreases, y will do the same

Neg Rel Pt 1
As x gets closer to origin, y increases as it moves upward (opposite)

Neg Rel Pt 2
As x gets farther from origin (increases), y decreases, getting closer to origin. (opposite)
Neg Rel def
If size of x increases/decreases, y does opposite

Pos & Neg Rel Curve
Express pos rel in one range and neg rel in other
Prod Poss Curve
Identify diff combinations of the 2 products can be produced (resources are scarce)
What you gain equation
what lose (numerator) /what you get (denominator)
Opportunity Costs INCREASE as
More and more of a produce is produced
Opp cost & law of comp. advantage
Used to compare prod possibility curves
Finding low opp cost
divide top & bottom by denominator
Market System/Price System (2)
Many buyers compete against other buyers for scarce items
Many sellers compete against other sellers for those buyers
Price
How much buyer pays for ONE UNIT
Market Demand Curve
Demand side of market (buyers & potential buyers focus)
Market Supply Curve
Focuses on sellers & potential sellers of items
Market Equilibrium
At price, quantity demanded for item = quantity supplied for the item
Quantity demanded (qd) def & equation (2)
Max quantity of items buyers = willing to buy
qd=f(p)
Law of demand
Whenever unit price & nothing changes, quantity demanded goes up/down (neg rel)
Cheaper = more wanted / More expensive = less demand
The buyers and sellers are ___ to compete against e/o & gov does ___ inerfere with their decisions
Free
Not
6 Assumed Constants of Market Demand Curve
Income
Prices of related goods
Tastes
Population (# of buyers)
Expected future prices
Taxes imposed on subsidies granted to buyers
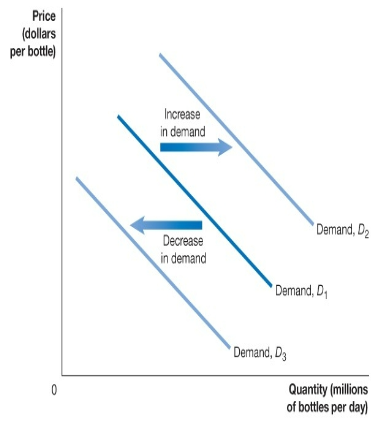
Which ways (2)
Decrease in demand moves closer to origin
Increase in demand moves farther from origin
Demand symbol
△
Quantity demanded equation
△qd
Change in price will cause change in
will cause change in quantity demanded
Sellers side of market + equation (2)
Limited amount sellers willing & able to sell
qs=f(p)
qs is a function of
function of price

Law of Supply (2)
When price ↑, quantity supplied ↑ (paid more, sell more)
When price ↓, quantity supplied ↓ (paid less, sell less)
Supply curve must be
Must be positive slope
6 Constants of Market Supply Curve
Prices of inputs
Tech change
Prices of substitutes in production
#s of firms in the market
Expected future prices
Taxes or subsidies
If any of these supply constants change, then the
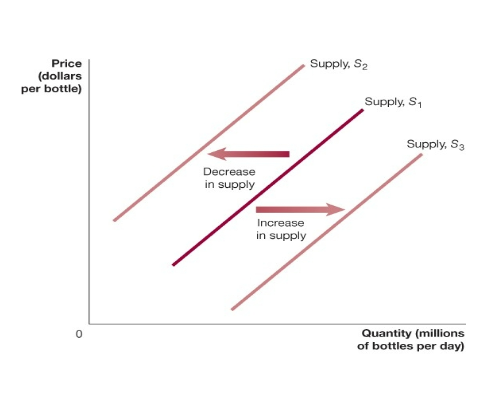
ENTIRE supply curve will shift, either to right or left
For supply curve, orientation is always ______, never ______
Right & left
Never up and down
Change in constant =
Change in price =
= change in supply
change in QUANTITY SUPPLIED
Supply curve graph, how to tell when dec supply vs incr supply
If quantity demanded (demand curve) = quantity supplied (supply curve), they
MUST intersect
Effect of Excess Supply and Excess Demand
Surplus (only over equilibrium point)
If gov does nothing about excess supply, then the supply will
go down on its own.
Only way excess supply persists is if gov
if gov buys up excess supply (price below equilibrium price)
Consumer Surplus (2)
Net gains to buyers when buyer pays price than Marginal Benefit to buyer gets by buying item
Aka if a buyer buys an item for less than they were willing to pay, the money they get to keep is CS.
Consumer Surplus Equation
Most willing to pay/what one actually pays
Producer Surplus
What seller gains the higher they sell for (the difference)
Price goes up, CS goes DOWN, price goes down, CS goes
CS goes UP
How to find the area
Triangle=1/2bh
Quotation Price Elasticity of Demand
=% change in quantity demand / % change in price
For Quotation Price Elasticity of Demand, ALWAYS _______, discard ___
negative #
discard -
For Quot. Price Elast. of Demand:
If #1 =
If less than 1 =
Elastic =
Unitarialistic
Inelastic
Numerator bigger than denominator
Use average in quot. price elast. demand to
minimize wrong if unsure
For Quot. Price Elast. of Demand: num & denom
Start/end up
Price Elasticity of Demand Full Equation

Total Revenue eq
Price firm gets for item TIMES amount sold
Steep line
Inelastic line
More flat line
Elastic line
Sales Tax
Gov taxes seller
Both employee & company _____ for employee’s SS
both pay (employer matches % paid)
Legal Obligation does _____ determine who must pay tax, depends on ______ of supply and demand curves
NOT
Elasticity
Per unit tax
Tax on each unit of item
Deadweight loss
Loss of consumer surplus and producer surplus WITHOUT a gain
If d=elastic and s=inelastic, seller pays _____, buyers pay _____
Seller pays MORE
Buyer pays LESS
If d=inelastic, s=elastic, seller pays _____ and buyers pay _____
Seller pays LESS
Buyer pays MORE
Dead Weight Loss Equation
DWL = 1/2bh
Consumer Theory
Explaining act of individuals choosing to allocate limited income on purchasing limited quantity products
Util
More satisfaction of using something = MORE Utils
Marginal Utility
Extra utility you get by consuming a util of product
Marginal
Extra
Law of diminishing marginal utility (2)
Util get from next unit of product will always be LESS (decreasing)
Will eventually reach 0
Budget Constraint
Limited amount of income available to consumers to spend on goods & services
Utility maximizing conditions equation
Marginal utility / price of item