micro economics
 Call Kai
 Learn
 Practice Test
 Spaced Repetition
 Match
 Flashcards
 Knowt Play
1/42

There's no tags or description
Looks like no tags are added yet.
43 Terms
Availability Heuristic
A mental shortcut in which people base judgments on information that comes easily to mind. “Availability” here concerns memory, rather than inventory. For example, a server’s vivid description of a special is easy to remember and influences the guest’s choice.
Behavioral Economics
The study of how psychology, emotions, and context influence economic decisions. For example, you planned to buy only coffee, but the pastry display prompts you to add a croissant.
Budget Constraint
The combination of goods and services a consumer can afford, given their income and the prices of those goods. It shows the trade-offs a consumer must make when spending limited resources. For example, if you have $15 for lunch, ordering a more expensive sandwich may leave you without enough money for dessert.
Consumer Equilibrium
The spending combination that gives a consumer the greatest satisfaction within their budget and that they cannot improve by reallocating their spending. For example, you have found the combination of tacos and drinks that satisfies you most. Spending more on drinks and less on tacos would leave you less satisfied.
Cost-Benefit Analysis
An economic decision-making process that compares the costs and benefits of a policy, project, or investment to determine its overall value and feasibility.
Costs
The expenses or sacrifices made to obtain something, including opportunity cost.
Credit
An agreement that lets an individual or firm obtain goods, services, or money now in exchange for a promise to repay later with interest. Confidence and expectations about the future influence how people use ____.
Demand
The quantity of a good that consumers are willing to purchase at various prices.
Diminishing Marginal Utility
A principle stating that as a person consumes more units of a good, the additional satisfaction from each extra unit decreases. The first slice of pizza might bring great pleasure, but by the fourth or fifth, the added enjoyment is much smaller.
Economic Equilibrium
The point at which supply equals demand for a product
Economic Growth
The increase in the production of goods and services in an economy over time, typically measured by the rise in real Gross Domestic Product (GDP).
Exchange Value
The worth of a good or service is determined by what it can be traded for in the market, typically expressed in monetary terms (the price). This contrasts with use value, which is based on the intrinsic benefits derived from consuming the good.
Income Effect
The change in a consumer’s purchasing behavior when their real income (or purchasing power) changes, holding prices constant. If income rises, people can usually buy more of most goods.
Inferior Good
A product or service whose demand decreases when consumer income rises and increases when consumer income falls. It has a negative income elasticity of demand, meaning demand moves inversely to changes in real income (YED < 0).
Loss Aversion
The tendency to feel the pain of a loss more strongly than the pleasure of an equivalent gain. Losing a $10 café voucher bothers you more than finding a $10 voucher makes you happy.
Marginal Utility
The additional satisfaction a consumer gets from consuming one more unit of a good or service. It shows how much utility changes with each extra unit.
Marginal Utility per Dollar
The additional satisfaction received for each dollar spent. Calculate it by dividing marginal utility by price: MU ÷ Price. Example: Another taco provides 12 units of satisfaction and costs $3. Its marginal utility per dollar is 4.
Markets
Systems or places where buyers and sellers interact to trade goods or services (with transactions). Example, you carefully budget money earned at work but freely spend a $50 birthday gift on an expensive dinner.
Mental Accounting
Treating money differently depending on its source or the category you mentally assign it to, even though each dollar has the same purchasing power.
Motivation Effects
The economic impacts of incentives and disincentives on individual or firm behavior, particularly in response to wages, taxation, or policy changes. These effects influence productivity, labor supply, and investment decisions.
Normal Good
Any product or service for which demand increases when consumer income rises, and decreases when consumer income falls. These goods have a positive income elasticity of demand (YED > 0), meaning purchasing power and quantity demanded move in the same direction.
Opportunity Cost
The value of the best alternative sacrificed as compared to what actually takes place. The value of the next best alternative forgone when making a choice, reflecting the trade-offs involved in economic decision-making. (Used for calculating comparative advantage).
Optimal Point
The equilibrium where marginal cost equals marginal benefit (the supplier gets the highest price; the consumer gets the maximum satisfaction).
Pain of Paying
The psychological discomfort associated with spending money. Combining purchases into one price can reduce attention to each separate cost. For example, a guest feels more comfortable ordering a $30 three-course meal than considering three separate charges.
Price Bundling
Selling two or more items together for one combined price, often emphasizing value and convenience. A sandwich, fries, and drink offered together as a $15 lunch combo.
Price Discipline
Firms' adherence to stable pricing strategies, often within an industry, to avoid destructive price competition. This can be enforced through tacit collusion, market expectations, or regulatory policies.
Price Stability
A condition in which inflation and deflation are kept at moderate, predictable levels, ensuring that the purchasing power of money remains relatively constant over time.
Price-Quality Trade-Off
The economic principle that suggests higher-quality goods often cost more, leading consumers to decide what they're willing to pay for perceived quality improvements.
Resources
Inputs used to produce goods and services, including land, labor, and capital.
Scarcity
Unlimited desire for goods and services exceeds our limited ability to produce them due to constraints on time and resources. The fundamental economic problem of limited resources versus unlimited wants. A server says, “We have only three portions of tonight’s fresh halibut left.”
Scarcity Cues
Messages signaling that a product has limited availability, which can make it seem more desirable or create urgency to buy.
Shock and Awe
a marketing strategy in which a business presents a high-priced, surprising product to capture attention. For example, a bottle of champagne that costs $1 million.
Substitution Effect
The change in consumption that happens when the price of one good changes, making it more or less attractive relative to other goods. For example, if coffee becomes expensive, consumers may substitute it with tea.
Supply Restraint
A situation where the availability of a good or service is intentionally or unintentionally limited, often leading to price increases. This can result from strategic decisions (such as Hermes intentionally limiting production of the Birkin handbag) to maintain high prices.
Supply
The quantity of a good or service that producers are willing to offer at various prices.
Sustainable Growth
Economic growth that meets present needs without compromising the ability of future generations to meet theirs, balancing economic expansion with environmental and social responsibilities.
Total Utility
The total amount of satisfaction or pleasure a consumer gains from consuming a certain quantity of goods or services. It measures overall happiness from all units consumed.
Utility Maximization
Choosing the combination of purchases that gives you the greatest total satisfaction within your budget. For example, you choose a sandwich and soup instead of a larger sandwich because that combination gives you more satisfaction for your $15.
Utility Value
A conceptual measure of worth that is not tied to a specific tangible good or service but rather represents an underlying economic or social principle, such as satisfaction, desirability, or cultural significance.
Value
The importance, worth, or usefulness of something in economic terms. Price is what you pay, ____ is what you get.
Veblen Effect
A phenomenon where higher prices increase the desirability of a good because it serves as a status symbol. Unlike normal goods, demand for Veblen goods rises as prices increase, contradicting the typical law of demand.
10 principles of Microeconomics: O PIGS FISTS
Opportunity cost, Price stability, Incentives, Global trade, Scarcity, Fiscal Policy, Inflation and employment, Supply and Demand, Trade-offs, Sustainable economic growth
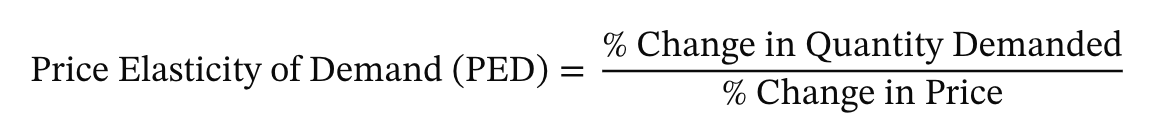
Price Elasticity of demand
Measures how much consumer demand for a product changes when its price changes. It is calculated by dividing the percentage change in quantity demanded by the percentage change in price.