Analysis of Financial Statements exam 2
 Call Kai
 Learn
 Practice Test
 Spaced Repetition
 Match
 Flashcards
 Knowt Play
1/33

There's no tags or description
Looks like no tags are added yet.
34 Terms
Gross Profit Margin
Multiply by 100 to get a percentage
Why it changes: selling prices, product costs, competition, product demand, product mix, and sales volume can affect gross profit margin
A high and increasing gross profit margin is generally better, while a low or decreasing margin can signal increased competition, lower demand, or higher product costs

DuPont Framework
Shows that a company can increase ROE in three main ways:
Increase profitability: Earn more net income per dollar of sales by increasing profit margins
Increase asset efficiency: Generate more sales from the company’s assets by increasing total asset turnover (aka ROA)
Increase financial leverage: Use more debt relative to equity, which can increase ROE but also increases financial risk
a higher ROE does not automatically mean a company is performing better operationally

RNOA (Return on Net Operating Assets)

NOA (Net Operating Assets)
= Operating Assets — Operating Liabilities
Operating Assets:
Accounts Receivable
Inventories
Prepaid Expenses / Supplies
PP&E and Right-of-Use assets
Intangible assets and Goodwill
Deferred tax assets
Equity method investments
Operating Liabilities:
Accounts payable
Accrued expenses
Unearned (deferred) revenue
Income taxes payable
Deferred tax liabilities
Pension obligations
Other post-employment benefits
NOPM (Net Operating Profit Margin)
reveals how much operating profit the company earns from each sales dollar

NOAT
Measures the productivity of the company’s net operating assets

NOPAT (Net Operating Profit After Tax)
= NOPBT — Tax on Operating Profit
NOPBT (Net Operating Profit Before Tax)
= Sales — Operating Expenses
Operating Expenses:
COGS
SG&A: wages, advertising, occupancy, insurance, depreciation and amortization, litigation, and restructuring expenses
Research and development
Impairments of operating assets such as goodwill
Income from joint ventures, partnerships, and associated companies
Gains and losses on asset disposals
“Other” operating expenses or income
Tax on Operating Profit
= Tax Expense + (Pretax Net Nonoperating Expense* Statutory Tax Rate)
* Tax Shield
Tax Shield
taxes a company saves by having tax-deductible nonoperating expenses
Demand for Credit — Why do companies need to borrow?
A. Operating activities
To pay for materials and labor
To make advance seasonal purchases
To cover operating cash shortages or losses
Companies have cyclical operating cash needs
Manufactures need cash for materials or labor
Advance seasonal purchases
Cash needed for operating activities is not uniformly “low risk”
Cash needed to cover operating losses might not be temporary
A willing lender could make the difference between bankruptcy and continued operations for a company
B. Investing activities
To purchase property, plant, and equipment (PP&E)
To purchase intangible assets
To finance mergers and acquisitions (M&A)
Companies require large amounts of cash for investing activities such as the purchase of property, plant and equipment or for corporate acquisitions
New PP&E (CAPEX)
Intangible assets
Mergers & acquisitions
C. Financing activities
To repay a maturing bank loan or bond
To repurchase company stock
Companies occasionally need credit for financing activities
A bank loan or bond matures
Funds to repurchase stock
Demand for credit refers to why companies need to borrow money. Companies demand credit to fund operating activities, investing activities, and financing activities
Supply of Credit — Where can companies obtain credit?
Source | What it means |
|---|---|
Trade credit | Suppliers let companies buy goods now and pay later, often without interest. |
Bank loans | Banks provide different types of borrowing to meet a company's needs. |
Lease financing | Leasing companies finance the use of assets, such as equipment. |
Publicly traded debt | Companies raise money by issuing commercial paper, bonds, or debentures. |
Types of bank loans and credit facilities
Removing credit line: Provides cash for temporary or seasonal shortages; the balance can be repaid later
Line of credit (backup credit facility): A bank commits to making funds available when needed
Term Loan: Typically used to finance PP&E, with the asset serving as collateral and the loan duration often matching its useful life
Mortgage: Typically used to finance real estate, with the property serving as security
Banks structure financing to meet specific client needs
Revolving credit line (revolvers)
Cash available for seasonal shortfalls
Bank commits to a credit line maximum, balance repaid later in the year
Lines of credit (back-up credit facilities)
Bank provides a guaranty that funds will be available when needed
Term loans (“bank loans)
Typically used to fund PP&E which serves as collateral
Loan duration matches useful life of PP&E
Mortgages
Typically used for real estate transactions
Lender takes property as security
Supply of credit refers to the sources from which companies can obtain borrowed funds. These include trade credit, bank loans, lease financing, and publicly traded debt such as commercial paper, bonds, and debentures
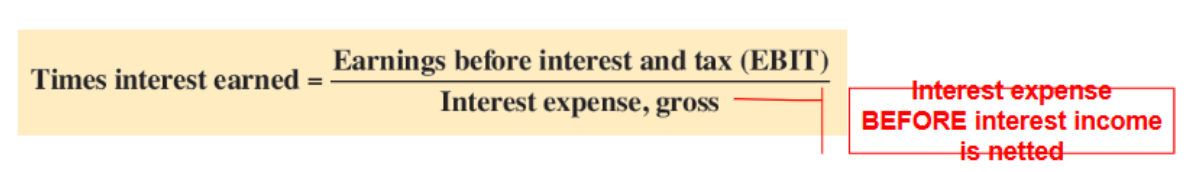
Times Interest Earned Ratio
Measures a company’s ability to cover its interest expenses using its operating income. It assumes the company only needs to pay interest on its debt and can refinance the principal (the amount originally borrowed) when it comes due
Basically, it tells us how easily a company can afford to pay the interest on its debt
A higher ratio generally indicates a stronger ability to cover interest expenses, while a lower ratio indicates greater difficulty paying interest
Cash Flow from Operations to Total Debt
Measures a company’s ability to generate additional cash from its operating activities to cover debt payments as they come due
Basically, tells you whether the company generates enough cash from running its business to help pay its debts when payments are due
Higher ratio: Generally indicates a stronger ability to meet debt obligations
Lower ratio: Generally indicates a weaker ability to meet debt obligations

Free Operating Cash Flow to Total Debt
Measures a company’s ability to pay its debt using the operating cash it has left after paying for capital expenditures (such as purchasing equipment or buildings)
Basically, it shows how much cash a company has available to help pay its debts after spending money on long-term assets

Current Ratio
Measures a company’s ability to pay its short-term debts using the assets it expects to turn into cash or use up within one year
Higher ratio: Generally better because the company has more current assets available to cover its short-term debts
Lower ratio: Generally worse because the company may have difficulty paying its short-term debts when they come due
A ratio below 1.0: Means the company has fewer current assets than current liabilities, which may indicate short-term liquidity problems
A very high current ratio, isn’t always better. It could mean the company isn’t using its assets efficiently

Quick Ratio
Measures a company’s ability to pay its short-term debts using its most liquid assets, without relying on selling inventory
Higher ratio: Generally better because the company has more readily available assets to cover its short-term debts
Lower ratio: Generally worse because the company may struggle to pay its short-term debts using its most liquid assets
A ratio below 1.0: Means the company has fewer quick assets than current liabilities, which may indicate difficulty paying short-term debts
Key difference from the Current Ratio: The Quick Ratio excludes inventory because inventory may take time to sell and turn into cash

Working Capital
= Current Assets — Current Liabilities
The financial resources a company has available to support its day-to-day operations, such as paying employees, buying supplies, and keeping the business running after accounting for its short-term obligations. It indicates the company’s ability to meet its short-term financial obligations and fund its day-to-day operations.
Positive working capital: Current assets exceed current liabilities, generally indicating a stronger ability to cover short-term obligations
Negative working capital: Current liabilities exceed current assets, which may indicate difficulty covering short-term obligations
Higher working capital: Generally provides more short-term financial flexibility, although an excessively high amount can indicate inefficient use of assets
An amount of money $, not a %
Liabilities to Equity
= Total Liabilities / Total Equity
Measures how much a company relies on liabilities compared with the amount of money invested by its shareholders to finance its assets
Higher ratio: The company relies more heavily on liabilities to finance its assets, which generally means greater financial risk because it has more obligations to meet
Lower ratio: The company relies less on liabilities relative to shareholders’ equity, generally indicating lower financial risk
A ratio above 1.0: The company has more total liabilities their shareholders’ equity
A ratio below 1.0: The company has more shareholders’ equity than total liabilities
Total Debt to Equity
= Total Debt / Total Stockholders’ Equity
Measures how much a company relies on debt to finance its operations compared with the amount invested by its shareholders
Higher ratio: Generally means greater financial risk because the company relies more heavily on borrowing and must meet more debt obligations
Lower ratio: Generally means lower financial risk because the company relies less on debt relative to shareholders’ equity
Total Debt to Equity may use only interest-bearing debt, while a broader Liabilities to Equity ratio uses all liabilities
Revenue Recognition Criteria
Revenue is recognized when a company fulfills its promise to provide goods or services to a customer, rather than simply when it receives cash
5 Steps:
Identify the contract — Determine the agreement between the company and the customer
Identify the performance obligations — Determine what goods or services the company promised to provide
Determine the transaction price — Determine how much the company expects to receive
Allocate the transaction price — Divide the price among the different goods or services provided, if there is more than one
Recognize revenue — Record revenue when each promise is fulfilled and the customer obtains control of the good or service. If the service is provided over time, recognize revenue over that period
Important rules and exceptions
Situation | When revenue is recognized |
|---|---|
Sales on credit | When the company fulfills its performance obligation, even if cash hasn't been received yet |
Right of return | Estimate expected returns and subtract them from sales to determine net sales |
Gift cards | When the customer uses the gift card |
Nonrefundable upfront fees | When the promised future goods or services are provided |
Bill-and-hold arrangements | When control of the goods transfers to the customer |
Consignment sales | If the seller acts as an agent, recognize the commission |
Licenses | Depends on the contract: right to use = when available for use; promise of access = over time |
Franchises | Recognize goods when transferred and services as they are delivered |
Variable consideration | Recognize the expected amount to be received, subject to the applicable rules |
Multiple-element contracts | Allocate the price to distinct goods and services and recognize each separately |
Receiving cash does not automatically mean revenue is recognized. Revenue is generally recognized when the company fulfills its promise to the customer.
Cost-to-Cost Method (for long-term contracts)
Recognizes revenue from a long-term contract based on how much of the total expected production cost the company has incurred so far. It spreads revenue recognition over the life of the contract according to the project’s progress.
How it works:
The company compares the costs incurred so far with the total expected costs
That percentage estimates how much of the contract has been completed
The company recognizes the corresponding percentage of the total contract revenue
Ex. If a company has incurred 15% of its total expected costs, it recognizes 15% of the total contract revenue
Net Sales
The total revenue a company earns from selling its goods or services after subtracting sales returns, sales allowances, and sales discounts
Basically, the money the company earns from sales after accounting for reductions to those sales
Example:
Total sales: $100,000
Returned products: $5,000
Sales discounts and allowances: $3,000
Net sales: $92,000
Why it matters: Net sales shows how much revenue the company actually keeps from its sales after these reductions
Unearned (Deferred) Revenue
Money a company receives from customers before it has provided the goods or services, which is recorded as a liability because the company still owes the customer what they paid for
Why it’s a liability: The company has received the money but still has an obligation to fulfill its promise to the customer
When it becomes revenue: Once the company delivers the goods or provides the service, it reduces the unearned revenue liability and recognizes revenue
Examples: Gift cards, advance payments, memberships, and subscriptions
Example: A customer pays $120 upfront for a one-year membership. The company initially records the $120 as unearned revenue because it still owes the customer membership services. As it provides those services, it recognizes the appropriate amount as revenue.
Analyzing unearned revenue:
Unearned revenue increases: Customers are making more advance payments, which may indicate that more revenue and profit will be recognized in the future.
Unearned revenue decreases: The company may be recognizing revenue from payments received in previous periods, while receiving fewer new advance payments. This could signal future declines in revenue and profit.
Important: These are possible indicators, not guarantees. Consider both the dollar amount and the rate of change.
Key distinction to remember: Receiving cash is not the same as earning revenue. A company earns the revenue when it fulfills its obligation to the customer.
Research and Development (R&D) Expense
Costs a company incurs to research new ideas, develop new products, or improve existing products and technology
Examples of R&D costs: Researchers’ salaries, research supplies, software licensing fees, payments to outside collaborators, and research facilities.
Most R&D costs are expensed as incurred: The company records them as expenses when it incurs them, rather than recording them as assets to spread the cost over future years.
Exception — general-purpose property, plant, and equipment (PPE): Equipment or buildings that can serve general purposes are capitalized as assets and depreciated over their useful lives.
Acquired R&D and IPR&D:
In-process research and development (IPR&D): Research and development projects that a company acquires from another company but that have not yet been completed.
When a company acquires IPR&D as part of acquiring another company, it records the IPR&D as an asset.
The asset is not amortized while the associated research is still in progress.
Amortization begins when the project is completed and available for use; if the project is abandoned, the asset is written off.
Key distinction to remember: A company generally expenses its own R&D costs as they occur, but R&D acquired through a business acquisition is recorded as an asset.
ROE is computed as
Net Income Attributable to Controlling Interest / Average Equity Attributable to Controlling Interest
The current ratio is used to assess
Liquidity
Net Operating Profit After Tax (NOPAT) includes operating revenues less expenses such as:
COGS
Taxes on operating
SG&A expenses
An example of a situation in which a company needs credit for investing activities is:
Mergers and acquisitions
When considering the results of an Altman Z-Score analysis, a score of 3.85 would suggest?
The company is healthy and there is a low bankruptcy potential in the short-term
Costco Wholesale Corporation collects annual non-refundable membership fees from customers. When should Costco recognize revenue for these membership fees?
Evenly over the membership year
Ticketmaster contracts with the producer of Blue Man Group to sell tickets online. Ticketmaster charges each customer a fee of $9 per ticket and receives $22 per ticket from the producer. Ticketmaster does not take control of the ticket inventory. Average ticket price for the event is $105.
How much revenue should Ticketmaster recognize for each Blue Man Group ticket sold?
$31 (22+9) because both the fee from the customer and the Blue Man Group producer are earned
Apple, Inc. reported research and development expense of $10,045 million on its 2031 income statement. This expense included many types of costs.
Which of the following types of costs would not be included in the $10,045 million?
Supplies and inventory related to R&D activities and new-product sales
Thomas Company receives information that requires the company to increase its expectations of uncollectible accounts receivable.
Which of the following does not occur on the company’s financial statements?
Accounts receivables (gross) is reduced