aud exam 2 important processes
 Call Kai
 Learn
 Practice Test
 Spaced Repetition
 Match
 Flashcards
 Knowt Play
1/19

There's no tags or description
Looks like no tags are added yet.
Name | Mastery | Learn | Test | Matching | Spaced | Call with Kai | Chat |
|---|
No analytics yet
Send a link to your students to track their progress
20 Terms
COSO
Control Environment, Risk Assessment, Control Activities, Information & Communication, and Monitoring
Audit Committee Duties

Phases of IC Evaluation

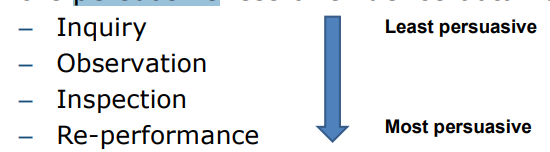
Audit procedures least to most persuasive
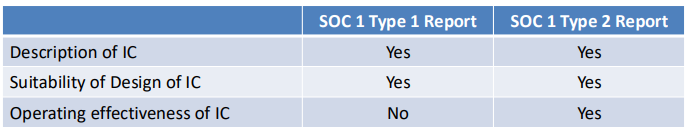
Soc Report Table
Material Weakness Indicators
Prior-year financial statements corrected for misstatement.
Material current-year misstatements found by auditors.
Ineffective audit committee oversight.
Senior management fraud suspected.
Significant Deficiencies Indicators
– Absence of appropriate separation of duties.
– Absence of appropriate reviews and approvals of transactions.
– Evidence of failure of control procedures.
Auditing bank reconciliation steps
Balance per bank → add deposits-in-transit → subtract outstanding checks → add/subtract other debit/credit memos → balance per books
Revenue and Collection Cycle Steps
1. Prepare sales order based on purchase order
2. Approve credit (cash sale if no credit is approved)
3. Issue warehouse merch
4. Shipment
5. Invoice preparation and billing
6. Collection of receivable from customers
7. Maintenance of customers’ balance in the A/R ledgers
8. Approval of sales returns and allowances
9. Authorization of ADA write-offs
Revenue and Collection Cycle Activities in Order
receiving and processing customer orders → delivering goods and services to customers → billing customers and accounting for accounts receivable → collecting and depositing cash received from customers.
Acquisition and Expenditure Cycle Activities in order
initiate purchase of goods & services → receiving goods or services → acct department records the asset or expense related liability → pay invoice through cash disbursement process
A/P Completeness: What can go wrong?
Liabilities are not recorded.
A/P Cutoff: What can go wrong?
Liabilities have been recorded in incorrect periods.
A/P Existence: What can go wrong?
Liabilities may not be real.
A/P Rights and Obligations: What can go wrong?
Liabilities may not represent actual obligations of the company.
A/P Valuation: What can go wrong?
Payables are recorded at an incorrect amount.
Completeness of Expenses: What can go wrong?
Not all expenses have been recorded.
Cutoff of Expenses: What can go wrong?
Expenses have been recorded in incorrect periods.
Accuracy of Expenses: What can go wrong?
Expenses are recorded at an