management. lecture 6. Subjectivity.
 Call Kai
 Learn
 Practice Test
 Spaced Repetition
 Match
 Flashcards
 Knowt Play
1/37

There's no tags or description
Looks like no tags are added yet.
Name | Mastery | Learn | Test | Matching | Spaced | Call with Kai | Chat |
|---|
No analytics yet
Send a link to your students to track their progress
38 Terms
performance measures are useful to address agency problems but problems are:
noise problem
congruence problem / bias
noise problem
performance measure can be influenced by uncontrollable factors
for who does the noise problem carry risk
the agent
congruence problem / bias
performance measure does not capture all aspects of what a good employee should do
for who does the congruence problem carry risk
principal
how to deal with noise problems
subjective performance evaluation with noncontractible information.
agency relationship
effort of the agent is unobservable. (true value)
risk averse agents combined with a noisy signal x of the agent's effort
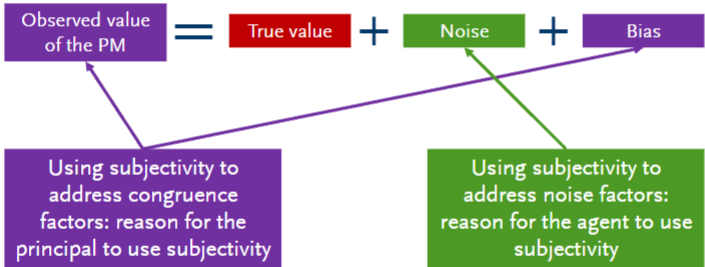
the signal x can be influenced by uncontrollable factors (noise) and can be manipulated by the agent (bias)
fundamental equation of every performance measure
observed value of the PM = True value + noise + bias

what is true value linked to?
effort level a
what is Noise linked to
precision
what is Bias linked to?
congruence. manipulatin the measure
how to correct for weakly congruent performance measures and the influence of noise and bias on the observed value of a performance measure
solution strategy 1: adapt other elements of the stool to correct for the imperfectness of the performance measure.
solution strategy 2: introduce subjectivity
solution stratefgy 1: adapt other elements of the stool to correct for the imperfectness of the performance measure.
adapt the delegation of decision rights so that the agent has less opportunities to bias the performance measure.
focus on improving your reporting system to correct for noise.
only use imperfect performance measures when they fit with the soft controls.
subjective performance evaluation
using noncontractible information that arises during the measurement period asses actions and efforts that are insufficiently captures by objective PM
solution strategy 2: use subjectivity
indicate that you (as a principal) will use other observations to correct for the weakly congruent and/or noisy PM. inform the agent about this on beforehand to ensure sufficient verifiability.
collect information to try to find out which noise compenents could have influenced the observed value of the performance measure
collect information about potential sources of bias
use the observations and collected
why do we not include in the contract how we will deal with 'noise factors'
a lot of the 'noise factors' are unforeseen and unpredictable.
contracting costs: it would be very difficult to try to predict all noise and write contractual clauses for it.
why do we not include in the contract how we will deal with 'congruence facors'?
if people know what you will look for, they could start to fake it.
contracting costs: congruent behavior manifests itself in many different ways and it would take a lot of time to describe this
different types of subjective performance evaluation
discretionary bonus (there is formula but bonus can be adjusted in post)
subjective weights (no formula)
why is it a good idea to include (mainly nonfinancial) performance measures?
informativeness principle
the informativeness principle
compensation contracts should include any costless measure that carries incremental information on the agent's actions. From the moment a performance measure provides additional information that is not captured by other performance measures, this performance measures should then be included in the formula based bonus contract.
what is subjectivity in compensation contracting used for?
to imporove congruence-,noise-, and bias-related problems that are intrinsically linked to the use of performance measures
when does subjectivity increase several outcomes and which
performance and satisfaction, but only when it is applied in a trusting environment.
disadvantages of subjective performance evaluation
you open the door for favoritism, supervisor biases, and influence activities.
the appropriate information needs to be collected: takes time or money.
when not to use subjectivity
in 'easy' environments and environments with behavioral controls
the biases in subjective performance evaluation
leniency bias
centrality bias
leniency bias
supervisors are reluctant to give low ratings
centrality bias
supervisors give medium ratings a lot more.
individual approach
you supervisor observes the available performance measures, collects additional information and makes the adjustment if he considers that reasonable.
problems with individual approach towards subjectivity
performance evaluation not a better reflection of the employee's effort because collecting additional information is costly.
centrality bias and leniency bias.
inconsistency: different supvisors have different criteria.
flexible teams: employees often work for different supervisors.
collective approach towards subjectivity
calibration committee. collection of supervisors.
disadvantage of calibration committee
increase the centrality bias
time to prepare and attend calibration committee
advantage of calibration committee
more consistency across supervisors
lower leniency bias.
supervisor learning about performance evaluation.
supervisors collect more information
what is subjectivity used to address
noise and congruence problems that drive the observed value of a performance measure.
what is a crucial component to make subjectivity work?
trust
the forms that subjectivity in performance evaluation arises in
subjectivity as an ‘add-on’ to an objective performance evaluation:option to ex-post override a formula-based contract.
subjectivity as an ‘integral component’ of the performance evaluation: no formula but performance measure are agreed on beforehand.
subjective performance evaluation can be based on
other objective performance measures
subjective performance measures that can be quantified
personal observations of the one/team who is doing the subjective performance evaluation
combinations of the above
reason for the agent to use subjectivity
using subjectivity to address noise factors
reasons for the principal to use subjectivity
to address congruence factors