AC105 - Week 6
 Call Kai
 Learn
 Practice Test
 Spaced Repetition
 Match
 Flashcards
 Knowt Play
1/45

There's no tags or description
Looks like no tags are added yet.
46 Terms
What is inventory costing
An entity must determine the cost of goods sold during the period and the cost of goods remaining at the end of the period
What are the 3 most common methods of costing inventories
FIFO
AVCO
LIFO
What is FIFO
First in First Out - Goods bought or produced first are sold first
What is AVCO
Weighted average cost - Weighted average cost of the inventory held (after each inventory acquisition takes place)
What is LIFO
Last in first out - Goods that are bought or produced last are sold first
When does FIFO give higher profits
During periods of increasing prices but vice versa during decreasing prices
What is an intangible asset
An identifiable non-monetary asset without physical substance
What are the 4 requirements to recognise an intangible asset
1) Identifiable
2)Under Control of the Entity
3)Produces Economic Benefits
4) Reliably measurable
What does it mean for an asset to be identifiable
An asset is identifiable if it is either separable or arises from contractual or legal rights
What are the 3 ways in which a company may obtain an intangible asset
1) Separate acquisition
2) Acquisition as part of a business combination
3) Internally generated assets
Why does a separate acquisition allow a company to obtain an intangible asset
- The cost can be measured (=price paid)
- It is identifiable (as it can be bought or sold)
- The purchase transaction is an indication that economic benefits are probable
- The entity has control over the asset
Why does an acquistion as part of a business combination allow a company to obtain an intangible asset
When a company buys another company and they produce a combined balance sheet, they have to include intangible assets (like brand names or customer lists) in the balance sheet, even if the company they bought didn't recognise these intangibles in their separate balance sheet
What is the issue with identifying internally generated intangible assets
difficult to demonstrate that their cost can be reliably measured and that there are expected future economic benefits
What is one of the only cases internally generated intangible assets can be identified
Research and Development
Internally generated intangible assets: Research and Development explained
Research phase costs are expensed and not identifiable however development costs are capitalised (identifiable as an asset) if certain conditions are met
What should an intangible asset be cost at
an intangible asset should be carried at its cost less any accumulated amortisation and any accumulated impairment losse
When can the revaluation model only be applied
The model can only be applied if there is an active market for that type of intangible asset
What is the condition for amortisation
The asset has a finite life
What is the partnership agreement
The partnership agreement provides how partners will share profits and losses
What does the law assume about net income distribution
The law assumes the net income is to be divided among the partners proportionally to the capital contributed
What are the 2 types of money a partner receives
A stated salary or stated percentage interest on the contributed capital or a combination of both
and
A stated share of residual profit after salaries
What are ordinary shares
The basic unit of ownership
What is the nominal (par) value of shares
The value of a share determined at initial public offering (IPO)
What is the difference between market value and nominal value known as
The share premium
What are the 2 types of shares
Ordinary shares and Preference shares
Characteristics of ordinary shares
Basic form of finance
If the business closes down, the ordinary shareholders receive proceeds after lenders, creditors and preference shareholders
Ordinary shareholders have voting rights
Ordinary shareholders benefit from dividends and appreciation of share market price
High risk high return
What are preference shares
A fixed rate of dividend each year
When are preference dividends paid
Before ordinary dividends
Characteristics of preference dividends
Where a business is closed down, preference shareholders have priority over the claims of ordinary shareholders
Preference shares do not have voting rights
Low risk low return
What are the 2 reserves that are non distributable
Share premium
Revaluation reserve (such as upward revaluations of non-current assets)
What is the distributable reserve
Retained earnings
What is a dividend
A dividend represents a drawing by shareholders of a company
What are the 2 types of dividends
An interim dividend
A final dividend
What is an interim dividend
An interim dividend is paid halfway through the accounting year, when the profit for the first six months is known. The amount is decided by the directors.
What is a final dividend
The final dividend is additional to the interim dividend and, although it relates to the same accounting year, is paid just after the end of the year
The final dividend has to be approved by the equity shareholders at the annual general meeting (AGM), and this is always held after the end of the accounting year when the profit for the year is known.
What is important to know about ordinary dividends
Ordinary dividends are not a business expense, therefore they are not deductible for tax purposes and will not appear on the Income Statement
What is the double entry for interim dividend declared
DOWN Dividends
UP Dividends payable (current liability, SOFP)
What is the double entry for interim dividend paid
Dr Dividends payable (current liability, SOFP)
Cr Bank
What is important to note about a proposed dividend
Proposed dividends are not included in the financial statements. Proposed dividend cannot be accounted for because, until it is declared, it would not qualify to be regarded as a liability.
How do profits impact capital
Profits increase capital
How do dividends impact capital
Decreases capital
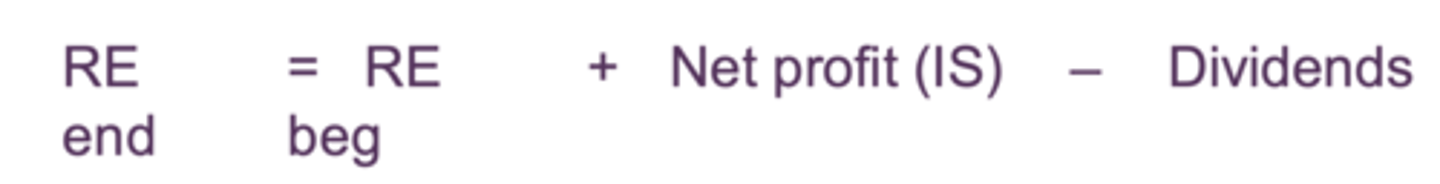
What is the equation for retained earnings
RE=RE (beg) + profit/loss - dividends
What is the relationship between taxable profit and accounting profit
Taxable profit is NOT equal to accounting profit (before tax)
What are capital allowances
A tax deductible form of depreciation
What is the double entry for corporation tax
UP Tax expense (Income Statement)
UP Tax liability (SOFP)
What is the concept of tax over/under provision
Last period's actual tax paid is likely to have been different from the estimated charge that went through the income statement
The difference needs to be included in this period's tax charge, either as an extra charge (if the tax paid was higher than the charge to the last period's income statement) or as a reduction (if the tax paid was lower)
This ensures that the whole tax bill hits retained profits at some point.