Chapter 19 - Share-Based Compensation & EPS
 Call Kai
 Learn
 Practice Test
 Spaced Repetition
 Match
 Flashcards
 Knowt Play
1/58

There's no tags or description
Looks like no tags are added yet.
59 Terms
Share-based compensation is best described as:
a. Paying employees a fixed cash bonus tied to the company’s annual sales growth
b. Paying employees in shares that the company must buy back at par value later
c. Paying employees with a form of payment tied to the value of the company’s stock
d. Paying employees a guaranteed return tied to the interest rate on company debt
C
Which pair of steps describes the accounting for share-based compensation?
a. Measure the fair value of the compensation, then expense it over the service period
b. Measure the fair value of the compensation, then expense it all on the grant date
c. Measure the intrinsic value at exercise, then expense it over the service period
d. Measure the fair value at the vesting date, then expense it when the shares vest
A
Why bother doing share-based compensation?
a. It guarantees employees a fixed return regardless of company performance
b. It lets the company avoid recording any compensation expense
c. It reduces the number of shares the company has outstanding
d. It gives an incentive to perform better and stay with the company
D
The two primary types of restricted stock plans are
a. Restricted stock awards and stock appreciation rights
b. Restricted stock units and employee share purchase plans
c. Stock options and employee share purchase plans
d. Restricted stock awards and restricted stock units
D
Which of the following describes a restricted stock award?
a. A right to receive shares in the future once the vesting requirement is met
b. A right to buy a set number of shares at a set price during a set period
c. Shares awarded in the employee’s name that cannot be sold during vesting
d. A payment equal to the rise in share price, with no shares ever purchased
C
A restricted stock unit (RSU) is
a. Shares issued in the employee’s name on the grant date and held in escrow
b. A right to receive a set number of shares in the future after vesting
c. A right to buy a set number of shares at a fixed price for a fixed period
d. A discount offered to employees who buy shares through a payroll plan
B
What happens to restricted stock awards if the employee is terminated?
a. The shares are forfeited
b. The shares are sold at par value
c. The shares vest immediately
d. The shares are paid out in cash
A
When does a company distribute the shares of Restricted Stock Units?
a. On the date the RSUs are granted to employees
b. After the recipient satisfies the vesting period
c. Whenever the employee requests the shares
d. At the end of the year the RSUs are granted
B
A restricted stock unit (RSU) award is considered a liability when
a. The employee must satisfy a multi-year vesting requirement
b. The company issues the shares in the employee’s name at grant
c. The shares are valued at the grant-date market price
d. The employee will receive cash or can elect to receive cash
D
Restricted stock awards and restricted stock units are valued at
a. The market price of an unrestricted share on the grant date
b. The market price of an unrestricted share on the vesting date
c. The par value of the shares multiplied by the number granted
d. The average market price of the shares over the service period
A
Each year of the service period, restricted stock compensation is recorded with a debit to Compensation Expense and a credit to
a. Paid-In Capital—Share Repurchase
b. Paid-In Capital—Restricted Stock
c. Paid-In Capital—Excess of Par
d. Paid-In Capital—Stock Options
B
What happens to the compensation expense recorded for restricted stock when an employee forfeits?
a. The expense stays on the books and is reclassified to retained earnings
b. The expense is kept and an offsetting gain is recorded on the shares
c. The earlier entry is reversed for those employees in the year of forfeiture
d. No adjustment is made until the remaining shares fully vest
C
A stock option gives the holder the right to
a. Receive shares for free once a vesting requirement has been satisfied
b. Sell shares back to the company at a price set in advance
c. Receive cash equal to the increase in the share price over time
d. Purchase a set number of shares at a set price during a set period
D
The intrinsic value of a stock option is
a. The option price minus the market price of the shares
b. The market price of the shares minus the option price
c. The fair value of the option minus the exercise price
d. The market price of the shares plus the option price
B
Compensation for stock options is now measured as
a. The fair value of the options at the grant date
b. The intrinsic value of the options at the exercise date
c. The fair value of the options at the vesting date
d. The intrinsic value of the options at the grant date
A
Which of the following is NOT an input to an option pricing model such as Black-Scholes?
a. Expected dividends over the option’s term
b. Exercise price set by the option contract
c. Current market price of the stock
d. The company’s retained earnings balance
D
Stock option compensation is accrued each year with a debit to Compensation Expense and a credit to
a. Paid-In Capital—Excess of Par
b. Paid-In Capital—Restricted Stock
c. Paid-In Capital—Stock Options
d. Liability—SAR Plan
C
How is Compensation Expense for Stock Option Plans recorded?
a. As an equal amount over the required service period
b. All at once on the date the options are granted
c. All at once on the date the options are exercised
d. In proportion to the change in stock price each year
A
How may a company handle forfeitures of stock options?
a. Estimate forfeitures up front or account for them as they actually occur
b. Estimate forfeitures up front, but never revise the estimate later
c. Account for forfeitures only when the remaining options are exercised
d. Ignore forfeitures until the remaining options expire unused
A
After stock options vest, the accounting depends on whether the options are
a. Granted at the market price or below the market price
b. Exercised by the holder or left to expire unused
c. Measured at intrinsic value or at fair value
d. Settled in cash or settled through share issuance
B
Some stock option plans specify a condition that must be satisfied before employees are allowed the benefits of the award. What are the two types of conditions?
Performance-based
(Examples: EPS, Revenue, Revenue Growth)Market-based
(Examples: Target stock price or Stock return)
For a performance-based option plan, compensation expense is initially recorded
a. In every case, regardless of whether the target is likely to be met
b. Only once the performance target has actually been achieved
c. Only if the company’s stock price reaches a set level
d. Only if it is probable that the performance target will be met
D; 70-75%
Which of the following is a market-based condition?
a. Reaching a target earnings per share
b. Reaching a target sales level
c. Reaching a target stock price
d. Reaching a target revenue growth rate
C
Match the following scenarios regarding Plans with Performance-Based Conditions with their proper accounting treatment:
It’s not probable that the performance-based measure will be met
It’s probable that the performance-based measure will be met
The assessment of probability changes in future periods
No compensation expense recorded
Compensation expense will eventually be adjusted
Compensation expense is recorded as usual
No compensation expense recorded
Compensation expense is recorded as usual
Compensation expense will eventually be adjusted
How is compensation expense treated when an award has a market-based condition?
a. Recognized only if the market condition is ultimately met
b. Recognized whether or not the market condition is met
c. Recognized only if it is probable the condition will be met
d. Reversed if the market condition is not met by the end date
B; no special accounting treatment required
Which of the following is a criterion for an employee share purchase plan to be noncompensatory?
a. All employees can participate
b. Employees have no longer than one month after the price is fixed to decide whether to participate
c. The discount offered to employees is no greater than 5%
d. All of the above
D
If an employee share purchase plan fails the noncompensatory criteria, the company records
a. The sale like any other issuance of shares, with no expense
b. The full price paid by employees as compensation expense
c. The discount given to employees as a charge to retained earnings
d. The discount given to employees as compensation expense
Bonus: What if the plan meets the criteria?
D
Bonus: The sales of new shares do not result in compensation expense.
_____ Permits employees to buy shares directly from their company without brokerage fees at a slight discount.
a. Restricted Stock Unit Plans
b. Stock Appreciation Rights Plans
c. Employee Share Purchase Plans
d. Executive Stock Option Plans
C
Stock appreciation rights (SARs) enable an employee to
a. Benefit from a rising share price without having to buy shares
b. Buy shares at a fixed price that is below the market price
c. Receive shares for free once the vesting period has ended
d. Sell shares back to the company at a guaranteed price
A
The appreciation an employee receives from a SAR is calculated as
a. The exercise price minus the market price on the exercise date
b. The market price on the exercise date minus the exercise price
c. The market price on the grant date minus the exercise price
d. The fair value on the grant date minus the exercise price
B
The accounting for Stock Appreciation Rights (SARs) dependes on whether the award is treat as
a. Revenue or an expense
b. An asset or a liability
c. Current or noncurrent
d. Equity or a liability
D
A SAR award is accounted for as equity when
a. The employee can elect to receive cash upon settlement
b. The SARs have fully vested before the end of the year
c. The employer can elect to settle in shares rather than cash
d. The SARs are exercised before they expire
C
A SAR award is accounted for as a liability when
a. The SARs have not yet reached the end of their vesting period
b. The SARs are exercisable at a price above the market price
c. The employer can elect to settle in shares of stock
d. The employee will receive cash or can elect to receive cash
D
For SARs payable in shares (equity), the total compensation
a. Is not revised for later changes in the fair value of the SARs
b. Is remeasured each period until the SARs are exercised
c. Is revised only during the vesting period for fair value changes
d. Is remeasured at the exercise date for the final fair value
A
When is the fair value of the Stock Appreciation Rights (SARs) estimated?
a. On the grant date
b. On the vesting date
c. On the exercise date
d. On the expiration date
A
For SARs payable in cash (liability), the fair value is re-estimated
a. Each period, but only until the end of the vesting period
b. Each period until the SARs are exercised or expire
c. Only on the grant date and the exercise date
d. Only in the years the employee elects to receive cash
B
Restricted stock units (RSUs) payable in cash are accounted for the same as
a. A restricted stock award
b. A stock option
c. A SAR payable in cash
d. A SAR payable in shares
C
Sometimes, Restricted Stock Units is given the cash equivalent instead of shares. The award, from an accounting perspective, is treated as a(n):
a. Equity
b. Liability
c. Asset
d. Contra-equity
B
Note: Until it’s paid, the liability is periodically adjusted based on the stock’s actual value
T/F The liability generated from paying Restricted Stock Units with cash is periodically adjusted to actual value.
True
Which statement about EPS reporting is correct?
a. All firms report both basic and diluted EPS regardless of structure
b. All firms report diluted EPS only, since it is more conservative
c. Firms report basic EPS, plus diluted EPS only if net income is high
d. All firms report basic EPS, and complex firms also report diluted EPS
D
The primarily goal of the accounting rules regarding EPS is to
a. Maximize reported earnings by allowing flexibility in the way EPS is calculated
b. Maximize accuracy by customizing the way EPS is calculated for each firm
c. Minimize reporting costs by letting firms choose any EPS measure they prefer
d. Maximize comparability by minimizing inconsistencies in the way EPS is calculated
D
What is the formula for Basic EPS?
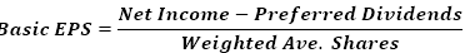
A firm has a complex capital structure when
a. It has more than one class of stock outstanding
b. It has any potential common shares outstanding
c. It has issued bonds of any kind to investors
d. It has declared a stock dividend or stock split
B
Securities that are not common stock but could become common stock through their exercise or conversion (Such as stock options, convertible bonds, or convertible preferred stock) are called:
a. Potential Common Shares
b. Antidilutive Common Shares
c. Treasury Common Shares
d. Restricted Common Shares
A
Diluted EPS is calculated
a. As if the potential increase in shares has already occurred
b. Using only the shares that are actually outstanding
c. Ignoring potential common shares to reflect actual performance
d. Using only potential shares from convertible bonds
A; assumes the worst case scenario!
Basic EPS focuses only on the shares that
a. Could become outstanding
b. Actually are outstanding
c. Will always be outstanding
d. None of the above
B
Options, Rights, and Warrants give holders the right to
a. Receive common stock at no cost after vesting
b. Sell common stock back to the company at par
c. Purchase common stock at a specified exercise price
d. Receive cash equal to the increase in share price
C
If Options, Rights, and Warrants are exercised, what will happen?
a. The number of shares outstanding will increase
b. The number of shares outstanding will decrease
c. The number of shares outstanding will stay the same
d. The company’s treasury stock balance will increase
A
When calculating the dilution from stock options, the options are assumed to be exercised
a. At the end of the period, or when they expire
b. At the midpoint of the period, or when granted if later
c. At the start of the period, or when issued if later
d. On the date the options become fully vested
C
In the dilution calculation for stock options, the cash proceeds from the assumed exercise are used to
a. Repay as much of the company’s outstanding debt as possible
b. Buy back as many shares as possible at the average market price
c. Pay additional dividends to the common shareholders
d. Fund the share issue costs of the new shares issued
B
Convertible securities can be converted into shares at the option of the
a. Board of directors of the company
b. External auditors of the company
c. Majority of the common shareholders
d. Holder of the convertible security
D
The potentially dilutive effect of convertible securities is reflected in Diluted EPS by pretending they were:
a. Converted into common stock at the beginning of the period
b. Converted into common stock at the end of the reporting period
c. Converted into common stock at the midpoint of the period
d. Redeemed for cash at the beginning of the reporting period
A
For convertible bonds in diluted EPS, the numerator and denominator are adjusted by
a. Adding after-tax interest savings and adding shares from conversion
b. Subtracting the interest expense and adding shares from conversion
c. Adding full pre-tax interest savings with no change in shares
d. Making no numerator change and adding shares from conversion
A
For convertible preferred stock in diluted EPS, the numerator and denominator are adjusted by
a. Subtracting preferred dividends and adding shares from conversion
b. Making no numerator change and adding shares from conversion
c. Adding back the preferred dividends and adding shares from conversion
d. Adding back after-tax preferred dividends and adding shares from conversion
C
Securities whose assumed conversion or exercise would increase EPS are called
a. Dilutive securities
b. Antidilutive securities
c. Contingent securities
d. Noncumulative securities
B
Antidilutive securities are
a. Included in diluted EPS, but left out of basic EPS
b. Included in basic EPS, but left out of diluted EPS
c. Included in both EPS figures, but at a reduced weight
d. Ignored when calculating the reported EPS figures
D
Stock options are antidilutive when
a. The exercise price is higher than the average market price
b. The exercise price is lower than the average market price
c. The options were granted in a prior year and are fully vested
d. The options will expire within the next twelve months
A
When the exercise price is above the average market price, options are antidilutive because
a. Fewer shares are bought back than were sold, which lowers EPS
b. The proceeds are too small to repurchase any shares at all
c. More shares are bought back than were sold, which raises EPS
d. The exercise price reduces the numerator of the EPS fraction
C
Anti-dilutive Securities
If the incremental effect of conversion < Basic EPS, the security is ______ (Dilutive/Antidilutive)
If the incremental effect of conversion > Basic EPS, the security is ______ (Dilutive/Antidilutive)
Dilutive
Antidilutive