Econ Unit 2 Exam
 Call Kai
 Learn
 Practice Test
 Spaced Repetition
 Match
 Flashcards
 Knowt Play
1/56

There's no tags or description
Looks like no tags are added yet.
57 Terms
Technology
Techniques firms have available to produce products
Explicit Cost & ex (2)
Cost involves paying money to input owners when acquiring rights to use inputs
Ex: Wages paid to laborers
Implicit Cost & ex (2)
Non-monetary opportunity cost of using inputs
Ex: Such as the income an owner-manager could earn if they worked for someone & the interest an owner-manager invests it own financial capital.
Explicit costs of running firms are EASY to identify:
Just look at what firm spends money on.
Finding implicit costs & ex (2)
Identify resources used in firm that could have been used for another beneficial purpose
Ex: I could’ve earned $120k! (opportunity cost)
q of some product producing =
= f(q inputs that went into making product)
Marginal Product
Extra quantity produced when using extra quantity of input.
Marginal Product of Labor equation and explanation (2)
Marginal Product of Labor =(Δq products / Δ q labor)
Extra quantity of product from adding extra quantity of labor.
Δ meaning
Means extra
Diminishing marginal product / returns
Marginal Product decreases over time
Firms pick up ____ employees FIRST and ____ employees LAST
Best
Worst
Marginal Product Graph looks like
Looks like Parabola
Variable Costs
Costs that CHANGE as quantity of product (output) produced changes
Fixed Cost
Costs that DON’T CHANGE as quantity of product (output) produced changes (varies)
Total Cost
Cost of ALL INPUTS a firm uses in production of a product
TC = FC + VC in _____ Run
Short Run
TC = VC in _____ Run
Long Run since fixed resources DO NOT exist in long run
1st Equation of MC Product
MC product = Δ C / Δ q product
2nd Equation of MC Product
MC Product = ΔTVC/ Δq product
2nd Equation in writing of MC Product
Price of variable input / M Product of variable input
3rd Equation of MC Product
Wage per labor/ MP labor
The BIGGER MP labor gets…
The SMALLER the MC Product gets

As you hire more people
MP labor DIMINISHES

As more of product is produced, MC Product
MC Product INCREASES
Increasing MC Product = caused by
Caused by diminishing MP labor
If marginal value of what was added = LESS than average value, then
Average value of thing will FALL
If marginal value of what was added = GREATER than average value, then
Average value of thing will RISE
The average value of something will ____ change as much as Marginal Value changes
NEVER change as much as
Marginal Cost (MC) Curve equation
ΔTVC/ Δq

On graph, MC = AVC, AVC is @ ______
AVC is @ MINIMUM
3 types of average total costs
Average VARIABLE Cost (AVC)
Average TOTAL cost (ATC)
Average FIXED cost (AFC)
TC equation
TC/q = TVC + FC/q
AFC Equation
AFC = F̄C̄/q
On last unit produced, MR = MC. Only this can be true because
Because business will be making profit
If MR > MC, or MR < MC, firm ____ be producing a profit maximizing or loss minimizing
CAN’T be producing a profit maximizing or loss minimizing
Perfect competitive firm, degree of compet, def, ex + price ______ (4)
Highest degree of competitiveness for that one firm
One firm among many firms producing an identical product
Ex: Agriculture
Price TAKER
Monopolist firm, def, degree of compet (2)
Only one firm producing a product
Lowest degree of competitiveness (Almost no competitiveness for that one firm)
Monopolistic-competitive firm, def & degree of compet (2)
One firm among many firms producing a similar product not an identical product
High degree of compet but LESS than perf compet firm
Oligopolist firm, def & degree of compet (2)
One firm among a few firms producing a product
Low degree of compet.
All other types are price ____ (figure out best price to charge) while perf compet firm is price ____ (2)
Price SEARCHERS
Price TAKER
Perfectly competitive firm line = (2)
Horizontal (price curve)
Cannot raise price, MUST CONFORM

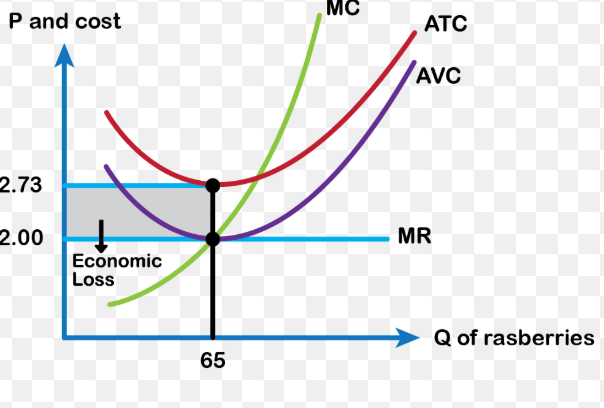
Price above TAC =
= Profit

Price below TAC =
= Loss
Economic profit = Total ….
= Total revenue MINUS total cost (P - ATC)
If on last unit produced MR will ____ MC, in order to profit Maximize or Minimize
MR=MC
Unit costs CANNOT be ____ than described by curve of assumption
CANNOT be LOWER
Perf compet faces ___________ to enter or exit market
No real barriers
Whenever price is ____ VC, firm will ______, not worth it. (2)
BELOW
SHUT DOWN
Productive efficiency (Technical Pov)
Firm produces product at LOWEST POSSIBLE AVERAGE COST (product efficient)
Allocative Efficiency (2)
Producing quantity optimal to society (What makes society best off)
Marginal Benefit of consumers = marginal cost of producing it
Price > ATC =
Price > ATC = Economic PROFIT
Price < ATC =
Price < ATC = Economic LOSS
(Price = ATC) =
Price = ATC = NO GAIN, NO LOSS
Socially Optimal Equation
Socially Optimal: P=MC
Perfect Competitor is Socially Optimal Because…
If P = MR, and MR = MC, then P = MC
In a Monopoly, MR must always be ____ than Price and cannot _____
Must always be LESS than Price and CANNOT BE SAME
Price Searchers are NOT socially optimal because…
If P > MR, and MR = MC
Then P>MC, which is Not Socially Optimal