Chap 16 - Cost allocating joint products and byproducts
 Call Kai
 Learn
 Practice Test
 Spaced Repetition
 Match
 Flashcards
 Knowt Play
1/20

There's no tags or description
Looks like no tags are added yet.
21 Terms
What are joint products?
One of two or more valuable outputs generated simultaneously from a single raw material and a common production process up to a specific point
Not separately identifiable until split off point
Has high sales value
What are byproducts?
Outputs of a joint production process that has a low sales value compared to the sales value of other outputs (e.g. main or joint products)
What is scrap?
Minimal sales value or a cost to dispose
Leftover raw materials, trimmings, shavings, or unusable waste generated during the production process that has a relatively low sales value.
What are joint costs
Costs of a single production process that yields multiple products simultaneously

What is the splitoff point
In a joint production process, it is where two or more products become separately identifiable
What are separable costs
Costs incurred beyond the split off point and are assignable to separate products
Why do we allocate joint costs?
Required for financial statements (to determine inventorial costs and cogs)
Taxation purposes
May be used for internal evaluation purposes (division profitability, manager’s performance)
Cost based contracting
Customer profitability analysis
Insurance settlement computations
Required by price regulators
Litigation
Cost based contracting
An agreement where a project owner/buyer will reimburse the contractor for all actual documented costs (indirect & direct) plus an additional profit margin
Litigation
Formal process of resolving legal disputes through the public court system
Joint cost allocation methods
Physical measures
Allocating using tangible attributes of the products, like pounds, gallons, barrels, etc
Sales value at split off
Net realizable value (NRV)
Constant gross margin percentage NRV
Physical measure method
Allocates joint costs to joint products on the basis of the relative weight, volume, or another physical measure at the split off point of total production of the products

Sales value at split off method
Uses relative sales value at the split off point of the entire production to calculate allocation percentage
Ignores inventories

NRV method
Allocates joint costs to joint products on the basis of relative NRV of total production of the joint products
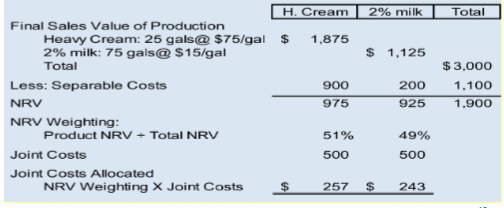
NRV formula is
Final sales value - Separable costs
Constant gross margin NRV method
Allocates joint costs to joint products in a way that the overall GM % is identical for the individual products
GM % being applied identically irrespective of separable costs, results in products with high SC being subsidized/supported by those with lower SC
Means those with higher SC are assigned a lower value of joint costs
Joint costs are calculated as a residual amount

Irrespective
Means ignoring
Which methods are the best?
Split off method → NRV method → Physical measures methods or Constant GM method
Should you Sell or Process Further?
Joint costs are irrelevant in these decisions
Mainly bc JC are sunk
Separable costs need to be evaluated for relevance
What are the methods for accounting for byproducts?
Production method
Sales method
Production method
Recognizes byproduct at the time they are produced (aka at inventory)
Sales method
Recognizes no byproduct at inventory
Bc it is recorded at sale instead
Recognizes only revenue at the time of sales
Byproduct costs are not tracked separately