Research Tax - Chapter 3: Constitutional and Legislative Sources (might add more)
 Call Kai
 Learn
 Practice Test
 Spaced Repetition
 Match
 Flashcards
 Knowt Play
1/9

There's no tags or description
Looks like no tags are added yet.
10 Terms
Sources of Legislative Tax Law
Primary sources of tax law largely stem from statutes—also called legislative or statutory sources
• Changes to IRC passed by Congress and signed by executive branch into statutory law through legislative process.
• U.S. Constitution and international tax treaties also considered legislative tax law.
• Some tax law that stems from legislative activities that are not codified in the Internal Revenue Code (IRC)
U.S. Constitution
• Source for all federal tax law
Congress can impose import taxes but not export taxes.
Rights of due process and privacy of the citizen apply to tax, as well as nontax, environments.
It must be applied uniformly to citizens of all states.
The constitutionality of income taxes has been upheld by courts.
• Estate and gift taxes are excise taxes on transfer of property and deemed constitutional.
Tax Treaties
• Common issues addressed in tax treaties
How business and investment income treated
When foreign person is subject to the host country’s tax law
Methods to offset double taxation of income or assets
How host country computes taxable income for foreigner
How host country’s withholding taxes are applied to foreigner
Extent to which taxes levied by states or provinces are applied to foreigners
Disclosure requirements applied to foreigners
• Conflict between statute and treaty
When the Internal Revenue Code and treaty provide conflicting guidance
Generally, follow “later in time” rule
Courts will try and give equal standing to both and reconcile differences
The Legislative Process

The Legislative
Bills are the text of the proposed law while working through the legislature
Bills that are passed and signed by the U.S. President become laws
Conference committee reports (“Blue Books”) from Joint Committee on Taxation (lower level of authority than a committee report—still used to show legislative intent)
Committee Reports and Conference Committee Reports
Committee reports are produced at each step of legislative process
− House Ways and Means Committee reports and Senate Finance Committee reports
− Explain elements of proposed changes to IRC and reasons for each proposal
− Used by tax researchers to clarify meaning of statute or intent of Congress
Conference committee reports (“Blue Books”) from Joint Committee on Taxation (lower level of authority than a committee report—still used to show legislative intent)
Internal Revenue Code—Organization
Title 26 of the United States Code (codification of all federal laws)
Subtitles
Chapters
Subchapters
Parts
Sections
Subsections
Subtitles of Internal Revenue Code, as
Amended
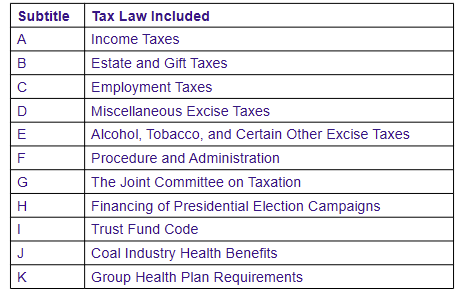
Key Chapters of the IRC
