GMK and MLO DAY 6 NOTES
 Call Kai
 Learn
 Practice Test
 Spaced Repetition
 Match
 Flashcards
 Knowt Play
1/94

There's no tags or description
Looks like no tags are added yet.
95 Terms
Conventional loan are which two?
Conforming and non-conforming
Non conventional loans are?
VA, FHS, and USDA (Ag)
Conforming loans are
conform to FHFA Bought by fannie and freddie
Non conforming loans are
not able to be sold to freddie and fannie
Mortgage investing agencies
Fannie Mae, Freddie Mac, and Ginnie Mae
* Created by congress
make rules
buy mortgages from lenders
provide liquidity stability to mortgage market
considered secondary markets
government sponsored Freddie and Fannie
government OWNED Ginnie
Which Mortgage investing agency is OWNED by the government
Ginnie Mae
Conventional Conforming Loan that conform to Fannie and freddie guidelines are what?
Loan amounts
down payment
PMI
LTV
Income qualifications
Credit Qualifications
Seller financing and seller concessions
Hazard Insurance
Seller Financing aka Seller carry-back
A loan from seller that is recorded in second position and must be paid back
Seller concessions
paid by seller and used to cover closing costs, and they do not have to be paid backM
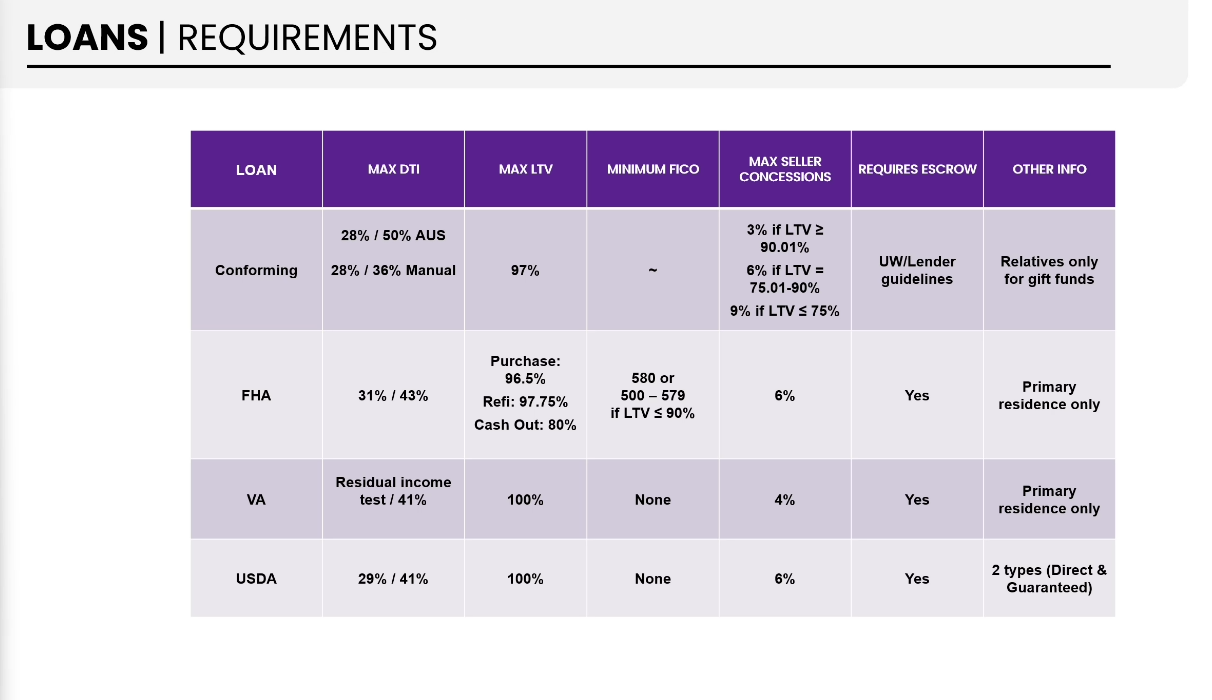
Max seller concessions ?
3% LTV is greater or equal to 90.01
6% LTV is great or equal to 75.01-90%
9% if LTV is less than or equal to 75%
LLPA Loan Level pricing adjustments
charges due to increased risk associated with loans. LLPA fees are passed on to consumers in the form of higher ratesWh
WHat influences the LLPA? There are 5*
Loan Term
Loan balance
property type
transaction type
borrower credit score
Credit Overlays
Higher standards lenders set which extend, or enhance FNMA/FHLMC requirements
Fannie Mae uses automated underwriting systems known as ?
Desktop underwriter
Jumbo Loan is ?
A Conventional Non conforming loan
Exceeds loan limits established by FNMA/FHLMC
ALT-A loan is ?
Conventional non conforming loan
ALT-A
Borrowers without same degree of risk as subprime, but do not meet underwriting requirements for conforming loans
Subprime
A conventional Non conforming loans
Higher Interest loans made to borrowers with flawed credit or other qualification issues
Niche Loans
A conventional non conforming loan
Loans for borrowers with unique circumstances or needs
Option ARMs or non traditional ARMS
A conventional non conforming loan
Refers to flexible payment options such as
minimum payments
interest only payments
full amortizing payments
2nd liens
conventional but dont conform to fannie and freddie
FHA does what to loans
INSURES LOANS
Purpose of FHA
Ensures borrowers who cannot qualify for conventional loans have opportunities to o
Features Characteristics of FHA LOANS (5)
Low down payment requirements
Fee limits on closing cost
More lenient underwriting requirements
streamline option
assumable
An assumption ?
Allows a buyer or someone else to take over a mortgage and streamlines it.
FHA mortgage insurance
UFMIP
UFMIP?
Upfront mortgage insurance premiums (UFMIP)
Paid in full time at time of closing
1.75% of the loan amount
Mortgage insurance premiums (MIP)
Amount based on LTV and the term of the loan
Paid monthly for:
11 years if LTV is less than or equal to 90% at origination
life of the loan if ltv > 90% at origination
VA loan does what to the loan?
GUARANTEES IT
PURPOSE OF VA LOANS?
Can be utalized by:
Members of military and spouses with dead service members
VA loans featured characteristics (7)
100% financing
limited closing cost
VA payment assistance
more lenient underwriting requirements
streamline option - IRRRL
Assumable
VA assistance available if borrower can no longer make mortgage payment
COE (Certificate of eligibility) relates to what?
VA loans
COE (Certificate of Eligibility)
Used to show entitlement amount - amount guaranteed for each eligible borrower
What is entitlement amount based on?
YEARS of service
discharge status
branch of service
Guaranty is based what?
loan amount and entitlement amount
ie 25% oif loan with full entitlement on greater than 144,000
VA funding fees:
do not require mortgage insurance but funding fees are required in most circumstances
funding fee is ?
% of a loan amount

funding fees as of 1/1/2026
Veterans are exempt from funding fee if:
Service-connected disability (10% or more disabled)
Spouse of veteran who died during service or service connected cause
Active duty purple heart recipients
Residual Income
income left over after paying estimated obligations related to all household members - in addition to DTI requirements
certificate of reasonable value
VA version of appraisal
USDA LOANS or RHS or section 502 apply to ?
rural areas
modest property
fixed rate
100% financing
RHS direct loans (4)
funded directly by U.S government
no gurantee fee
offered in 33 or 38 year term
max income is usda low-income limits for area
RHS Guranteed loans? (5)
funded by private lenders
guranteed by RHS if loan goes into foreclosure
30 year term max
max income 115% of median income for area
guarantee fee
1% up front
.35% of remaining loan amount
RHS guarantee fee?
1% up front
.35 of remaining loan amount
UFMIP is 1 time at closing at what percentage?
1.75%
Guidances are ?
An immediate response to the subprime mortgage crisis response
Problem that guidances fix?
laws take time to pass guidances offer immediate actionso
Guidance #1
Interagency guidance on nontraditional mortgage product risks (2006)
What was the purpose of guidance #1?
address risky features of nontraditional loans. helped shape ability to repay and qualified mortgage rules
wh
who was the target audience of guidance #1
depository institutions and later adapted for state licenses lenders
key concerns of guidance #1 (3)
Deferred principle
negative amortization
borrower misunderstanding of terms
fixed rate mortgage characteristics (4)
interest rate stays fixed during life of loan
P&I portion of monthly payment will stay the same for life of loan
Monthly Payment may change due to escrow items
regional property taxes go up → payment goes up not interest rate
30 year is the most common8*** 25, 15, and 10 year (rare)
What determines current market rates
forclosure rates
loan fraud
fed reserve
Prepayment penalties?
Allows lender to recoup some unearned interest if borrower prepays loan balance before end of term
Prepayment penalties are ?
qualified mortgages that have a fixed rate for full term of the loan
Prepayment penalties (3)
2% of outstanding loan balance if prepayment is made within the first 2 years
1% of outstanding loan balance if prepayment is made within 3rd year
No prepayment penalty if prepaid 3 years or more after consumation
ARMs
Adjustable-rate mortgages
Hybrid ARMS?
Interest rate that may change one or more times during life of loan
Common hybrid terms (3)
3 year (3/1), 5 year (5-1), 7 year(7-1), 10 year(10-1)
Features of hybrid arms
Fixed for the initial period
Adjustment frequency determines how often the rate changes
3/1, 7/1, 10/6
3 years will be fixed, will adjust every 1 year
/ 7 years will be fixed, will adjust every 1 year
/ 10 years will be fixed, will adjust every 6* month
ARMS have ?
CAPS
What is an arm cap?
Expresses initial rate cap/periodic rate cap/lifetime rate cap
ex: 2/2/5
5/2/5
5% initial rate cap
2% periodic rate cap
5% lifetime rate cap
initial rate caps are to prevent?
RATE SHOCKS
EXAMPLE 1 ARMs
3/1 ARM?
Rate 3%
CAP 1/2/6
fixed for 3 three years/ 1 (can adjust every 1 year)
3% start rate
1% for initial rate, 2% for periodic rate
index
piece of arm that adjusts

Indexes (3)
San Francisco 11th District Cost of Funds Index (COFI)
Secured overnight financing rate
treasury bill index
Margin
Lender profit (remains constant for life of loan)
Fully indexed rate
index + margin
Second Mortgages purpose?
Also known as junior mortgage or subordinate loan - ranks in priority below first mortgage
priority of liens is significant if foreclosure occurs because liens are usually paid in order in which recorded
2nd mortgages apply to?
HEL (home equity loan)
HELOC (home equity line of credit)
Piggybackloan
balloon mortgages purpose
Loan does not fully amortize when matured
large balloon payment due at maturity
typically loan matures between 5 to 7 years
Conditional refinance provision
conditional refinance provision allows borrower to request modification at maturity
conditional refinance provision example
5/25
7/23
no conditional refinance provision
5/30
7/30
180/360 (months)
reverse mortgages purpose
Allows elderly homeowners to use equity in their home to help with living expenses or home improvements
reverse mortgages must be repayed (5)
Stop paying property taxes and insurance
house in disrepair
add any new owners to the title
rent out the home
declare bankruptcy
REQUIREMENTS FOR A REVERSE MORTGAGE
must be 62+ years old (definition of elderly under ECOA)
must live in home: primary residence
no others loans or liens on home
loan becomes due if any of the items above change, home is sold, or last surviving homeowner dies
interest is charged on outstanding debt and added to debt
debt increase with each advancement of credit
requires counseling
single purpose reverse mortgage?
low-cost loans offered to low-income borrowers by state and local agencies, or non profit organizations
can be only used for purpose specified by lender
Home equity conversion mortgages (HECM) (4)
Regulated by hud
borrower can receive fixed monthly payments, a line of credit, or combination
Available to homeowners who owe little or no money on their home
HUD requires certificate of completion of counseling as part of the application process must be completed prior to application
properietary mortgages:
private loans
more expensive but allow homeowners to borrow more than HECM
Purpose of HELOCS?
Open-end loan that allows repeated transactions or withdrawls against loan
helocs are obtained using equity in property
heloc is often a second mortgage
Construction to permanent
Only one closing, reducing fees consumer would pay
only pays interest on outstanding loan balance during construction
lender converts construction loan into permanent mortgage
Stand alone construction loan
two application processes and two closings
benefits consumer if they are putting less than 20%
bridge financing
short term loans taken out by consumers waiting for long term financing
may be as a construction loan (down payment for land/new construction)
loan is secured by existing home that borrower is trying to sell
interest only loan purpose?
pay only interest for specified amount of time
when interest only period ends, borrowers must begin making larger payments of principal interest
URLA (UNIFORM RESIDENTIAL LOAN APPLICATION)
Takes place in person, by phone or online
LO is responsible for signing and verifying accuracy
False statement can lead to 5 year jail term
Section 1-8 of the URLA is borrowing specific information

URLA
the mortgage application (1003) is the foundation of the loan. Everything that follows: pricing underwriting, disclosures, approval, and closing is based on the information collected at application
ERROR or assumptions at this state can cause
Re-disclosures
delays
rate or cost changes
loss of borrower trust
compliance issues
URLA info
Six Core categories of information
1. borrower information
full legal name
social security number
date of birth
current and prior addresses
marital status (when applicable)
income and employment
assests
liabilities
property information
loan details
Loan type
purpose
rate type
estimated loan amount
this drives eligibility disclosures and time requirements
What are borrower declerations?
legal statements the borrower makes under penalty of perjury