Ch 1: Accounting for Intercorporate Investments
 Call Kai
 Learn
 Practice Test
 Spaced Repetition
 Match
 Flashcards
 Knowt Play
1/20

There's no tags or description
Looks like no tags are added yet.
Name | Mastery | Learn | Test | Matching | Spaced | Call with Kai | Chat |
|---|
No analytics yet
Send a link to your students to track their progress
21 Terms
Three Approaches to the Accounting for Equity Investments under GAAP (Degree of Influence)
The degree of influence/control that the investor comp can exert over the investee comp’s operating activities determies the method that the investor must use to report its equity investment in the fin st
Insignificant Influence (Fair Value Method): the investment account is reported on the BS at its current fair value at each statement date. Dividends received are recognized as income, and increases in the FV of the investment are reported in current income. Method is req if the investment is passive (the investor cannot exert signif influence over or control the investee company)
Significant Influence (Equity Method): the investment account is not reported at fair value, but at an amt that is equal to the proportion of the stockholders’ equity of the investee company that the investor owns (and typically also includes acquisition-date fair value adjustments)
Control (consideration): after the investor comp is deemed to control the investee, the fin st of the two companies must be consolidated (combined)
1. Insignificant Influence — Fair Value Method
Usually less than 20%
Girl terms: You own a piece of the company, but you don't have a say in how it runs.
Balance sheet: Report the investment at fair value.
Dividends: Record as dividend income.
Changes in fair value: Unrealized gains and losses generally affect current net income.
2. Significant Influence — Equity Method
Usually 20%–50%
Girl terms: You can't control the company, but you have a voice in its decisions.
Balance sheet: The investment balance changes based on your share of the investee's earnings, dividends, and other required adjustments.
Net income: Your share of the investee's earnings increases your investment.
Dividends: Your share of dividends decreases your investment.
Fair value changes: Ordinary market-price changes do not directly adjust the investment balance.
3. Control — Consolidation
Often more than 50%
Girl terms: You control the other company, so you combine the two companies' financial statements.
Financial statements: Combine the parent and subsidiary's accounts line by line.
Intercompany transactions: Eliminate transactions between the two companies.
Less than 100% ownership: If applicable, recognize a noncontrolling interest for the portion owned by outside shareholders.

When should the equity method be used?
GAAP says: used to account for Equity Investments and investments in corporate joint ventures when the investor has the ability to exercise influence over operating and financial policies of an investee
an investment of 20% or more of the voting stock of an investee shall lead to a presumption that in the absence of predominant evidence to the contrary an investor has the ability to exercise sig influ over an investee But sometimes it doesn’t result in sig inf
The ability to exercise signif influ may be indicated in a number of ways:
Investor representation on the BOD of the investee
Investor participation in policy making process of the investee
the extent of ownership of investee voting shares by the investor in relation to the concentration of other shareholdings
material intercompany transactions btwn the investor and the investee
interchange of managerial personnel btwn the investor and the investee
technological dependency of the investee on the investor
any of these can be met to provide sufficient evidence to conclude that the ability to exercise sig influ is present, even if the investor owns less than 20% of the outstanding voting stock of the investee
The investor might not have signif influ even though it owns more than 20% of the outstanding voting stock of the investee. Ex of when an investor may be unable to exercise sig influ over the operating and financial policies of an investee:
The investee challenges the investor’s ability to exercise signif influ, such as by litigation or complaints to governmental regulatory authorities
the investor and investee sign an agreement under which the investor surrenders signif rights as a shareholder
majority ownership of the investee is concentrated among a small group of shareholders who operate the investee without regard to the views of an investor
the investor needs/wants more financial info to apply the equity method than is available to the investee’s other shareholders, tries to obtain that info and fails
The investor tries and fails to obtain representation on the investees BOD
when any of these are present, the investor company may be justified in not employing the equity method in accounting for the investment despite ownership of more than 20% of the outstanding voting stock of the investee
the investor must account for the Equity Investment using the equity method when it can exert influence over investee company
when the investor obtains control over the investee, it must consolidate the fin st of both companies when reporting to external parties such as shareholders or the SEC
for preconsolidation internal reporting, the investor can use the equity method to account for its equity investment in the investee company

Accounting Procedures for an Investment Using the Equity Method: Accounting for the Purchase of an Equity Investment (Ex problem)
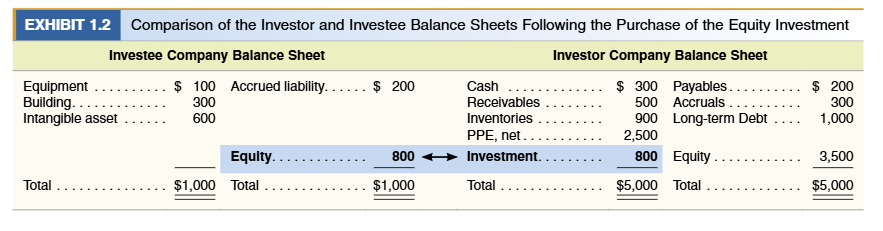
Equity Investment acct represents the proportion of the owners equity of the acquired company that is owned by the acquiring company
assume fair values of the acquired comp’s net assets equal their reported amnts (BV) on the BS
assume the investor comp purchases all of the investees outstanding CS from its shareholder for total consideration worth $800. Investor funds the purchase price of $800 thru a cash pmt of $300 and issuance of 100 shares of $1 value CS with fair value of $500.
Acquiring comp records the equity investment:
DR Equity Investment 800
CR Cash 300
CR Common Stock (100 @ $1) 100
CR Additional paid in capital 400
Investees business is now represented on the investors BS as an asset (equity investment) that is equal to the Stockholders equity of the acquired comp on the date of purchase
bc the investor owns 100% of the investee comp and the air value of the business is equal to its stockholders equity, the investor’s equity investment account in the amnt of $800 is equal to the proportion of the investee’s stockholder equity that it owns (100% of 800 = $800
provided that the acquisition is made at book value, the balance reported in the equity investment account will always be equal to the proportion of the investee company equity that we own; as the investee’s SE inc or dec, the equity investment on the investor’s BS does too
Accounting for the Equity Investment Subsequent to its Purchase: Accounting for Changes in the Reported Amount of the Equity Investment Subsequent to its Purchase
Now assume the investee earns a profit of $300 and pays a dividend of $100 to the investor. The investee’s SE has then increased by 200 (300 profit-100 dividend) to 1000
to maintain the equivalence btwn the equity investment on the investors BS and the investees SE, the equity investment much also inc by 200 to a balance of 1000
recording two changes to this account
a 300 inc to recognize the investors share of the increase in the investee’s SE resulting form the profit of 300
DR Equity Investment CR Equity Income (300)
a 100 dec to recognize the investors share of the dec in the investee’s SE, resulting from the payment of dividends (reduction of RE) of 100
DR Cash CR Equity Investment (100)
Equity Investment Account: Beg DR 800 + Equity Income DR 300 - Dividends Received CR 100= 1000 DR Ending Bal
The equity method results in an equity investment account that inc and dec with the SE of the investee company
Accounting for the Equity Investment Subsequent to its Purchase: Accounting for Changes in the Reported Amount of the Equity Investment Subsequent to its Purchase:
Three Observations relating to the Investor’s Accounting for its Equity under the Equity Method
the investor does not report the receipt of dividends as income like it does under the fair value method for passive investments. Div are treated as a return of investment (not return on) and the Equity Investment account is reduced accordingly. Instead the investor reports income from the investment equal to the percentage of the investee’s NI that it owns. In this case, the investor owns 100% of the investee, so it reports 100% of the investee’s NT as equity income in its own IS
The investor only reports Equity Income commencing with the date on which it purchases the Equity investment. Ex, If the investor purchases the equity investment on March 1, it can only include in its income statement the percentage of the investee’s profit that it earns subsequent to march 1
under the equity method, the investor does not adjust the equity investment account for changes in fair value, as is the case with fair value method of accounting for investments. There may be substantial unrealized gains that are not reported on the BS, and the investor does not report these gains in its IS. There may be unrealized gains are recognized in full when the investment is sold
Accounting for the Equity Investment Subsequent to its Purchase: Accounting for the sale of the Equity Investment
Account for the sale of a non controlling equity investment in the same way thats for the sale of any asset we own
record the receipt of cash (or other assets (n/r))
Remove the equity investment from the BS
Recognize the difference btwn cash received and the reported amnt (bv) of the equity investment as a gain or loss on the sale
The invesstor sells its equity investment (reported at 1000) for cash proceeds of 1250
DR Cash 1250 CR 1000 CR 250
The investor recognizes a gain on the sale of equity investment bc the proceeds (1250) exceed the reported the reported amnt (bv) of the investment (1000) on its bs. if it sold the equity investment for 700 there would be a loss:
DR Cash 700 DR Loss on sale 300 CR Equity Investment 1000
Summary of Equity Method

Accounting for Equity Investments When the Purchase Price Exceeds Book Value
Acquisitions are rarely made at book value. Fin St are prepared using a mixture of measurement bases (historical costing) and do not reflect fair values. And there may be unrecorded assets that are reported on the BS of the investee comp plus some additional previously unrecorded assets
EX. Acquiring comp purchases all of stock of investee for 1100 with cash pmt of 600 and issuance of 100 shares of $1 par value CS w a fair value of $500 ($5 per share). Investor is willing to pay the increased price bc the building, reported on the investee’s BS at a net book value of 600 has a current fair value of 900
1,100= 800 BV of SE of the investee comp + 300 Building value not reported on investee comp’s BS
Depreciation
The investee will continue to depr the 600 BV of the building it reports on its BS
The investor will depr the additional 300 building asset that it purchased in the acquisition
Total Depr Exp: 45= 30 (600/20) investees IS +15 (300/20) Investors IS
Investor entry: DR Equity Investment 1100 CR Cash 600 CR CS 100 CR APIC 400
investee earns profit of 300 and pays div of 100. So investee’s SE inc by 200 to a balance of 1000. The additional investment is on the investors BS not the investor
Investor entry: DR Equity Investment 300 Equity Income 300 (equity income) DR Cash 100 CR Equity Investment 100 (dividends) DR Equity Income 15 CR Equity Investment 15 ( depr of the building asset)
Equity Investment: DR Beg Bal 1100 + Equity Income 300 - Div received 100 - Depr of incremental building value 15 = DR End bal 1285
The balance reported in the Equity Investment account will always be equal to the proportion of the investee comp’s SE that the investor owns plus the unamortized amnt of the incremental FV of the net assets acquired

Accounting for the Effects on Equity Investments of Intercompany Sales of Inventory
Investee sells goods that cost 100 to the investor for 130. When the intercompany (btwn investor and investee) sale occurs, the investee and investor comps make these transactions
Investee: DR AR CR Sales 130 (sale of product on acct) DR COGS CR Inventories 100 (cost of goods sold)
Investor: DR Inventories CR A/P 130 (purchase of inventory)
The investee records a gross profit of 30 (130-100) and investor records the inventory on its books at the purchase price of 130
the 30 gross profit has inc the investee’s NI by 30 and that inc in profit results in a 30 inc in equity income that is reported by the investor (investor owns 100% of investee comp and reports 100% of investee’s profit as equity income)
Both the investor and investee reported the same 30 of profit
GAAP does not permit the recognition of profit on appreciated assets until those assets are sold (profit is realized) . GAAP views the two comp as one reporting group
the gross profit on the intercompany sale must be deferred and cannot be recognized until those inventories are sold outside the related comps
Deferral of gross profit on inv sale in the period of sale: DR Equity income CR Equity Investment 30
Recognition of gross profit on inventory sale in the following period: DR Equity Investment 30 CR Equity Income 30
If only you deferred 40% of the gross profit on inventory sale in the period of sale: DR Equity Income 12 CR Equity Investment 12
Equity Method Accounting when Less than 100% of the investee is owned
instead of purchasing 100% of the comp for $800, the investor purchases a 30% interest in the investee for $240 (800*30%), in cash and has signif influ over the investee comp
also the investee earns a profit of $300 and pays a total div of $100 with $30 (30%) paid to the investor and the remaining paid to other shareholders. The investee’s SE at EOY inc by $200 to a bal of $1000
Investor JE
DR Equity Investment CR Cash 240 (purch of equity investment)
DR Equity Investment CR Equity Income 90 9record equity income (30% of 300)
DR Cash CR Equity Investment (to record receipt of div of $30)
Equity Investment Acct: Beg Bal: 240 + Equity income 90 - Div recieved 30 = End Bal 300
investee records it as 1000 at eoy and investor reports equity investment as 300 (30%*1000 at BV)
Deferral of unrealized profit on intercomp sales: if the asset being sold is 1) an output of the comps operations, 2) the transaction is considered arms length, and 3) the investor has sig influ over the investee; then the investor only defers the proportion of GP that it owns
investor will defer $9 (30% of $30) DR Equity income DR Equity Investment
Relation btwn investment bookkeeping and consolidation
both the investor and the investee comp are separate legal entities, each w their own fin st. We need to account for the operations of both comps separately
The investor will continue to report the investee on the investor’s pre-consolidation BS using the equity investment account. This is true whether the investor has signif influ over or controls the investee comp
The investor accounts for its equity investment using the equity method from the time it acquires sinif influ and for internal reporting purposes can continue to account for the investee using the equity method even if it gains control. When the investor gains control over the investee, the investor must issue consolidated fin st for external fin reporting purposes
Discontinuation of the Equity Method
When the investor has signif influ over an investee, it is possible that the reported amnt of the equity investment might be reduced to zero on the investors BS
This occur bc of any of these:
Investee comp losses
pmt of div by the investee to the investor in excess of the amnt of cumulative equity income reported by the investor
write down of the equity investment by the investor as a result of its determination that the fair value of the investment has other than temporarily declined
When an investor has significant influence over an investee, and when the reported amnt of the equity investment is reduced to zero, the investor ceases to use the equity method to account for its equity investment
the investment is instead carried on the investor’s BS at a zero amnt until the investee earns sufficient profit such that the unrealized loss is eliminated
Ex. investor owns 30% of the investee and the equity investment was acquired at book value
the reported amnt of the equity investment equals 30% of the SE of the investee
as the investee reports losses, the investor reduces the reported amnt of its equity investment until the SE of the investee comp reaches zero
any dividend received from the investee are recognized as income by the investor and the investor ceases to recognize equity losses until the investee resumes profitability and the deficit SE has been eliminated
investor resumes using equity method to account for equity investment
Accounting for a Change to and from the Equity Method
the level of influence can change over time:
investor purch additional shares of the investee
investee purch its own shares from other parties
investor gaining representation on the BOD of the investee comp
Change from Insignificant Influence (Fair Value or Cost-Based Methods) to Significant Influence (Equity Method)
Investor Comp has insignif influ
If the investee’s CS held by the investor has a readily determinable FV, then the investment account is recorded at fair value with all holding gains and losses and all dividends received by the investor run thru earnings
the equity investment account will be measured at FV, the equity investment account will be measured at FV thru the most recent BS date
on the date signif influ in the investee is obtained, the process for converting from the FV method to the equity is to
adjust the equity investment account to its FV on the date that signif influ is obtained
increase the equity investment account for the cost of the incremental additional investment that caused the investment to move from being a passive investment to a significant influ investment
if the invesee’s CS held by the investor does not have a readily determinable FV, then the investment account is recorded using the cost based method with only dividends received thru earnings
equity investment will be measured at cost thru the date of the transaction that triggered the investor achieving signif influ
determine whether the transaction to obtain signif influ is an observable price change in orderly transactions for the idintical or a similar investment of the same issuer
Change from the Equity Method to the Fair Value or Cost-Based Methods
when the level of influ over an equity investee changes to a level at which the investor can no longer exert signif influ over the investee comp’s operating activities, the accounting will transaction from the equity method to FV or CB methods
Fair-Value-Based Measurement Approach
at the moment signif influ is lost, the balance of the Equity Investment account will carry forward, even if the fair value measurement approach is appropriate
transition from the equity method to the fair value approach:
adjusting the investment to the appropriate carrying value and computing the gain or loss from the ownership-change transaction itself
after the post-transaction carrying value is determined, marking the retained investment to fair value
Both of these happen instantaneously, but will result in two types of gains and or losses

Cost-Based Alternative Measurement Approach
allowed for investments in equity securities that do not have a readily determinable fair value
when we transition away from the equity method for noncontrolling equity investments, the investor needs to determine whether the transaction causing the discontinuation of the equity method constitutes an observable price change in orderly transactions for the identical or a similar investment of the same issuer
if it does, the remaining investment will be marked to fair value
if it does not, the first entry in the fair value approach example will be recorded but not the second
Required Disclosures for Equity Method Investments
Under FASB ASC 323-10-50, companies using the equity method must disclose the following in their financial notes:
Investee & Policy Details: Investee names, ownership percentages, investor accounting policies, and any difference between carrying value and underlying net asset equity (along with how that difference is treated).
Market Value: Aggregate market value based on quoted market prices, if available (does not apply to subsidiaries).
Summarized Financial Data: Summarized asset, liability, and operating result data (individually or grouped) if joint ventures or equity method investments are material relative to the investor's overall position.
Dilutive/Contingent Securities: The potential impact of convertible securities, options, warrants, or contingent issuances on the investor’s share of earnings or losses.
Criticism of the Equity Method
Key Conceptual Weaknesses
Book Value vs. Fair Value: Increases in fair value are not recognized until the investment is sold. However, if fair value experiences a permanent decline, it is treated as an impairment and written down.
Accrual Income vs. Actual Cash: The investor recognizes its share of investee net income as revenue, but actual cash is only received if the investee pays dividends.
"One-Line Consolidation" Risks
Hiding Debt & Underlying Risks: Presenting investments as a single net balance hides underlying financial leverage. For instance, a company can report a positive investment balance even if the underlying joint ventures have massive debt and negative net equity.
Liability Masking: Joint venture structures allow parent companies to isolate high-risk liabilities (such as bankruptcy or major litigation) off their primary balance sheet, limiting direct exposure.