Ch. 16. Income Tax Expense, Deferred Tax Accounts MCQ
 Call Kai
 Learn
 Practice Test
 Spaced Repetition
 Match
 Flashcards
 Knowt Play
1/10

There's no tags or description
Looks like no tags are added yet.
11 Terms
Which of the following differences between financial accounting and tax accounting ordinarily creates a deferred tax liability?
A. Depreciation early in the life of an asset.
B. Unrealized losses from recording investments at fair value.
C. Rent collected in advance.
D. None of these answer choices are correct.
A. Depreciation early in the life of an asset.
Which of the following differences between financial accounting and tax accounting ordinarily creates a deferred tax asset?
A. Depreciation early in the life of an asset.
B. Unrealized gain from recording investments at fair value.
C. Subscriptions collected in advance.
D. None of these answer choices are correct.
C. Subscriptions collected in advance.
For its first year of operations, Tringali Corporation's reconciliation of pretax accounting income to taxable income is as follows:
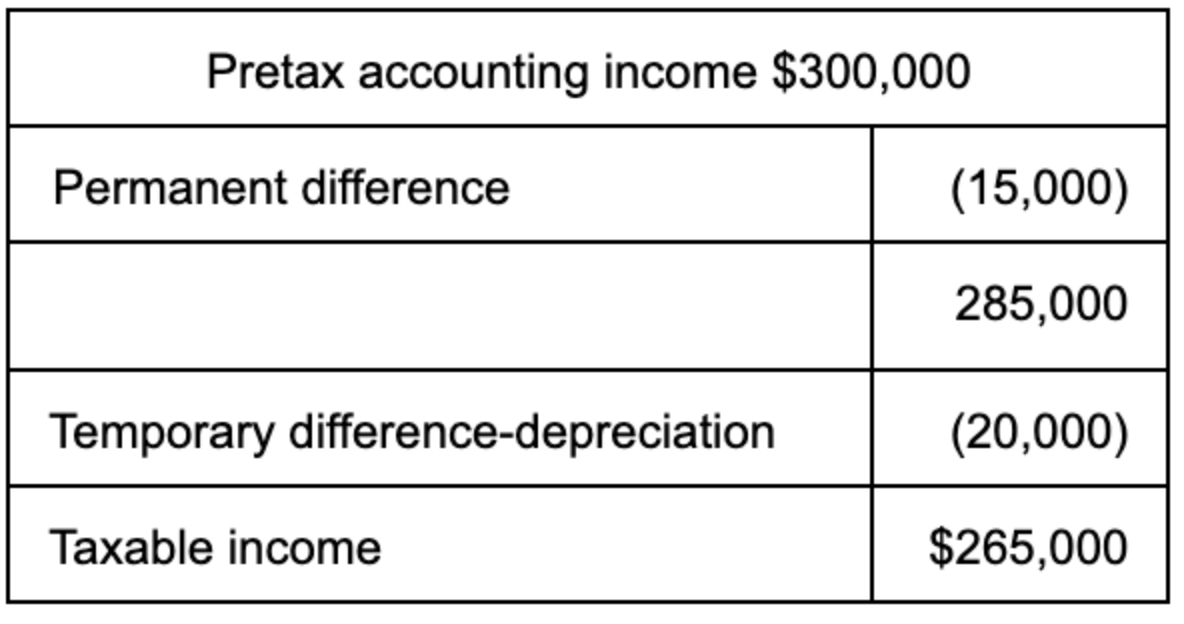
Tringali's tax rate is 40%. Assume that no estimated taxes have been paid.
What should Tringali report as income tax payable for its first year of operations?
A. $120,000.
B. $114,000.
C. $106,000.
D. $8,000
C. $106,000.
$265,000 × 40% = $106,000
For its first year of operations, Tringali Corporation's reconciliation of pretax accounting income to taxable income is as follows:
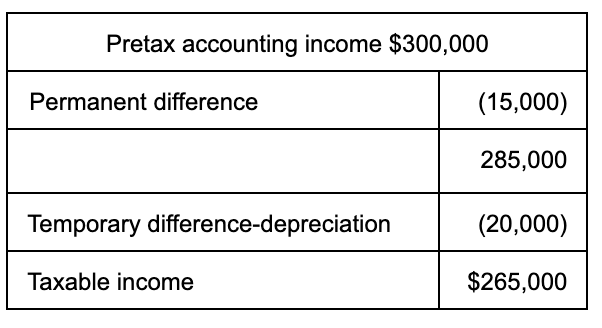
Tringali's tax rate is 40%. Assume that no estimated taxes have been paid.
What should Tringali report as its income tax expense for its first year of operations?
A. $120,000.
B. $114,000.
C. $106,000.
D. $8,000.
B. $114,000.
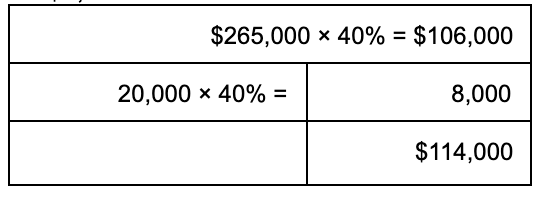
The following information relates to Franklin Freightways for its first year of operations (data in millions of dollars):
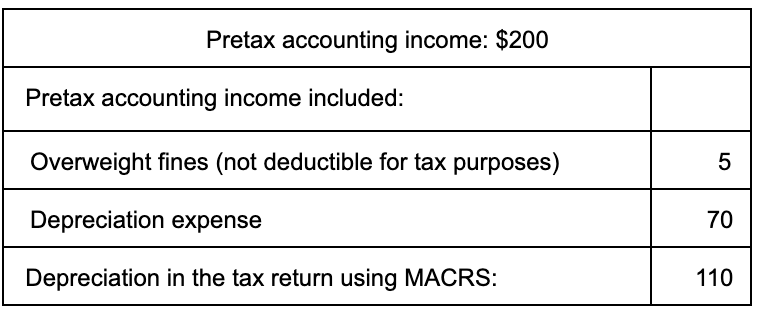
The applicable tax rate is 40%. There are no other temporary or permanent differences. Franklin Freightways experienced ($ in millions) a current:
A. Tax liability of $66.
B. Tax liability of $36.
C. Tax liability of $70.6.
D. Tax benefit of $10 due to the NOL.
A. Tax liability of $66.
($200 + 5 - $40) × 40% = $66
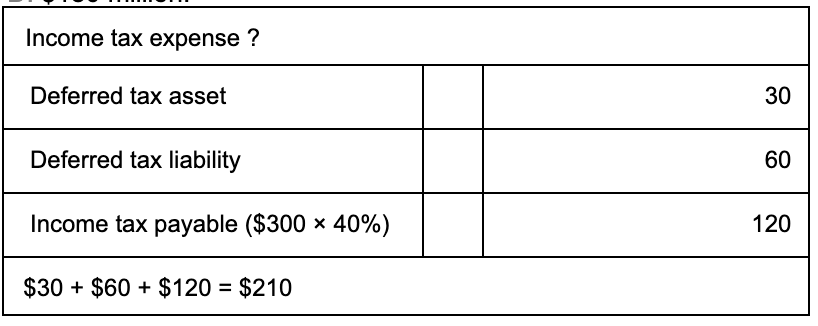
Alamo Inc. had $300 million in taxable income for the current year. Alamo also had a decrease in deferred tax assets of $30 million and an increase in deferred tax liabilities of $60 million. The company is subject to a tax rate of 40%. The total income tax expense for the year was:
A. $390 million.
B. $210 million.
C. $150 million.
D. $180 million.
B. $210 million.
Of the following temporary differences, which one ordinarily creates a deferred tax asset?
A. Completed-contract method for long-term construction contracts for tax reporting.
B. Installment sales for tax reporting.
C. Accrued warranty expense.
D. Accelerated depreciation for tax reporting.
C. Accrued warranty expense.
The valuation allowance account that is used in conjunction with deferred taxes relates:
A. Only to deferred tax liabilities.
B. To both deferred tax assets and liabilities.
C. Only to deferred tax assets.
D. Only to income taxes receivable due to net operating loss carrybacks.
C. Only to deferred tax assets.
In 2015, HD had reported a deferred tax asset of $90 million with no valuation allowance. At December 31, 2016, the account balances of HD Services showed a deferred tax asset of $120 million before assessing the need for a valuation allowance and income taxes payable of $80 million. HD determined that it was more likely than not that 30% of the deferred tax asset ultimately would not be realized. HD made no estimated tax payments during 2016. What amount should HD report as income tax expense in its 2016 income statement?
A. $50 million.
B. $80 million.
C. $86 million.
D. $116 million.
C. $86 million.
The tax expense of $80 million is adjusted for two items. (1) It is reduced by the $30 million increase in the deferred tax asset, and (2) it is increased by the $36 million increase in the valuation allowance (30% × $120 million).
Which of the following causes a permanent difference between taxable income and pretax accounting income?
A. The installment method used for sales of property.
B. MACRS depreciation method used for equipment.
C. Interest income on municipal bonds.
D. Percentage-of-completion method for long-term construction contracts.
C. Interest income on municipal bonds.
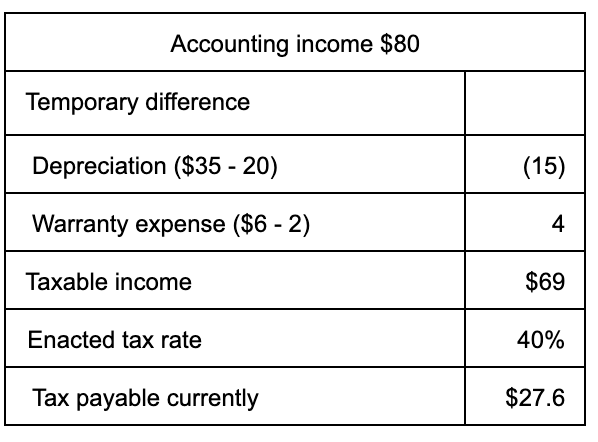
For the current year ($ in millions), Centipede Corp. had $80 in pretax accounting income. This included warranty expense of $6 and $20 in depreciation expense. Two million of warranty costs were incurred, and MACRS depreciation amounted to $35. In the absence of other temporary or permanent differences, what was Centipede's income tax payable currently, assuming a tax rate of 40%?
A. 19.6 million.
B. 25.2 million.
C. 27.6 million.
D. 29.2 million.
C. 27.6 million.