TAX week 4
 Call Kai
 Learn
 Practice Test
 Spaced Repetition
 Match
 Flashcards
 Knowt Play
1/17

Earn XP
Description and Tags
Week 4 – Income Tax calculations (including gift aid), admin & National Insurance Contributions (NIC)
18 Terms
Gift Aid Introduction

example if you pay to charity

Gift Aid – Claiming Higher /Additional Rate Relief

Gift Aid – Lecture Example 1 Question
Yasar’s only source of income in the 2025/26 tax year, is £60,000 salary from employment.
On 1 January 2026, Yasar paid £1,600 to a local charity, on which gift aid was claimed.
Required:
Calculate Yasar’s Income Tax Liability for 2025/26
Gift Aid Lecture Example 1- SOLUTION

Self-Assessment Tax Return Deadline

Tax Payment Deadlines
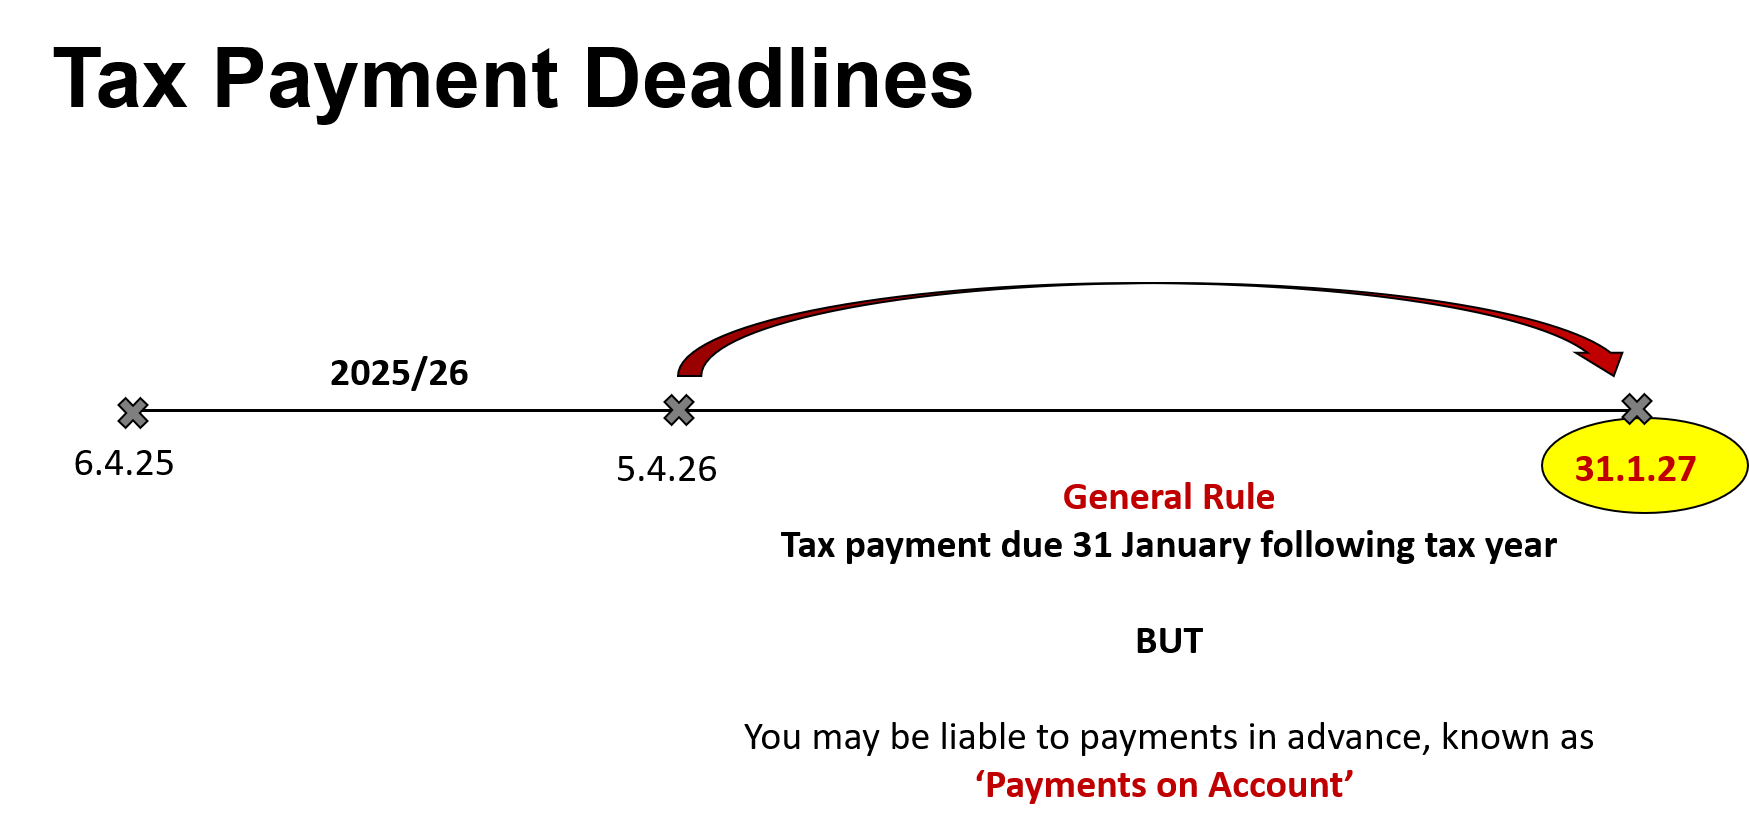
Payments on Account (First year)

Payments on Account (First year) part two

Does everyone make POAs? (payments on account)
No – you do not make POAs if:
•Tax Payable < £1,000, or
•Tax deducted at source > 80% of Tax Liability
•
So e.g. if you only have a small amount of tax due on your savings income – you just pay tax once a year on 31 January.
Likewise, if you pay lots (>80%) of tax via PAYE, then the idea is you pay enough tax upfront so don’t need to pay in advance!
What if I know next year’s tax bill is lower than this year’s?
POAs assume your tax bill next year will be the same as this year. Obviously, this may not be the case.
If you have reasonable grounds to expect your tax bill to be lower next year, you can claim to reduce your POAs to an appropriate amount. But you will suffer interest if you get it wrong!
National Insurance Contributions (NICs)

Class 1 NIC

Class 1A NIC

National Insurance - Lecture Example 2
Maria is employed by BETA plc. She earns an annual salary of £52,000 and has a taxable company car benefit of £12,300 per annum.
Calculate the Class 1 Primary (Maria pays), Class 1 Secondary (BETA plc pays) and Class 1A (BETA plc pays) National Insurance contributions for 2025/26.
National Insurance - Lecture Example 2 - Solution Part 1

National Insurance - Lecture Example 2 - Solution Part 2
3.Calculate Class 1A NIC (employer)
●
Class 1A BIKs (Company car Benefit) 12,300
Class 1A = 12,300 @ 15% = £1,845