CPA REG
 Call Kai
 Learn
 Practice Test
 Spaced Repetition
 Match
 Flashcards
 Knowt Play
1/248

There's no tags or description
Looks like no tags are added yet.
249 Terms
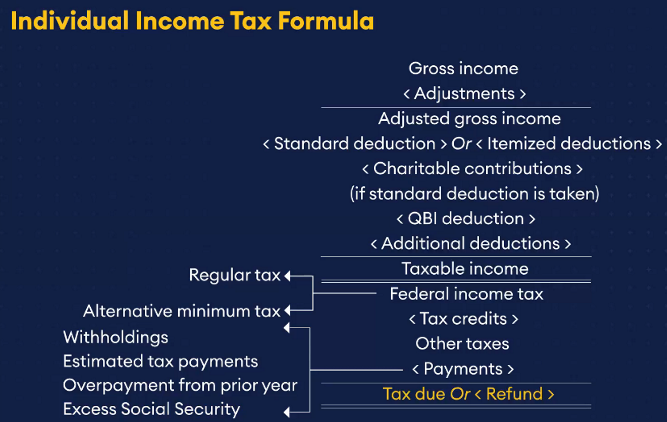
What is the individual tax formula?
What are the itemized deductions?
MTICCM
Medical
Taxes (state + local)
Interest expense (home + investment)
Charitable contributions
Casualty/theft loss attributable to federal or state declared disaster
Miscellaneous - educator
Who must file?
A taxpayer if their income is greater than:
- The standard deduction PLUS
the additional stadard deduction for taxpayers 65 or older
When to file? Extension? What does this mean for payments?
April 15
15th day of the 4th month after the taxable year close
Auto 6 month extension to October 15
NOT an extension for payment of taxes
What are the filing statuses? Criteria to be eligble
QSS:
_ years after spouse’s death
Pay over __ the cost of maintaining a housewhole where a dependent child lives for the _ taxable year
Dependent child CANT be a ___
Single - everything else
Married filing separately - don’t want to talk to other person + protect from tax liability
Married filing jointly
Qualifying surviving spouse
2 years after spouse’s death
Pay over half the cost of maintaining a household where a dependent child lives for the whole taxable year
CANT be a foster child
Head of Household
Separate flash
Head of Household criteria
Individual ____
Pay over __ the cost for more than __ the taxable year
Qualifying person + requirement to live with
Individual unmarried
Pay over half the cost of maintaining a household of a qualifying person for more than half the taxable year
Qualifying person: Dependent child + relative (must live with), parent (not required to live with)
Qualifying Child criteria
CARES
Close Relative - child, foster, sibling
Age limit - younger than taxpayer + under age 19 (or age 24 if full-time student). No age limit if disabled
Residency - same residence for more than half the year
Eliminate gross income
Support test - qualifying child can’t contribute more than half their support. Scholarships not included
Qualifying Relative criteria
SURT
Support test - taxypayer must have supplied more than half the support
Under a specfic amount of gross income/ taxable income - $5,300
Relative test - children, parents, siblings, foster
Taxpayer lives with individual for the whole year
What is the rule for qualified children of divorced parents?
What about support?
What about equal custody?
Parent who has custody for the greater part of the year - claim as dependent
Does not matter whether that parent has provided more than half the support
If equal custody, parent with higher AGI will claim tax benefits
A married taxpayer who has lived apart from his or her spouse for the last six months of the year and maintains a household where a dependent child lives for more than half the year qualifies for which filing status?
Head of household
If your spouse dies this year what filing status?
MFJ
Income is determined as…
In the case of noncash income
Cash, property (FMV) or services obtained
Noncash income → FMV of property/services received
In order to be taxable, a gain must be…
Realized - change in form eg sale
Recognized → gain must be included on the tax return
Eg if a stock appreciates, you need to sell it to tax the gain
When is revenue recognized for taxes?
Recognition occurs in the period the revenue is actually or constructively received in cash or FMV or property
Is life insurance premiums included in gross income?
Not income for the first 50k of coverage
Premiums above 50k are taxable income
What are de minimus fringe benefits? Included in income?
What about meals + lodging?
Benefits that are so minimal that they are impractical to account for + excluded from gross income
Meals not included in gross income if on the employer’s premisis
In order to be nontaxable, the lodging must be required as a condition for employent. Eg firefighters
Is employee’s educational expenses included in gross income?
What about adoption?
Up to 5250 may be EXCLUDED from gross income
Can exclude up to 17670 of adoption expenses. Phase out
Don’t need to memorize these numbers
Is dependent care assitance included in gross income?
Amount
Either:
Children under age _
_ or _ that is disabled
Employees can exclude 7500 for qualifying dependents:
Children under age 13
Spouse or dependent that is disabled
What is the qualified tuition reduction?
Grad students may only exclude if:
Employees of educational institutions studying at the undergrad level may excludee tuition reductions from income
Grad students may only exclude if:
They are engaged in teaching or research
Tuition reduction is in addition to pay for teaching or research
Merchandise v service discounts
Employer parking
Transit
Merchandise → discount limited to % of gross profit. Excess reported as income
Service → discount limited to 20% of the FMV of services. Excess reported as income
Parking → up to 340 a month may be excluded
Transit → up to 340 a month may be excluded
What interest is taxable?
Nontaxable?
When:
Used to pay for __ __
Taxpayer over __ when bond is issued
__ requirements
Phase out?
Federal bonds
Fed or state for late payment of a tax refund
Nontaxable:
State + local bonds
US Series EE Savings bonds when:
Used to pay for higher education
Taxpayer over 24 when bond is issued
Income requirements
Phase out
When a taxpayers uses bonds to pay for a child’s education, bonds must be…
… registered in the taxypayer’s name
Taxable dividends?
Qualified dividends?
Holding period?
What tax rate?
Distributions of a corp’s earnings
Domestic investments
Held for more than 60 days during 120 day period that begins before the dividend declared
Preferred rate
Nonqualified divdends?
Taxfree distributions?
Employee stock ownership plan (ESOP)
Investment income
Return of capital
Stock split
Stock dividend
Life insurance dividend
Capital gain distribution
Types of IRA distributions taxable or non? Principal v earnings
Taxpayers required to start taking minimum distributions when?
April 1 of year after taxpayer is 75

What is a qualified distribution from a Roth IRA?
Made at least _ years after the first day of the year which taxpayer made their first contribution
One of the following
Made at least 5 years after the first day of the year which taxpayer made their first contribution
One of the following:
Taxpayer age 59.5+
Disabled
First time homebuyer + uses distribution to purchase a home
Distribution made to a beneficiary after taxpayer’s death
A premature distribution from an IRA is subject to?
Exception to tax
A 10% penalty tax
HIM DEAD TED

What is a Trump account? Criteria
Earnings are taxed at ___ tax rates when distributed
Tax-deferred investment account for children under age 18 with valid SSN
No distributions allowed until beneficiary turns age 18
Ordinary
What is an annuity?
2 Types?
Each payment consists of? Taxable v non
Contract between a taxpayer and an insurance company where taxpayer contributes a lump sum + receives regular annuity payments over time
Fixed → payments received over a fixed period of time
Life → payments received over lifetime
Return of investment → nontaxable
Earnings → taxable
For a fixed period annuity, what is the expected value of the annuity?
Annuity exclusion ratio?
Taxable portion of each?
Expected value = Amount of each payment x number of payments
Annuity Exclusion Ratio = Original investment / expected value
Taxable portion = Annuity exclusion ratio x monthly payment
How to determine taxable portion for life annuity payments?
If the taxpayer lives longer than expected
If they die before
Use IRS life expectancy tables
Nontaxble = original investment / IRS factor
Taxable portion = payment - nontaxable
Entire amount of additional payments received are taxable
Remaining unrecovered portion is deducted on the taxpayer’s final return
Is interest paid by the state on a late refund taxable?
Itemized in prior year
Standard deduction in prior year
Taxable
Nontaxable
Alimony gross income?
Requirements?
Before December 31, 2018, alimony included in gross income by recipient + deduction by the payor spouse
After, alimony NOT included in gross income, not deducted
Divorce agreement
Cash only
Can’t be designated as anything other than alimony
Is child support taxable?
If payments aren’t enough for child support + alimony what is the priority order?
What about property settlements?
Nontaxable to recipient + nondeductible to payor
Child support then alimony
Nontaxable + nondeductible
1040 Schedules
A → Itemized deductions
B → interest + dividends
C → Self Employed Net Income
D → property disposals
E → rental real estate, royalites + flow through income
K → Entity’s total income
Is unemployment compensation taxable?
What about social security?
Taxpayer must include in income the lesser of:
Yes
Taxpayer must include in income the lesser of:
50% or 85% of social security benefits received; or
50% or 85% of MAGI (AGI + Tax exempt interest + 50% of social security benefits
What adjustments to AGI to get MAGI?
AEIOU
Adoption exclusion
EE bond income
IRA
Out of US income
University student loans
Prizes + Awards
FMV → taxable income
Exclusion applies when the winner:
Is selected for the award without entering the contest
Assigns award directly to a governmental unit or charity -
Gambling winnings + losses taxable income?
Losses deductible on schedule _
Limited to __ % of losses
Only allowed to extent of
Carry forward?
Winnings included
Losses deductible on schedule A as an itemized deduction
Limited to 90% of losses
Only allowed to extent of gambling winnings
Can’t be carried forward
Punitive damages taxable?
Taxable if received:
In business context; or
Loss of personal reputation
Cancellation of debt taxable?
Exceptions
Yes
Death
Bankruptcy
Gift or inheritance
Scholarships taxable? Excluded if:
__ student
No __ performed to receive
Only spent on…
Degree v non degree
What about tuition reductions? Grad assistants taxed if…
Excluded if:
Degree-seeking student
No services are performed to receive
Only spent on tuition, books + supplies
Non-degree → taxable
Tuition reductions → grad assistants taxed if it’s their only compensation
Life insurance proceeds taxable?
Medicare?
Workers comp?
Personal injury?
Accident insurance?
Excluded from gross income
Interest taxable
EXCLUDE
What is the foreign earned income exclusion?
But must pass _ tests:
Taxpayers may exclude gross income from foreign earned income up to 132,900
But must pass 2 tests:
Bona Fida Residence →. lives in a foreign country for an entire taxable year
Physical presence → 330 days out of a year
Schedule C Business interest expense deduction
Limited to the sum of:
Can prepaid be deducted?
Limited to the sum of:
Business interest income;
30% of adjusted taxable income (EBITDA); and
Floor plan financing interest expense (debt used to acquire motor vehicles held for sale where debt secured by inventory)
Prepaid can’t be deducted until the period in which interest relates
Nondeductible expenses on schedule C
Salaries paid to ___ __
__ __ tax
__ __ of meal expenses
__ contributions
Salaries paid to sole proprietor
Federal income tax
Personal portion of meal expenses
Charitable contributions
How to calculate the self employment tax?
SE tax on 92.35 of self employment income
15.3% tax
What to do with hobby losses?
For vs not for profit
What about incomes?
If an activity has profit for 3/5 years, activity is for profit
If not for profit, can’t deduct expenses
Still required to include revenue as taxable income
What are the 3 different rental situations?
Rental of your house for less than 15 days
Rental income excluded from income
Rental of your house for more than 15 days
Expenses prorated between personal + rental use
Expenses deductible only to extent of rental income
Rental of property that you never use → true rental
How are guaranteed payments to partners vs distributions treated on the K1? Taxable income
Guaranteed payments to partners → business expense that reduce income
Separately stated item on the K1
Distributions → not taxable income
Partnership is taxed regardless of whether there’s a distribution
Owner’s share of ordinary business income partnership v s corp → is it self employment income?
Partnership → if actively involved → self employment income
If not actively involved → not self employment income
S corp → active or not → not self employment income
What is the tax basis loss limitation?
Carry forward?
A loss can only be flowed through an individual’s income tax return + deducted to the extent of the owner’s tax basis
Loss carried forward indefinitely
What is the excess business loss limitation?
NOLs? Different dates
Taxpayers can’t deduct an excess business loss
NOL prior to 2018 → carried forward 20 years. Can offset 100% of future taxable income
2018-2020 → 100% taxable income + carried forward forever
NOL 2021 → carried forward forever. 80% of taxable income
Adjustment FOR AGI
SMASSSH A PIE
Student loan interest deduction
Moving expenses
Alimony paid
Self-employment tax deduction
Self-employed health insurance deduction
Self-employed retirement plan contribution
Health savings account deduction
Attorney fees
Penalty on early withdrawal of savings
IRA contribution deduction
Educator expenses
Educator expenses? What type of AGI?
What level of eduction? How many hours in a school year?
Qualified expenses?
FOR AGI
Can deduct up to $350 of qualified expenses
Kindergarten through grade 12 teacher at least 900 hours during a school year
Qualified expenses → books, supplies etc
Student loan interest expense.
What type of AGI?
Limited to
Phase out?
FOR AGI
Limited to $2500
Phase out
What is a health savings account?
Make contributions → get a __ on your tax return
Enable workers with __ __ health insurance plans to make pretax contributions
Distributions not used to pay qualified medical expenses are:
Includable in __ __
Subject to an additional __% tax
HSA → tax-advantaged savings account for qualfiied medical expenses
Make contributions → get a deduction on your tax return
Enable workers with high deductible health insurance plans to make pretax contributions
Distributions not used to pay qualified medical expenses are:
Includable in gross income
Subject to an additional 20% tax
What are Archer Medical Savings account?
__ __ individuals
Employees of ___ ___
High ___ health insurance plans
How are they compared to HSAs?
Self employed individuals
Employees of small businesses (fewer than 50 employees)
High deductible health insurance plans
Archer less flexible
When are moving expenses deductible?
US military
Which IRA is a FOR AGI deduction?
Deductible traditional IRAs
Describe:
Self-employment tax deduction
Self-employed health insurance deduction
Self-employed retirement plan contribution
½ employer portion of tax → adjustment FOR AGI
Health insurance → can deduct all
REtirement → max amount they can contribute yearly depending on the plan
What are the types of self-employed retirement plans? Max contributions
Simplified employee pension (SEP) IRA:
Max employer contribution is the lesser of:
20% of net income from self employment after the deduction for self employment tax
72k
Savings Incentive Match Plan for employees (SIMPLE) IRA:
Max employee or employer lesser of:
100% of employee’s compensation
17k
Solo 401k
Only available for self employed taxpayers with no full time employees
Max is the lesser of:
20% of net income from self employment reduced by the deduction for ½ of self employment tax
72k
Who receives an additional standard deduction?
65+ or blind
What is the standard deduction for the dependent’s of another?
Standard deduction greater of:
1250
Earned income + 450
Medical expenses? What type of deduction? Max allowed?
What are nondeductible expenses?
FROM AGI
Qualified medical expenses
Minus insurance reimbursement
= Qualified medical expenses paid
Minus 7.5% of AGI
= Deductible medical expenses
Elective surgery
Travel
Vitamins
Funerals
Life insurance
Gym memberships
SALT Taxes. What type of deduction?
Max allowed?
Phase out?
Choice?
FROM AGI
Limited
Phase out
Can choose:
SALT income
SALT sales → actual sales tax paid or IRS table
Casualty losses. What type of deduction?
How to calculate?
Can only be claimed if…
FROM AGI
Less of decrease in FMV or property’s adjusted basis
MINUS insurance recovery
= Taxpayer’s loss
Minus 100
Eligible loss
Minus 10% AGI
= Deductible loss
… insurance claim was filed or losses not covered by insurance
Home Mortgage Interest. What type of deduction? Max allowed?
What are points?
Deductible?
FROM AGI
Deductions allowed for qualified residence interest on first or second home
Interest up to 750k MFJ
Points → fees that banks charge in return for a lower interest rate.
Deductible
Investment interest.
What type of deduction?
Limited to
Excess loss…
FROM AGI
Investment interest deduction limited to net taxable investment income
Excess loss carried forward indefinitely
Are political contributions + gifts deductible?
Nondeductible
Charity deduction limits for public charities
Also in excess of…
Carry forward how long?
What about charities services? What can they deduct? Example
Ceiling:
Cash 60% of AGI
Ordinary income property 50% of AGI
LTCG property 30% of AGI
Also in excess of 0.5% AGI Floor
5 years
Can deduct services. Includes cost of driving
Deduction for student living in taxpayer’s home
Charitable deduction when the taxpayer taxes into the home a full-time student
Not beyond the 12th grade
Up to $50 a month
Limitation on tax benefit of itemized deductions
For taxpayers in the highest marginal tax bracket of 37%, the total amount of itemized deductions allowed reduced by 2/37 of the lesser of:
Itemized deductions
Amount which taxable income plus itemized deductions exceed the applicable 37% bracket
What is the qualified business income deduction? How to determine?
Qualified Trade or Business vs specified service trade or business?
What does it exclude?
Minimum deduction?
20% deduction for eligible flow through entities QBI
QTB → anything else
SSTB → principal asset of the business is the reputation or skills of the employees. Eg accounting, law. If over taxable income, no deduction allowed
Exclude engineering
Greater of:
Amount calculated under regular QBI
$400
3 Types of limitations for QBI
What are the categories?
Limitations based on taxable income
W-2 wage
Overall taxable income
Category 1 → taxable income below threshold
Category 2 → taxable income above threshold
Category 3 → taxable income within threshold
QBI deduction calculation category 1
Lesser of:
Lesser of:
Tentative QBI deduction: QBI x 0.2
Overall limit: (TI before QBI deduction - Net Capital gains) x 0.2
QBI deduction calculation category 2
Steps:
Take the lesser of:
Calculate overall limit
Lesser of:
Take the lesser of:
Tentative QBI deduction: QBI x 0.2
W2 wage limit
Greater of:
50% of W2 wages
25% of W2 wages + 2.5% of unadjusted basis of qualified property
Calculate the overall limit. TI x 0.2
Lesser of step 2 and step 1
Tax on tips or overtime?
Qualified vehicle loan interest?
Enhanced deduction for seniors?
For all:
__ deduction
Phase out?
__ not eligible
Valid __ required
Max deduction
Phase out
MFS not eligible
Valid SSN required
What type of tax rate structure does the US have? What does this mean
LTCG taxed at what?
Progressive → higher marginal tax rate as taxable income increases
Preferential rates → 0, 15, 20
What are tax credits? What are the 2 basic types?
Reduce personal tax liability, dollar for dollar
Nonrefundable → reduce tax, but no refund
Refundable → reduce tax, refund
What are examples of the refundable tax credit?
FAAACES
Federal income tax withheld
American opportunity credit
Adoption credit
ACA premium tax
Child tax
Earned income
Excess social security tax
Child + Dependent Care Credit
Qualifying person (3)
Lesser of:
Max?
Phase out
Qualifying person:
Maintain a household
Work
Incur eligible expenses for dependent children under 13 or disabled any age, includes spouse
Eligible eg babysitter, day care
Lesser of:
Earned income of lesser earning spouse
Actual expenses incurred
Maximum allowable amount
Max 3000 for single, 6000 for MFJ
Phase out
What is the American Opportunity Tax Credit?
Qualified expenses?
How long?
Max credit?
On a ___ ___ basis?
Phase out?
What % is refundable?
Qualified expenses: tuition, books
How long: 4 years of undergrad
Max: $2500
100% of first 2000 of qualified expenses
25% of next 2000
Per student
Phase out
40% refundable
What is the lifetime learning credit?
How long?
Max credit?
On a ___ ___ basis?
Phase out?
What portion is refundable?
Is there a limit on AOTC vs LLC?
Unlimited number of years
20% of qualified expenses up to 10k
Qualified expenses: tuition undergrad + grad, courses to improve job skills
Per taxpayer basis
Phase out
Can claim both for different children
What is a coverdell education savings account?
Deductible?
Max contribution
Phase out?
Distributions are tax free to the extent that they are used for…
Any amounts remaining when beneficiary reaches __ must be distributed
Nondeductible
2000k
Phase out
… qualifying education expenses - tuition, books, room + board
Any amounts remaining when beneficiary reaches 30 must be distributed
What is a qualified tuition program?
Distributions are…
A person may purchase tuition credits on behalf of a beneficiary for payment of qualified higher education expenses - tuition, fees
… excluded
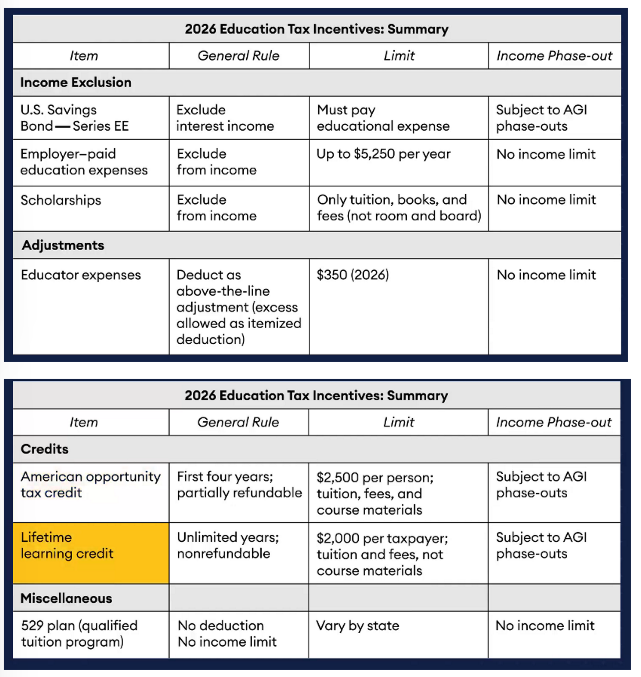
Education Tax Incentives Summary
Years
Refundable
Max allowed per __
What does it cover?
Phase out?
Credit for the elderly and/or permanant disabled
Steps
15% of eligibile income for those 65+ or disabled
Base amount
Reduce base amount by social security payments + ½ of AGI that exceeds a certain level
Multiply the result by 15%
What is the adoption credit? Max amount? Is it refundable?
Carry forward?
Phase out?
Max 17670
Up to 5120 refundable
5 years
Phase out
What taxpayers is the retirement savings contributions credit for?
Who is eligible (3)?
Allowable credit % depending on the?
Max contribution?
Low income taxpayers
At least 18 years old
Not a full time student
Not a dependent
10, 20 or 50% depending on the filing status + AGI
$2000
What is the foreign tax credit?
Limited to
Any disallowed may be carried over?
Lesser of:
Foreign taxes paid
Taxable income from all foreign operations/ total taxable worldwide income x US tax
Carried back 1 year
Carried forward 10 years
What is the general business credit?
Limit
Carried back + forward?
Regular tax liability after other credits - 25% of regular tax liability over 25k
Carried back 1 year, forward 20
What is the work opportunity credit?
Calculation
Qualified groups
Available to employees from a targeted group
40% of first 6000 of first year’s wages
Disabled
18-24
Vietnam veterans
Small employer pension plan start up costs - eligible employers:
No more than ___ employees who received at least __ in compensation
At least __ plan participant is a non-highly compensated employee
Employer can choose…
Greater of:
_% of the first 1000 of employers with 50- employees (_% for 51-100) OR
Lesser of:
__ for each employee who is eligible for the plan + not a highly compensated individual
___
Eligble employers:
No more than 100 employees who received at least 5k in compensation
At least one plan participant is a non-highly compensated employee
… to deduct start up costs or claim a credit. Can’t do both
Greater of:
100% of the first 1000 of employers with 50- employees (50% for 51-100) OR
Lesser of:
$250 for each employee who is eligible for the plan + not a highly compensated individual
5000
What is the small business healthcare credit?
Carried back?
Carry forward?
Employer contributes 50% of health converage on behalf of employees enrolled in a small business health plan
Carried back 1 year
Carried forward 20 years
Child tax credit
Limit
Qualifying child
phase out?
Refundable?
Lesser of:
2200 max
CARES
And US citizen
Phase out
Non refundable
Lesser of:
Excess of child tax credit liability
Earned income in excess of 2500 × 0.15
1700 per qualifying child
What is a non child dependent credit?
How much?
Children who are age __
OR other __ who are qualifying __
$500
Children who are age 17+
Other dependents who are qualifying relative
What is the earned income credit?
Is it refundable?
Low income earner
At least 25 years old but under 65
Refundable
When is excess FICA withheld?
When 2 or more employers withhold social security tax. Excess is a credit
1 employer → no credit allowed
What is the ACA Premium Tax Credit?
Refundable credit that helps low income families with health insurance