1) Economic methodology and the economic problem
 Call Kai
 Learn
 Practice Test
 Spaced Repetition
 Match
 Flashcards
 Knowt Play
1/10

Earn XP
Description and Tags
1) Economic methodology and the economic problem
11 Terms
Ceteris paribus
Assumption that other things are being held equal or constant, so nothing else changes.
Difference between positive and normative statements
Positive statements are objective and based on facts, describing the world as it is, while normative statements are subjective and based on opinions, describing how the world should be.
What are the factors of production?
Capital, Enterprise, Land, and Labour.
What’s the basic economic problem?
The basic economic problem is the issue of scarcity, where limited resources are insufficient to satisfy unlimited human wants and needs.
What is opportunity cost?
The cost of the next best alternative.
What does a PPF show?
The maximum productive potential of an economy, using a combination of two goods and services, when resources are fully and efficiently employed.
Draw a PPF diagram
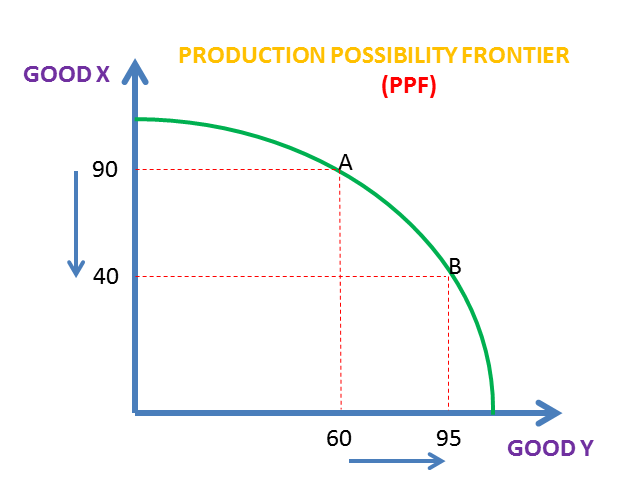
What are capital goods?
Goods which can be used to produce other goods, such as machinery.
What are consumer goods?
Goods which cannot be used to produce other goods, such as clothing.
What is allocative efficiency?
When economic resources are utilised to produce the combination of goods an services that maximise economic welfare.
What is signalling price function?
Prices provide information to sellers and buyers, influencing economic decisions.