COST 311 Exam 1
 Call Kai
 Learn
 Practice Test
 Spaced Repetition
 Match
 Flashcards
 Knowt Play
1/32

Earn XP
Description and Tags
33 Terms
Value-Added Activities
those activates that customers perceive as adding utility to the goods or services they purchase
Cost
a sacrifice of resources
Outlay Costs
past, present, or future cash outflow
Opportunity Cost
forgone benefit from the best alternative course of action
Expense
cost charged against revenue in an accounting periodthat represents the outflow of resources for goods or services.
THREE COSTS ARE:
Labor, Materials, and Overhead.
Product Costs
costs relating to inventory; costs that are recorded as an asset in inventory when incurred and expensed as COGS when sold
Period Costs
nonmanufacturing costs related to the firm; costs recognized for financial reporting when incurred
Direct Costs
costs that are directly traced to the product
Direct Materials
materials traceable to the product
Direct Labor
work traceable to transforming materials into the finished product
Indirect Costs
costs that cannot be reasonably traced to the productand are often allocated across multiple products.
Manufacturing Overhead
all production costs except direct materials and direct labor
Indirect Materials
Indirect Labor
Other Indirect Costs
Prime Costs
the “primary” costs of the product
Direct Materials
Direct Labor
Conversion Costs
costs necessary to “convert” materials
Direct Materials
Direct Labor
Marketing
costs necessary to sell the product
Advertising, Sales Commissions, Shipping
Administrative
costs necessary to operate the business
Executive Salaries, Data Processing, Legal Costs
Cost Allocation
assigning indirect costs to products, services, people, business units, etc.
Necessary when several departments share facilities or services
Cost-Volume-Profit (CVP)
explore the relations among revenue, costs, and volume and their effect on profits
Contribution Margin
the difference between price and variable cost
Break-Even Point
volume level at which profits equal zero
Cost Structure
the proportion of fixed and variable costs to total costs
Operating Leverage
the extent to which the cost structure is comprised of fixed costs
Margin of Saety
the excess of projected or actual sales volume (or revenue) over break-even volume
Raw Materials Inventory
materials purchased to make a product
Work-In-Process Inventory
products currently in the production process, but not yet completed
Finished Goods Inventory
completed products that have not yet been sold
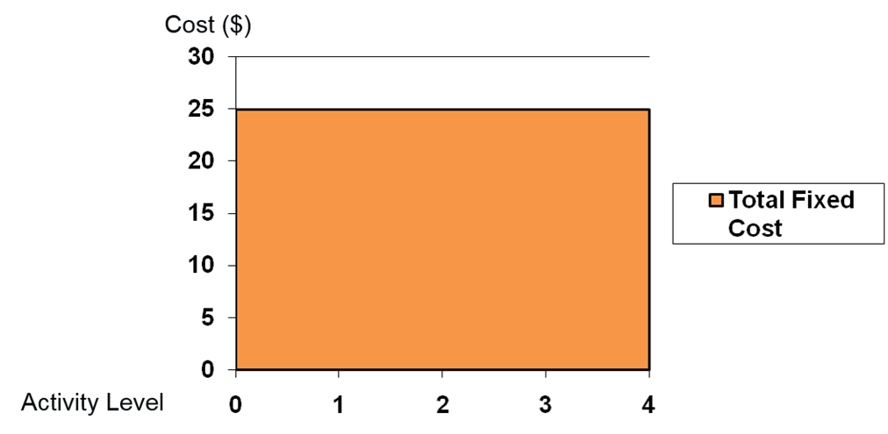
Fixed Costs
cost that does not vary with the volume of activity
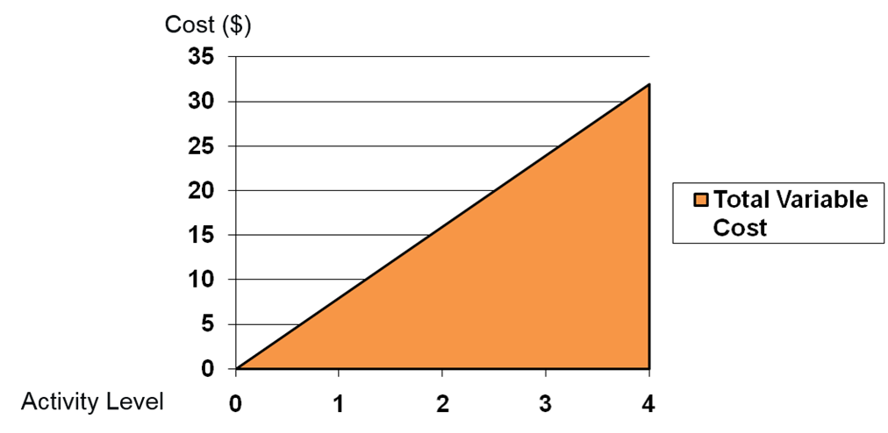
Variable Costs
cost that varies with the volume of activity; the sum of all variable costs of manufacturing and selling a unit of the product
Full Cost
the sum of all costs of manufacturing and selling a unit of product
Full Absorption Cost
the sum of all veriable and fixed costs of manufacturing a unit of the product
Full Absorption Costing
Required by GAAP used for: Financial Purposes and External Reporting
Sales Revenue
- COGS
= Gross Margin
Variable Costing
Used for: Managerial Purposes and Internal Decision Making
Sales Revenue
- Variable Costs
= Contribution Margin