Microeconomics Exam 2
 Call Kai
 Learn
 Practice Test
 Spaced Repetition
 Match
 Flashcards
 Knowt Play
1/99

There's no tags or description
Looks like no tags are added yet.
100 Terms
Economists normally assume that the goal of a firm is to
maximize profit
XYZ corporation produced 300 units of output but sold only 275 of the units it produced. The average cost of production for each unit of output produced was $100. Each of the 275 units were sold for a price of $95. Total revenue for the XYZ corporation would be:
26,125
Profit is defined as
total revenue minus total (opportunity) cost
An example of an implicit cost of production would be
the income an entrepreneur could have earned working for someone else
Foregone interest from investing your own personal savings into a business is an example of
an implicit cost
Economic profit is equal to
total revenue minus the total opportunity cost of producing goods and services
Accounting profit is equal to
total revenue minus the explicit cost of producing goods and services
Firms can have
(i) accounting profits and economic losses
(ii) accounting profits and economic profits
(iii) accounting losses and economic losses
(iv) accounting losses and economic profits
only (i), (ii), and (iii)
The production function describes
the relationship between quantity of inputs and quantity of output
The principle that rational people think at the margin
(i) is important to understanding how firms decide how many
workers to hire
(ii) is of little use to firms who are trying to maximize profit
(iii) provides the behavioral foundation for analyzing how firms make
optimal decisions
(i) and (iii) only
The marginal product of labor (MPL) can be defined as
total output / quantity of labor, where denotes "change in"
Diminishing marginal product of labor occurs when
adding another unit of labor increases output, but not by as large a margin as the previously employed labor
________ do not vary with the amount of output a firm produces.
Fixed costs
Categorizing a factor of production, such as a large piece of machinery, as a fixed cost or a variable cost often depends on
the time horizon being considered
The cost to produce one additional unit is called
marginal cost
If XYZ company chooses not to produce anything this month, its ________ will be zero for the month.
marginal cost
As the quantity produced increases,
average fixed cost decreases
Average total cost (ATC) equals
(fixed costs + variable costs) / quantity produced

The most efficient or optimal scale of production for Bill's Bones occurs at
Q = 150

Over what output range would marginal cost (MC) be above average variable cost (AVC) but below average total cost (ATC)?
120 to 150
Diseconomies of scale occur when
average total cost increases as output increases
Typically, the marginal cost curve ________ as output increases.
briefly decreases then increases
Which of the following cost functions always has a negative slope?
Average fixed cost (AFC)
The efficient scale of a firm occurs when
All of the above
When marginal cost (MC) is less than average total cost (ATC),
All of the above
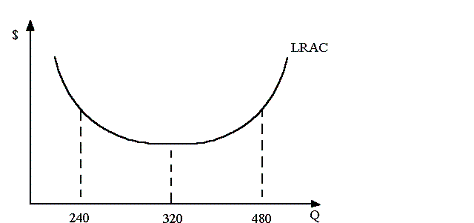
Decreasing (diminishing) returns to scale occur when output is at
Q = 400
A perfectly competitive market is characterized by which of the following attributes:
(i) many buyers and many sellers
(ii) barriers to entry
(iii) goods offered for sale are largely the same
(iv) price takers
(i), (iii) and (iv)
Quantity Price
1 $13
2 $13
3 $13
4 $13
5 $13
6 $13
7 $13
8 $13
9 $13
Over what range of output is marginal revenue (MR) declining?
None. Marginal revenue is constant over the whole range of output.
For a firm in a perfectly competitive market, __________________ equals the price of the good.
all of the above
If marginal cost exceeds marginal revenue
the firm may still be generating economic profit, but will not be maximizing profit.
To the best of their ability, a profit maximizing producer always chooses to produce the level of output where
marginal revenue equals marginal cost.

For the perfectly competitive firm depicted in the graph,
average revenue is equal to $5.00
Firms in a perfectly competitive market are said to be price takers because
All of the above
Which of the following industries is generally assumed to be most closely associated with a perfectly competitive market?
Agriculture
If you were to buy a product from a perfectly competitive firm, the price you would pay for the product would be
All of the above
If a perfectly competitive firm receives $500 in total revenue and has a marginal revenue of $10, what is the average revenue, and how many units were sold?
$10 and 50
When price is greater than marginal cost for a perfectly competitive firm
there are profit opportunities to be exploited by increasing production and output.
The supply curve for an individual firm in a perfectly competitive market
both b and c are correct
Firms maximize profits when marginal cost equals
marginal revenue.
When a firm in a perfectly competitive market shuts down production,
the market supply curve shifts left.
When new firms enter a market in pursuit of economic profit,
economic profit of existing firms in the market will begin to fall, all else equal.
The entry and exit decisions of firms are signaled by
economic profits and economic losses
The fundamental source of monopoly market power arises from
barriers to entry

Which of the average total cost curves shown in the graphs below would be consistent with a natural monopolist?
Panel c
A firm in a market characterized by significant barriers to entry, products which have no close substitutes, and no competitors, is said to be
a monopoly.
The goal of a(n) ________ is to maximize profit.
all of the above
An industry is a(n) ________ when a single firm can supply a good or service to an entire market at a lower cost than two or more firms could.
natural monopoly
In order to sell more of its product a monopolist
must lower its price on all units it sells.
When a monopolist faces a downward sloping market demand curve, its
marginal revenue is always less than the price of the units it sells.
A profit maximizing monopolist will produce the number of units that coincides with the level of output at which
marginal revenue is just equal to marginal cost.

Which of the graphs shown below best depicts the demand side of the market for a typical monopolist?
Panel b

A profit maximizing monopolist will choose to produce approximately _________ units of output.
Q1

A profit maximizing monopolist will have economic profits roughly equal to
(P4 - P1) * Q1

If this monopolist decided to produce (and sell) Q2 units of output
it would continue to make an economic profit, but would not be operating at a level consistent with profit maximization
As a monopolist increases the quantity of output it sells, the price consumers are willing to pay for the good __________.
decreases due to the law of decreasing marginal benefit
For a competitive firm, marginal revenue ________ the price of its good, and for a monopolist, marginal revenue ________ the price of its good.
equals, is less than

A profit maximizing monopolist will cause a deadweight loss equal to
F
The real economic problem with monopolies is their ability
to restrict output below the socially efficient level of production
Under conditions of monopoly, the socially efficient level of production occurs where the marginal cost curve intersects the ________ curve.
demand
Because P > MC, monopoly pricing prevents some mutually beneficial trades from taking place. These unrealized mutually beneficial trades are ________ to society.
a deadweight loss or excess burden
If a monopolist sells 100 units at $8 per unit and realizes an average cost of $6 per unit, what is the monopolist's profit?
$200
What is the deadweight loss due to monopoly pricing under the following conditions:
The price charged for goods produced is $16.
The intersection of the marginal revenue and marginal cost curves occurs where output is 10 units and price is $8.
The socially efficient level of production is 12 units
$8
One problem with government regulation of natural monopolies is that
the government typically has poor information about the socially optimal level of production
If a regulated natural monopoly is unable to generate profits at the "marginal-cost pricing" regulated level of production
it may be necessary for the government to subsidize the natural monopolist, which requires raising taxes or cutting public spending elsewhere
One problem with regulating a natural monopolist on the basis of its average cost is
that it does not provide an incentive for the monopolist to reduce or minimize its costs, possibly encouraging the monopolist to overstate costs or become less efficient

Which of the graphs shown below best describes the situation of a regulated natural monopolist with marginal-cost pricing regulation?
Panel d
A perfectly price discriminating monopolist is able to
maximize profit and produce a level of output consistent with optimal social well-being
If a monopolist is able to price discriminate
consumer surplus and deadweight losses are transformed into producer surplus and monopoly profits at a point closer to the socially efficient level of output

A monopolist who is able to engage in perfect price discrimination will have profit equal to
A + B + C + D + E
Price discrimination requires the firm to
both c and d
Markets which are characterized by only a few sellers with large market shares that sell similar or nearly identical (homogeneous) products are typically referred to as
oligopoly markets
In general, market structures that fall somewhere in between Monopoly and Perfect Competition are called
imperfectly competitive markets
Monopolistic competition is characterized by which of the following attributes:
(i) Many sellers
(ii) Product Differentiation
(iii) Barriers to entry
(iv) Natural monopolies
(i) and (ii) only
In a monopolistically competitive market structure, because each good sold in the market is _________________ each firm is considered a _________________.
slightly different, price setter or price maker
In a monopolistically competitive industry, price is likely to be _________________ marginal cost since each firm is a _________________.
above, price setter or price maker
When many sellers are involved in selling their products in a market, the market structure could be which of the following:
(i) perfect competition
(ii) monopolistic competition
(iii) monopoly
(iv) oligopoly
both (i) and (ii)
When freedom of entry is one of the attributes of a market structure, economic profits are
eventually driven to zero
A monopolistically competitive firm differs from a perfectly competitive firm because a monopolistically competitive firm
faces a downward sloping demand curve for its product due to product differentiation

Which of the graphs shown above would be consistent with a monopolistically competitive firm that is making economic profits?
Panel a

Which of the graphs shown above would be consistent with a monopolistically competitive firm that is making economic losses?
Panel b

If firms in a monopolistically competitive market are earning economic profits, which of the graphs shown would reflect the change in demand for incumbent firms as the market adjusts to its new equilibrium?
Panel a
In monopolistically competitive markets, economic losses ____________, and __________________ shifts the demand curve of incumbent firms to the ___________________.
signal some incumbent firms to exit, exit, right
As new firms enter a monopolistically competitive market, economic profits of existing firms ____________ and product diversity in the market _________________.
declines, increases

Which of the panels shown reflects a long run equilibrium in a monopolistically competitive market?
Panel a

Panel b in the set of images shown above is consistent with
a monopolistically competitive firm in short-run equilibrium, but not a long-run equilibrium
For a monopolistically competitive firm in long-run equilibrium ___________________ like in a monopoly market, and ________________________ like in a competitive market.
price exceeds marginal cost, price equals average total cost?
If regulators were to require that monopolistically competitive firms set price equal to marginal cost in the long run, then
all monopolistically competitive firms would experience economic losses
Advertising that conveys information about the prices of different goods being offered for sale
is likely to enhance the ability of markets to allocate scarce resources more efficiently
When advertising encourages customers to become more informed about all firms in the market, then
each firm is likely to have less market power and prices are likely to be lower
Firms that have large advertising budgets, such as those firms that advertise during the Super Bowl, are likely to be providing consumers with
a potential signal about product quality
When compared to perfect competition, the theoretical disadvantages of monopolistic competition are __________ and __________, whereas the practical benefit that consumers get in return is __________.
excess capacity, deadweight losses, product variety
In markets characterized by oligopoly,
there is often tension between cooperation with rivals and pursuit of self interest
When a profit maximizing oligopolist makes a production decision
it generally must consider the behavior of competing rival firms
There are two types of markets in which firms face some competition yet are still able to have some control over the prices of their products. The names given these market structures are
monopolistic competition and oligopoly/duopoly
An agreement among firms over production output and price is called _______. This group of firms that are acting in unison is called a ________.
collusion, cartel
An oligopolist is part of a cartel that is collectively producing at the monopoly level of output. The oligopolist, being self-interested will
increase production beyond the agreed-upon level to undercut rivals within the cartel
________ is the study of how people behave in strategic situations.
Game theory
The prisoners' dilemma is an important game to study because
it identifies the fundamental difficulty in maintaining cooperative agreements
Given the following prisoners' dilemma table, if Bonnie and Clyde make the appropriate self-interested decision independent of the other, how much time would each end up spending in jail?
8 years each
In game theory, a strategy is called a ________ if it is the best strategy for a player to follow regardless of the strategies pursued by other players.
dominant strategy