Checkpoint 1 (Quant, Econ, FSA, Corp)
 Call Kai
 Learn
 Practice Test
 Spaced Repetition
 Match
 Flashcards
 Knowt Play
1/74

There's no tags or description
Looks like no tags are added yet.
75 Terms
R² Coefficent of determination
(SST-SSE)/SST
RSS/SST
Adjusted R²

AIC
Forecast/Predictions
n * (ln(SSE/n)) + 2(k+1)
BIC
Better Fit
n x ln(SSE/n) + ln(n) x (k+1)
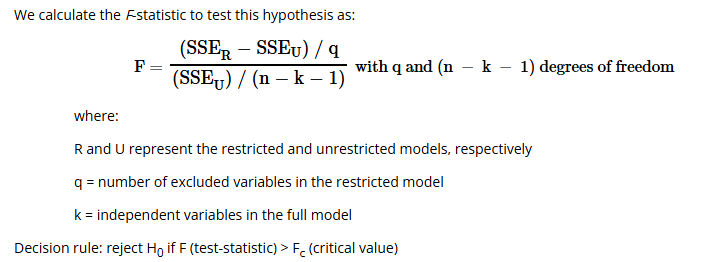
F-Test 1Tail
Test to see if adding additional variables contributed to explaining more of the model and if the coefficients are sig diff than 0
BP X² Test
n * Rresidual²
Heteroskedasticity test
Variance Inflation Factor and crit values
Multicolinearity
VIF = 1/(1-Rj²)
Rj is one variable on others
VIF | Interpretation |
|---|---|
VIF > 5 | Warrants further investigation (possible multicollinearity) |
VIF > 10 | Serious multicollinearity, correction required |
VIF = 1 | No correlation with the other independent variables |
Leverage
3(k+1)/n
Logit Regression
ln(p/1-p) = b0 + b1×1 + b2×2 + e
odds / probability
odds = ey
prob = odds / ( 1- odds) = 1/(1-ey)
Likelihood Ratio
LR = -2(log likelihood restricted - log likelihood unrestricted)
method to assess the fit of logistic regression models and is based on the log-likelihood metric that describes the fit to the data.
0 is good
AutoCorrelation Test

Mean Reversion Form
xt = b0/1-b1
Random Walk
xt = xt-1 + e
Random Walk with Drift
xt = b0 + b1xt-1 + e
ARCH

Normalized
(xi - xmin)/(xmax - xmin)
Precision
CORRECTLY PREDICTED POSITIVES OF ALL PREDICTED POSITIVES
TP / (TP + FP)
TP + FP = predicted positives
TYPE I ERROR
Recall
CORRECTLY PREDICTED POSITIVES FOR ALL ACTUAL POSITIVES
TP / (TP + FN)
TP+FN = all actual positives
TYPE II ERROR
Accuracy
CORRECTLY PREDICTED FOR ALL
(TP + TN) / (TP + TN + FP + FN)
F1 Score
(2 x P x R) / (P + R)
R = Recall
P = Precision
0-100 range high is better
True Positive Rate
TP/(TP + FN)
TP + FN = All positives
False Positive Rate
FP / (FP + TN)
FP + TN = All negatives
RMSE

Forward Premium/Discount
F - S0
Mark to Market Value

Covered Interest Rate Parity

Uncovered Interest Rate Parity
E(%ΔS)(A/B) = RA − RB
Forward Rate Parity
F = E(S1)
If the forward rate is equal to the expected future spot rate, we say that the forward rate is an unbiased predictor of the future spot rate. In such an instance, F = E(S1); this is called forward rate parity. In this special case, if covered interest parity holds (and it will; by arbitrage) uncovered interest parity would also hold (and vice versa). Stated differently, if uncovered interest rate parity holds, forward rate parity also holds (i.e., the forward rate is an unbiased predictor of the future spot rate).
Domestic Fisher Relation
Rnominal = Rreal + E(inflation)
Fisher Relation
Rnominal A − Rnominal B = E(inflationA) − E(inflationB)
Purchasing Power Parity
S(A/B) = CPI(A) / CPI(B)
Internation Parity Relationship Chart

Cobb Douglas
Y = TKαL(1 − α) |
Labor Productivity
output per worker = Y/L = T(K/L)α
Marginal Product of Capital
MPK = αY/K
Grinold-Kroner (2002)
E(R) = DY + ΔEPSR + π – ΔS + ΔP/E
ERP = [DY + Δ(P/E) + i + g – ΔS] – E(rf).
E(R) = dividend yield (DY) + expected capital gains yield (CGY)
expected capital gains yield = EPS growth (Δ EPS) + expected repricing (ΔP/E)
EPS growth = real EPS growth (ΔEPSR) + inflation (π) – change in shares outstanding (ΔS)
Cobb Douglas Growth Relation

growth rate in potential GDP
long-term growth rate of technology + α (long-term growth rate of capital) + (1 − α) (long-term growth rate of labor)
Sustainable growth of output per capita NEOCLASSICAL
g*=θ/(1−α)
Sustainable growth of output per capita (or output per worker)(g*) is equal to the growth rate in technology (θ) divided by labor's share of GDP (1 – α).
Sustainable growth rate of output (G*) NEOCLASSICAL
G*=θ/(1−α)+ΔL
ENDOGENOUS GROWTH
Growth = s·c − δ − n
saving rate
consumption
depn
labor force growth rate
Interest Income
Coupon +- Amortization
Equity Method Income
Profit x %confirmed x %shares owned - DepN/AmortN%
Equity Method Balance Sheet
Beg Balance + NI% - dividends received
CTA
Ending retained earnings
Ending RE=Beginning RE+Net income−DividendsEnding CTA as plug in equity
CTA end=Assets translated−Liabilities translated−Common stock historical−Ending REPeriod translation gain/loss under current rate method
ΔCTA=CTAend−CTAbegWhere it goes
Under the current rate method, translation gain/loss goes to OCI and accumulates in CTA in equity.
Temporal method: remeasurement gain/loss
No CTA under temporal method
Remeasurement gain/loss goes to the income statement
Income statement link through retained earnings
Ending RE=Beginning RE+Net income after remeasurement gain/loss−DividendsIf you solve for net income from RE:
Net income after remeasurement=Ending RE−Beginning RE+DividendsRemeasurement gain/loss
Remeasurement gain/loss=Net income after remeasurement−Net income before remeasurement
Full Goodwill and NCI
Purchase Price/ % shares owned - FV
NCI = fair value of the NCI (e.g., market price per share × number of shares held by minority shareholders)
Full goodwill is higher than partial goodwill because it also includes the NCI's share of goodwill.
NCI at period end = NCI at acquisition + (NCI % × subsidiary net income) − (NCI % × dividends paid by the subsidiary)
Partial Goodwill
Purchase Price - (% Owned * FV net identifiable assets) = % owned * full goodwill
NCI = NCI % × fair value of the subsidiary's identifiable net assets
NCI at period end = NCI at acquisition + (NCI % × subsidiary net income) − (NCI % × dividends paid by the subsidiary)
IFRS Goodwill Impairment
CV(asset + gw) - Recoverable amount(FV)
higher of selling costs or value in use
GAAP Goodwill Impairment
IF CV > FV
FV - FV net identifiable assets = implied FV Goodwill
GW - Implied FV GW = Impairment Loss
Tax Deduction for Stock Grants
share price on settlement date * # of shares vested
Tax Deduction for Stock Options
(Stock price - strike) * # of shares
Number of Treasury Shares
Number of Treasury Shares = assumed proceeds / avg share price in report period
assumed proceeds = cash proceeds + average unrecognized SBC
cash proceeds = number of options x strike
avg unrecognized SBC = avg last 2 period end value of unamortn expense
The treasury stock method nets gross new shares from options/RSUs against a hypothetical buyback funded by their proceeds, so only the shares left over count as dilution.
Shares repurchased = assumed proceeds ÷ average market price
Net dilution = gross shares − shares repurchased
Funded Status
FV of planned assets - PBO
Net interest Cost (IFRS)
Beginning funded status × discount rate
Interest Cost
Beginning PBO × discount rate
Expected Return on Plan Assets
expected rate × beginning plan assets
Ending PBO
Ending PBO = Beginning PBO + Current service cost + Interest cost + Past service cost ± Actuarial G/L − Benefits paid
Ending Planned Assets
Beg Planned Assets + Employee Contr + Actual Returns - Benefits paid
Pension Expense (IFRS / GAAP) income statement
IFRS
Current Service Cost + Net Interest cost + PSC
GAAP
Current SC + Int Cost - E(R) + AmortN G/L + Amort PSC
Liquidity Coverage Ratio
Highly liquid assets / expected cash outflows
Highly liquid assets are those that are easily convertible into cash, while expected cash flows are the estimated one-month liquidity needs in a stress scenario. The standards recommend a minimum LCR of 100%.
Net Stable Funding Ratio
available stable funding / required stable funding
Available stable funding is a function of the composition and maturity distribution of a bank's funding sources (i.e., capital, deposits, and other liabilities). Required stable funding is a function of the composition and maturity distribution of the bank's asset base.
Enough for 1 year horizon
Underwriting Loss Ratio
price adequacy
increase in loss reserve bad
decrease is good

Underwriting Expense Ratio
underwriting expenses including commissions / net premium written
operational efficiency

Loss and loss adjustment expense ratio
success in est. risk/losses
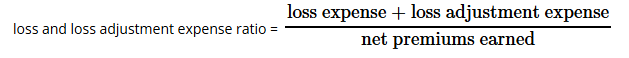
Dividends to policyholders ratio
CF to premium income

Combined Ratio & Combined Ratio After Dividends
L&L adj exp ratio + underwriting exp ratio
combined ratio + divs to policyholders
low is generally good for both
dupont 6 stage
ROE = NI/EBT x EBT/EBIT x EBIT/REV x REV/ASSET x ASSET/EQ
Accrual & Accrual Ratio (BS)
Accrual
NOAend - NOAbeg
Accural Ratio
NOAend-NOAbeg / avg(NOAend - NOAbeg)
Accrual & Accrual Ratio (CF)
Accrual
NI - CFO - CFI
Accural Ratio
NI - CFO - CFI / avg(NOAend - NOAbeg)
Cash generated from operations
CGO = EBIT + NCC - change in NWC
common ratios
CGO/EBIT
CGO/CAPEX
CGO/total debt
CGO/int coverage
Market Value of Decomposition (PE ratio)
(Mkt Cap of Parent - Associate Mkt Cap) / (NI - parent % of associate earnings)
Benish M Score
M-score = −4.84 + 0.920 (DSR) + 0.528 (GMI) + 0.404 (AQI) + 0.892 (SGI) + 0.115 (DEPI) − 0.172 (SGAI) + 4.679 (Accruals) − 0.327 (LEVI)
M-score = Score indicating probability of earnings manipulation
DSR (days sales receivable index) = (Receivablest/Salest)/(Receivablest−1/Salest−1).
Changes in the relationship between receivables and sales could indicate inappropriate revenue recognition.
GMI (gross margin index) = Gross margint−1/Gross margint.
Deterioration in margins could predispose companies to manipulate earnings.
AQI (asset quality index) = [1 − (PPEt + CAt)/TAt]/[1 − (PPEt−1 + CAt−1)/TAt−1], where PPE is property, plant, and equipment; CA is current assets; and TA is total assets.
Change in the percentage of assets other than in PPE and CA could indicate excessive expenditure capitalization.
SGI (sales growth index) = Salest/Salest−1.
Managing the perception of continuing growth and capital needs from actual growth could predispose companies to manipulate sales and earnings.
DEPI (depreciation index) = Depreciation ratet−1/Depreciation ratet, where Depreciation rate = Depreciation/(Depreciation + PPE).
Declining depreciation rates could indicate understated depreciation as a means of manipulating earnings.
SGAI (sales, general, and administrative expenses index) = (SGAt /Salest)/(SGAt−1/Salest−1).
An increase in fixed SGA expenses suggests decreasing administrative and marketing efficiency, which could predispose companies to manipulate earnings.
Accruals = (Income before extraordinary items9 − Cash from operations)/Total assets.
Higher accruals can indicate earnings manipulation.
LEVI (leverage index) = Leveraget/Leveraget−1, where Leverage is calculated as the ratio of debt to assets.
Increasing leverage could predispose companies to manipulate earnings.
CRP from Sovereign Yield Spread and std
