CF Chapter 13: Risk, Cost of Capital, and Valuation
 Call Kai
 Learn
 Practice Test
 Spaced Repetition
 Match
 Flashcards
 Knowt Play
1/55

Earn XP
Description and Tags
How to determine a firm's cost of equity capital and overall cost of capital
Name | Mastery | Learn | Test | Matching | Spaced | Call with Kai | Chat |
|---|
No analytics yet
Send a link to your students to track their progress
56 Terms
Big picture of Corporate Finance
Corporate finance theories are mostly about valuation (determining the value of a bond, stock, project, company
Discounted cash flow valuation
For safe projects, calculate NPV as:
NPV = C0 + Summation Ct / (1+rf)t
Where
Ct = project cash flows in period t
rf = risk-free rate
For risky projects calculate NPV as
NPV = C0 + Summation C (bar)t / (1+r)t
Where
C (Bar) t = expected project CF in period t
r = cost of capital
What is the correct discount rate (r) to calculate NPV?
Cost of capital
Definition: Cost of Capital
Expected return on a financial asset of comparable risk
Two assumptions with NPV
The company uses only equity finance (all equity case)
The project has the same risk as firm’s existing assets
Cost of capital = Expected return on a firm’s stock
How do we calculate expected return on a firm’s stock?
Capital Asset Pricing Model (CAPM)
Equation for CAPM
r = rf + B(rM - rf )
A firm with excess cash can either ____________ or _____________
can either pay a dividend or make a capital investment

Because stock holders can reinvest the dividend in risky financial assets (______ ___), the expected return (_______ ____) on a capital-budgeting project should be at least as great as the expected return on a financial asset of comparable risk
Because stock holders can reinvest the dividend in risky financial assets (opportunity cost), the expected return (discount rate) on a capital-budgeting project should be at least as great as the expected return on a financial asset of comparable risk
To calculate expected return we need 3 things
Risk free rate
Market Risk Premium
Beta for firm’s stock
Risk free rate
Symbol: Rf
This reflects the pure time value of money - reward for waiting for your money without any risk
Market Risk Premium
Equation: (rM - rf )
This reflects the reward for the market offers for bearing an average amount of systematic risk
Beta for a firm’s stock
B (beta)
This reflects the amount of systematic risk a firm has relative to the market average
Assumptions when determining appropriate discount rates for a new plan/project
Beta of new project is the same as the beta of the company
Firm is entirely equity financed
We accept projects with a ______ NPV, and reject NPVs that are ______
Accept: Positive NPV
Reject: Negative NPV
Equation to determine expected return
E(Ri) = summation Pi Ri (probability economic state will occur x the rate if that state does occur)
How to calculate the expected return of a portfolio
E(Rp) = Summation Wi [E(Ri)]
Using the Security Market Line (SML) to determine whether or not to accept projects
Accept projects whose IRRs exceed the cost of equity capital (above the line) and reject projects whose IRRs fall short of the cost of capital (below the line)

If a stock sits above the SML does that mean that it’s underpriced or overpriced?
it is UNDERPRICED, getting a higher return for the same risk as another stock
Markets are efficient so investors will begin buying stock B, which will drive the price of the stock up
What is the slope equation for the Security Market Line
Slope = [ E(Ri ) - Rf ] / B
CAPM vs SML
The Capital Asset Pricing Model (CAPM) is a mathematical formula that calculates expected return, while the Security Market Line (SML) is the visual graph of that exact formula.
Core Definitions
• CAPM: A formula that links a security's risk to its expected return.
• SML: A straight line on a chart that plots the CAPM equation
Basic method/equation for measuring company’s beta
Bi = Cov(ri , rM) / Var(rM)
Beta measures…
The responsiveness of a security to movements in the market
What is the beta of a risk free asset?
0
What is the beta of a market portfolio?
1
T/F A Beta cannot change
FALSE
most analysts argue that betas are generally stable for firms remaining in the same industry
The is not to say that a firm’s beta cannot change
Changes in product line
Changes in technology
Deregulation
Changes in financial leverage
Industry Beta
Frequently argued that one can better estimate a firm’s beta by involving the whole industry
If you believe that the operations of the firm are similar to the operations of the rest of the industry, you should use the industry beta
If you believe that the operations of the firm are fundamentally different from the operations of the rest of the industry, you should use the firm’s beta
Do not forget about adjustments for financial leverage
Determinants of Beta → two types of business risk
Cyclicality of Revenues
Operating Leverage
Business Risk: Cyclicality of Revenues
Highly cyclical firms have high betas
Retailers and automotive firms fluctuate with the business cycle
Transportation firms and utilities are less dependent on the business cycle
Business Risk: Operating Leverage
Ratio of fixed costs to variable costs
Firms with higher fixed costs relative to variable costs tend to have higher betas
Read over the information about the two firms. Which firm will tend to have a higher beta?
Firm A - high operating leverage
If there is a recession → sales will decrease, costs are unchanged, profits go down sharply
Firm B - low operating leverage
Recession → sales down, scale back on variable costs so costs go down, profits go down moderately
Firm A will tend to have a higher beta
Extended definition Degree of Operating Leverage
Measures how sensitive a firm (or project) is to its fixed costs
Operating leverage __________ as fixed costs rise and variable costs _______
Operating leverage increases as fixed costs rise and variable costs fall
Operating leverage __________ the effect of cyclicality on beta
magnifies
Equation for Degree of Operating Leverage
DOL = Delta EBIT/EBIT x Sales/Delta Sales
Definition: Financial Leverage
The extent to which a firm relies on debt
Levered firms must make interest payments (fixed costs of finance)
Equation for beta demonstrating relationship between firm’s debt, equity, and assets
BAsset = D/D+E x BD + E/D+E x BE
Beta of _____ is constant, but we must solve for the beta of _____
Beta of debt is constant, but we must solve for the beta of equity
Beta of Equity equation (can also include taxes)
BE = BUL [1+D/E]
Version with taxes: BE = BUL [1+D/E(1-Tc)]
Taxes on debt mitigates the impact of debt on beta because of tax savings
If D/E = 0, AKA the firm has no debt, then what is BE
BE = BAsset
If a company has debt, and then pays some of it (but not all of it) off, what is the impact on Be?
Be decreases
Ex: Consider Grand Sport Inc., which is currently all-equity financed and has a beta of 0.9. The firm has decided to lever up to a capital structure of 1 part debt and 1 part equity
Since the firm will remain in the same industry, the asset beta should remain 0.9
However, assuming a zero beta for its debt, its equity beta would become twice as large
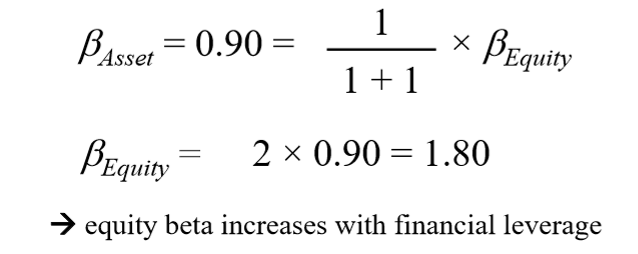
Definition: Cost of debt
Interest rate required on new debt issuance
Ex: Yield to maturity on outstanding debt
The combination of returns from both equity and debt is called
The weighted average cost of capital (WACC)
Steps to Calculating RWACC
Calculate requity using CAPM
Calculate D/D+E and E/D+E
Put it all together into the rWACC formula

The correct discount rate for a project should reflect the _______ risk of the project’s cash flows
systematic
The Bequity you estimate for a firm reflects the systematic risk of the company’s _______ assets and _____ financial choices
The Bequity you estimate for a firm reflects the systematic risk of the company’s existing assets and past financial choices
If a project is the same systematic risks of existing assets and will be financed the same way, using estimate ______ ______ to calculate discount rates is valid
Bequity
If a project is higher/lower systematic risk than existing assets or is financed differently, one must…
adjust the betas and the discount rates to reflect this difference
How to go about firm valuation
The value of the firm is the PV of expected future (distributable) cash flow discounted at the WACC
To find the equity value, subtract the value of the debt from the firm value
Some example steps to go through when calculating firm value
Estimate the cost of equity and cost of debt
Estimate an equity beta to estimate the cost of equity
Can often estimate the cost of debt by observing the YTM of the firm’s debt
Second, determine the WACC by weighting these two costs appropriately
How do we determine the cost of equity capital?
CAPM
How can we estimate a firm or project beta?
Firm: Comparing similar industry betas, SML
Project Beta: Using Basset = Be = BUL [ 1+D/E ]
How does leverage affect beta?
Increase in leverage → increase in equity beta
decrease in leverage → decrease in equity beta