a Unit 3 Area of Study 1b
 Note
 Call Kai
 Learn
 Practice Test
 Spaced Repetition
 Match
 Flashcards
 Knowt Play
1/41

There's no tags or description
Looks like no tags are added yet.
Name | Mastery | Learn | Test | Matching | Spaced | Call with Kai | Chat |
|---|
No analytics yet
Send a link to your students to track their progress
42 Terms
Accounting Assumptions
Period
Entity
Going concern
Accrual basis
Period Assumption
The assumption that reports are prepared for a specific period of time, such as a month or year, to obtain comparability of results.
Entity Assumption
the assumption that the records of business activities of an entity are kept completely separate from those of the owner of the entity, as well as from those of other entities.
Going Concern Assumption
The assumption that financial reports are prepared with the expectation that the entity will continue to operate in the future.
Accrual Basis Assumption
The assumption that revenue is recognized in the period in which the expected inflow of economic benefits can be measured in a faithful and verifiable manner.
Qualitative Characteristics
timeliness
understandability
relevance
faithful representation
comparability
verifiabillity
Timeliness
information should be available to decision-makers in time to influence decisions.
Understandability
financial information is comprehensible to users with reasonable business and economic knowledge.
information should be presented clearly and concisely.
Relevance
Information that directly assists users in making decisions related to economic outcomes.
Faithful Representation
information reported must be a faithful representation of the real-world economic event it represents
- free from error, neutral, complete
Comparability
Information about an entity is more useful if it can be compared with similar information about other entities, and with similar information about the same entity for another date or period.
Verifiability
different observers can reach a consensus that an event is faithfully represented
Current/non current Asset
A present economic resource controlled by the entity as a result of past events
Current/non current Liability
A present obligation of the entity that results in an outflow of future economic benefit due to past events
Owner’s Equity
The residual interest after liabilities are subtracted from assets
Revenue
An increase in assets or decrease in revenues that increases owners’ equity, other than those relating from contributions from the owner
Expense
A decrease in assets or increase in liabilities that decreases owners’ equity other than those relating to distributions to the owner
Accounting equation
Assets - liabilities = owner’s equity
Product cost
Any cost incurred in getting a piece of inventory into a condition and location ready for sale, allocated to each individual inventory on a logical basis
Period cost
Any cost incurred in getting a piece of inventory into a condition and location ready for sale, which cannot be allocated to each individual inventory on a logical basis
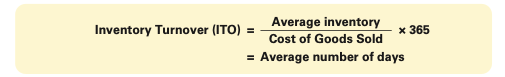
Inventory turnover
Measured in faster/slower
Lower days faster, higher days slower
Net realisable value
Estimated selling price - direct selling expense no gst
How to enhance inventory control
physically rotating inventory on hand so oldest is first
ensuring adequate security for products to decrease theft/fraud
introducing complementary products to boost sales
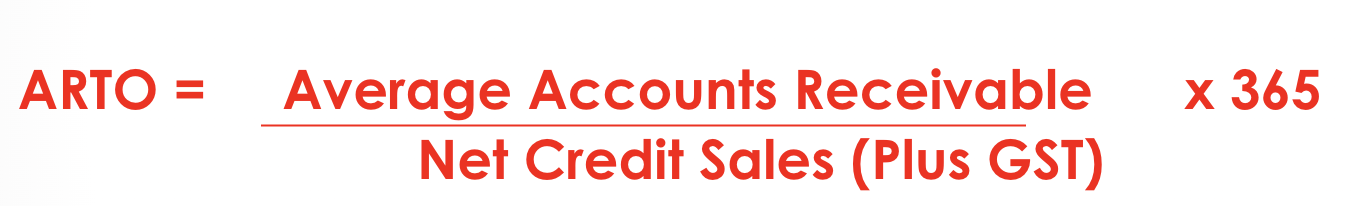
Accounts receivable turnover
the average time it takes for accounts receivable to settle accounts
measured in faster/slower
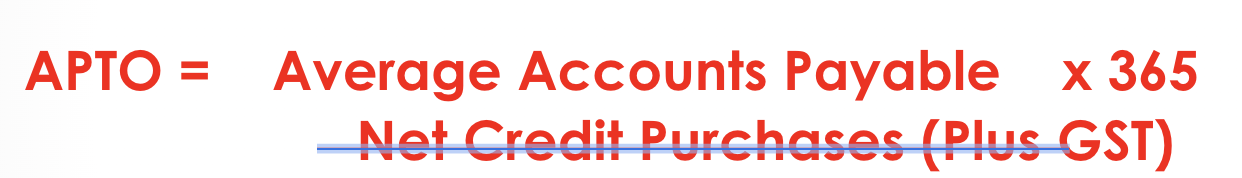
Accounts payable turnover
the average time it takes for business to settle accounts with accounts payable
measured in faster/slower
What to measure accounts payable/receivable turnover with (Non financial information)
past performance
competitor performance
credit terms offered
Bad debts
debts that have to be written off as irrecoverable or uncollectible since it’s confirmed that Accounts Receivable is unable to pay due to liquidation/bankruptcy
Doubtful debts
debt that is unlikely to be collected but not written off since it’s not confirmed that Accounts Receivable cannot pay, quantified by past experience
Ethical considerations
The social and environmental consequences of a financial decision
QCs about inventory write down
faithful representation, relevance
QCs/ethics about bad and doubtful debts
Positive of recording:
faithful rep the true state of profit/sales in the business
owner has all relevant info to affect decision making
ethical since AR isn’t overstated
Negative:
estimates that cannot be verified from source docs
AAs about bad and doubtful debts
When bad debt is in the same period as credit sale this fulfills accrual basis
Sometimes it isn’t so there is estimate
How to improve inventory control
Introduce complementary products
Monitor seasonal products
Monitor selling prices
Actions for too slow ITO
Maintain lower levels of inventory
Implement strategies to increase sales
Actions for too fast ITO
Increase selling price
Increase inventory levels
How to manage accounts receivable
Offer discounts to fast paying people
Legal action
Sending emails/phone reminders
Internal control
A system of procedures that protect the assets of a business and ensure the accuracy of its accounting system
Internal control and cash/bank account
Maintain accounting journals
take cash home/don’t leave in premises
Internal contorl and physical assets
Security to protect
Video surveillance
QCS about period/product cost
Relevance - is this useful for decision making to be included in reports?
Why does inventory write down happen
Obsolete
damaged
out of season
QCs about inventory write down
Faithful representation