Econ Midterm 2
 Call Kai
 Learn
 Practice Test
 Spaced Repetition
 Match
 Flashcards
 Knowt Play
1/89

There's no tags or description
Looks like no tags are added yet.
Name | Mastery | Learn | Test | Matching | Spaced | Call with Kai | Chat |
|---|
No analytics yet
Send a link to your students to track their progress
90 Terms
Economics
The social science that studies production and trade
Spontaneous Order
Order that is the product of human action, but not human design. (Ex. humans made language but no ONE person invented it.)
Positive Analysis
Analysis that attempts to describe the way things are in reality. (How the world is.)
Normative Analysis
Analysis that describes a value judgment. (How the world should be.)
Market Economy
A social system in which resources are privately owned and controlled. (Ex. Laissez fair and free market system.)
Command Economy
A social system in which resources are collectively owned or controlled (typically through a government). (Ex. Communism.)
Mixed Economy
A social system in which some resources are privately owned and controlled, and some are owned or controlled by the government.
The Four Starting Points of Economics
Scarcity (there is a limited amount of everything)
Unlimited desires (people always want more of something)
Methodical individualism (everything is caused by human belief/actions)
Rational choice (people act in self interest)
Price System
A network of interrelated prices of goods and services.
Exchange of Equivalents (300s BCE)
The theory that people exchange one good for another when both parties value the goods equally.
Just Price Theory (700s CE)
There is a single just price at which each good should be sold.
Mercantilism (1600s)
Social order requires government planning
Money constitutes real wealth for a nation.
Exchange is zero-sum-game, one party must loose for the other to win.
There is a “public interest” separate from the interests of actual individuals.
Nominal Value of Money
The face value of a certain amount of money, with no inflation or change in purchasing power. (Ex. amount earned before taxes)
Real Value of Money
The goods and services that can be purchased with a certain amount of money. (Ex. amount earned after taxes)
Invisible Hand
Adam Smith’s metaphor for the power of individual self-interest to create spontaneous order.
Subjective Theory of Price (NOT CLASSICAL THOUGHT)
The theory that the price of a good is determined by its utility.
Water-Diamonds Paradox (The Paradox of Value)
Water is very useful but has a low price, while a diamond is not very useful but has a high price.
Labor Theory of Value
The theory that the price of a good is determined by its cost of production or amount of labor used for production.
Iron Law of Wages
The price of labor is determined by minimum amount to sustain human life and reproduction.
Intrinsic Value Theory
The theory that the value of an object is inherent in the object itself.
Problems with the Labor Theory of Value
1. How do you measure labor?
2. Labor has a price.
3. It is a theory of intrinsic value.
4. It ignores the context of the exchange.
A Good
A useful thing that is subject to human control.
Four requirements for something to be a good:
1. A human need must exist.
2. The object must have properties that allow it to satisfy this need.
3. Humans must know of this causal connection.
4. Humans must have sufficient control over the object to make use of it.
Consumer Good (First Order Good)
A good that serves our desires directly. (Ex. a car.)
Producer Good (Higher Order Good)
A good that is used in the production of another good. (Ex. for a car it needs: rubber, iron, and labor.)
Structure of Production
The set of steps by which producer goods are used to produce a consumer good.
Theory of Derived Demand
The demand for a good, service, or factor of production that occurs because of the demand for another, related final product. (Ex. Higher demand for cars means higher demand for materials to make a car.)
Marginal
At the edge.
Marginal Unit
The next unit gained or given up.
Marginal Utility
The additional utility that a person gets from having one more unit of a good, or loses from having one less unit of a good.
Theory of Marginal Utility (or the Marginal Theory of Value)
The theory that the price of a good is determined by its marginal utility. (Ex. first slice of pizza is satisfying but last eaten is unsatisfying.)
Ordinal Ranking
A list in order of preference.
Opportunity Cost (Applies to every choice.)
The best alternative given up when making a choice. (Ex. Study more and ensure higher score or sleep and be more well rested.)
Diminishing Marginal Utility
As a person acquires more units of a good, the satisfaction they derive from each new unit is lower than the previous unit. (The more you have the less satisfying it is.)
Increasing Marginal Opportunity Cost
As a person gives up more units of a good, the satisfaction they give up with each new unit is higher than the previous unit.
Four Conditions for Trade to Take Place:
1. The parties have reverse values.
2. Both parties must recognize the opportunity for exchange.
3. Both parties must have the power to transact.
4. The benefits of the transaction must outweigh the costs.
Range of Indeterminacy
The range of potential prices. (EX. Between max buying price and min selling price.)
Market Clearing Price
A price at which anyone who wants to buy or sell can find a willing trade partner. (Overlap between demand and supply curve, when both are equal.)
Quantity Demanded
The amount of a good a person is willing and able to buy at a particular price.
Demand Curve
The curve that shows the relationship between the price of a good and the quantity demanded.
Law of Demand
There is a negative relationship between the price of a good and the quantity demanded.
Quantity Supplied
The amount of a good a person is willing and able to sell at a particular price.
Supply Curve
The curve that shows the relationship between the price of a good and the quantity supplied.
Law of Supply
There is a positive relationship between the price and the quantity supplied.
Market Clearing Quantity
The number of exchanges that take place at a market clearing price.
Four implications of the Price Determination Model:
1. Buyers who value the good more exclude buyers who value it less.
2. Sellers who value the good less exclude sellers who value the good more.
3. The price for all traders is set by the marginal traders. In other words, the
price for all buyers and sellers is set by the maximum buying price and
minimum selling price of the marginal buyers and sellers.
4. As more parties enter the market, the range of indeterminacy tends to
shrink.
Comparative Statics
Studying how supply and demand curves shift.
Increase
Shift to the right
Decrease
Shift to the left
Shifts of the Demand Curve
QD = f ( Price, Consumer Tastes, # of Buyers, Income, Prices of Related Goods)
Elasticity
A measure of the responsiveness of one variable to changes in another variable.
Income Elasticity of Demand
The effect that a change in a person’s income has on their demand for a certain good.
Normal Goods
Demand increases when income increases, when income decreases demand decreases
Inferior Goods
Demand decreases when income increases, demand increases when income decreases
Cross-Price Elasticity of Demand
The effect that a change in the price of one good has on the demand for another good
Substitutes
Goods that perform a similar function or satisfy a similar human desire (demand increases when others price increases)
Complements
Goods that are more valuable when consumed together (when compliment price increases, demand decreases)
Shifts of the Supply Curve
QS = f ( price , # of sellers , technology , input prices, per-unit taxes or subsidies )
Tax
When the government takes money from you when you engage in a certain activity.
Subsidy
When the government gives you money when you engage in a certain activity.
Elasticity Equation

%change dependent variable/% change independent variable
Own-Price Elasticity of Demand
The responsiveness of the quantity demanded for a good to changes in the price of that good.
Own-Price Elasticity of Demand Equation

% change of quantity demanded/% change in price (same for supply, just % of supply instead)
Inelastic
When the absolute value of a good’s price elasticity of demand is less than 1 (E=0 is perfectly inelastic)
Elastic
When the absolute value of a good’s price elasticity of demand is greater than 1 (E=∞ is perfectly elastic)
Total Revenue
Price x Quantity (TR= P*Q or %ΔTR ≈ %ΔP + %ΔQ)
Degrees of Elasticity

Income Elasticity of Demand

%change in quantity demanded/%change in income
Cross-Price Elasticity of Demand
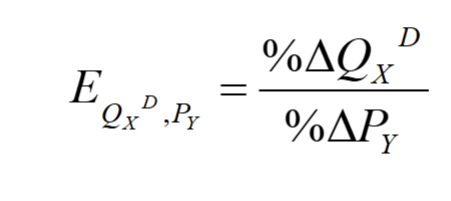
%change in quantity demanded of Good A/% change in price of Good B)
Demand curve
The set of maximum buying prices
Supply curve
The set of minimum selling prices
Consumer Surplus
A measure of the gain that the buyer experiences from an exchange.
Producer Surplus
A measure of the gain that the seller experiences from an exchange.
Total Gain from Trade
The sum of consumer surplus and producer surplus.
Equilibrium
A situation in which no individual wants to change their own behavior
Shortage

When the quantity supplied is lower than the quantity demanded.
Surplus

When the quantity demanded is lower than the quantity supplied.
Dead Weight Loss
Gains from trade that are not being made.
Economic Efficiency
A situation in which all possible gains from trade are being made.
Entrepreneur
A person who takes advantage of a profit opportunity in the market.
Direction of Causation
The causal relationship between one event and another.
Price Control Law
A law that mandates what price buyers and sellers must trade at.
Effective Price Control
A price control law that keeps the price above or below the market-clearing price.
Maximum Price Control Law (Price Ceiling)
A law that prohibits people from trading at a price above a legal maximum.
Minimum Price Control Law (Price Floor)
A law that prohibits people from trading at a price below a legal minimum.
Maximum Price Control Laws:
• Create a shortage
• Benefit some consumers and harm others
• Harm all producers
• Do more harm than good
Minimum Price Control Laws:
• Create a surplus
• Benefit some producers and harm others
• Harm all consumers
• Do more harm than good
Rent Control Law
A maximum price control on rental housing.
Effects of Rent Control:
• Housing shortage
• Ruined buildings
• Lawbreaking
• Misallocation of Housing
• Bias Against Low-Income Housing
• Lowers the Cost of Discrimination by Landlords
Calculating Price change %
((new-old)/old)*100