Labour market
 Call Kai
 Learn
 Practice Test
 Spaced Repetition
 Match
 Flashcards
 Knowt Play
1/54

There's no tags or description
Looks like no tags are added yet.
55 Terms
Markdown of a monopsony
The markdown in a monopsony is the gap between the value of a worker’s marginal product and the wage they receive. It represents the power a monopsony has through the monopsonist’s ability to set wage below the marginal return of labour. Since MCL>w, workers receive less than the value they add to the firm.
Markdown equation
Markdown = (MRL-w)/MRL

Labour supply elasticity and markdown
Inversely related - higher labour supply elasticity = lower markdown
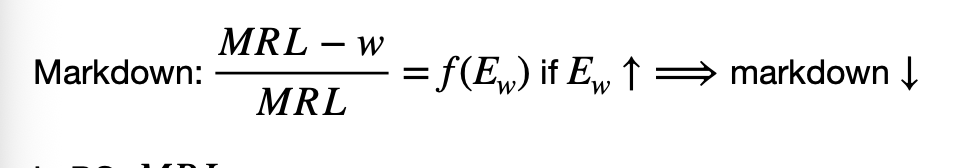
Labour supply elasticity
Ew = % change in the quantity of labour supplied / % change in wage
Ew is the wage elasticity of labour supply: how strongly the quantity of labour supplied responds to a change in wages.

High Ew - high labour supply elasticity
Workers respond strongly to wages → the monopsonist has less power to pay low wages → smaller markdown. If you change the wage, the quantity of labour supplied changes a LOT.
Low Ew - low labour supply elasticity
Workers respond little to wages → the monopsonist has more power to pay low wages → larger markdown. If you change the wage, the quantity of labour supplied does not change that much. More elastic labour supply means workers respond more strongly to wage cuts, limiting the monopsonist’s ability to pay below MRL.
What is the condition in perfect competition in labour market?
MRL = w
What is real wage?
w/P = MPL - Real wage means how much output your wage can buy, whereas marginal productivity means how much extra output your labour produces.
Real wage in PC
In PC, real wage = marginal productivity of labour. The wage a worker earns can buy exactly as much output as an additional unit of their labour produces. A direct result of MRL = w.
MRL and MPL in PC
MRL = MPL x P

MPL and MRL in general
MPL x MR = MRL
MRL and w in monopsony
MRL > w
in a pc product market - real wage in monopsony
w/P < MPL
because MRL > w => P x MPL > w : the real wage is below labour productivity. It means an extra hour of work produces more output than the worker’s hourly wage can buy. The employer pays you less than the value of the extra output your labour produces.
Inter-temporal choice
Means deciding how much to consume today versus in the future. Borrowing and saving let you move spending between these periods.
Borrower
If in t_0: P0C0 > m0 is a borrower because you spend more than today’s income, so you borrow the difference and repay it in the future.
Saver
If in t_0: P0C0 < m0 is a saver because you spend less than today’s income, so you save the difference for future consumption.
What does an inter-temporal choice depend on?
Preferences (patience): a more patient person is more willing to postpone consumption and save.
Income now and in the future: if you expect higher income later, you may borrow to consume more today.
Prices and inflation: rising prices reduce how much your future money can buy.
Interest rates: saving earns interest, allowing more future consumption; borrowing requires repayment with interest, making consumption today more costly.
Saving moves purchasing power into the future; borrowing brings future purchasing power into the present.
Principal
The original amount saved or borrowed. If you save €100, the principal is €100.
Interest
The extra money earned on savings or paid for borrowing. At 10% interest, €100 earns €10 over one period.
Interest rate
(interest/principal) x 100 - interest as a proportion of the principal

Future value of x_0

What today’s money becomes after earning interest. x_0 + ix_0 = x_0 (1+i)
How much x_0 is worth in future terms
Present discounted value - PDV
How much you need today to obtain a given amount in the future:
x_1 /(1+i) So €110 next year is worth €100 today, because saving €100 today would give you €110 next year.
Stream of income in today’s money vs future money
in t_0 = 800 + 1100/(1+0.1) = 800 + 1000 = 1800 (if we borrow all of tomorrow into today)
in t_1 = 0
if we leave all of today for tomorrow
in t_0 = 0
in t_1 = 800 (1+0.1) + 1100 = 1980

stream of income calculations variables
t_0 : today
t_1 : tomorrow
C_0 : consumption of good in t_0
C_1 : consumption of good in t_1
P_0 : price of c_0
P_1 : price of c_1M
M_0 : income in t_0
M_1 : income in t_1
i : interest rate

Preferences between consumption today v tomorrow
Cobb-Douglas: U(C_0, C_1) = C_0^a C_1^b
Stone-Geary: U(C_0, C_1) = (C_0 + sigma)^a (C_1 + sigma) ^b
Indifference curve - inter-temporal choices
C_0: consumption today.
C_1: consumption next period.
Each curve connects combinations of C_0 and C_1 that give someone the same satisfaction.
They slope downward because if you consume less today, you need more future consumption to remain equally satisfied. If you consume less tomorrow, you need to consume more today to remain equally satisfied.
Steeper curves: a less patient person, who needs a lot of extra future consumption to give up consumption today.
Flatter curves: a more patient person, more willing to wait.

MRS in inter-temporal choices
The MRS in inter-temporal choice is how much future consumption C_1 you are willing to give up for one extra unit of consumption today C_0, while keeping the same satisfaction. How much y you are willing to give up for one more unit of x.
MRS = MUC_0/MUC_1
It is the absolute slope of your indifference curve: MRS = a/b y/x

MRS and patience
At the same consumption bundle:
Higher MRS → steeper curve → less patient.
Lower MRS → flatter curve → more patient.
At an interior optimum, with constant prices:
MRS=1+i
Why does MRS decrease?
Moving right along an indifference curve means more consumption today C_0 and less consumption in the future C_1. When you have little today and plenty tomorrow, you are willing to sacrifice a lot of future consumption for one extra unit today. As you consume more today and have less left tomorrow, future consumption becomes more precious, so you are willing to sacrifice less of it. Your willingness to give up future consumption for one extra unit today, this is diminishing MRS.
Why does MRS = 1+i?
It is because at an interior optimum, MRS = Px/Py. IfWith constant prices, one extra unit consumed today costs 1+i units of future consumption:
If you use savings, you give up the principal plus the interest it would earn.
If you borrow, you must repay the principal plus interest.
If MRS>1+i, consuming more today is worthwhile. If MRS<1+i, shifting consumption towards the future is worthwhile.
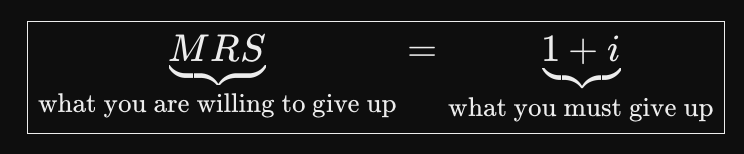
MRS = price ratio at interior optimum
MRS = 1+i
Price tomorrow is how much you need to save today for it to grow into price today tomorrow. So if today it costs 1 euro, we need to save an amount that with interest becomes 1 euro tomorrow which is less than how much it costs today. If interest is 0.1, we save 1/1.1 = 0.91 today, that will become 0.91 × 1.1 = 1 tomorrow.

Consumption smoothing
Means trying to avoid large differences in consumption across time. For example, someone receiving little income today and lots tomorrow might borrow today and repay tomorrow to make consumption more even. Aka spending around the same each day on each good. It does not necessarily mean C_0=C_1: the preferred balance also depends on patience and interest rates.

More consumption today, more consumption in the future, equal consumption today and in the future
Above the line (blue): C_1>C_0 → more consumption in the future.
Below the line (red): C_0>C_1 → more consumption today.
On the line: equal consumption in both periods.

Inter-temporal budget line
The combinations of consumption today and tomorrow you can afford.
Today, t_0: If P0C0 < M0, you have saved what you have not spent, S = M0-P0C0
Future, t_1: You start with M_1 + S(1+i), your income today plus what what you saved yesterday is worth today due to interest.
Amount you can spend in t_1: P_1C_1 = M_1 + S(1+i) = (M0-P0C0)(1+i) + M_1 = M0(1+i) - P0C0(1+i) + M_1

Inter-temporal budget line in terms of stream of expenditures and stream of incomes
Stream of expenditures: P0C0 (1+i) + P1C1
Stream of incomes: M_0 (1+i) + M_1

PDV (present discounted value) of inter-temporal budget line (expressing everything in today’s money by dividing by 1+i)
P0C0 + (P1C1)/(1+i) = M0 + M1/(1+i)
PDV inter temporal budget line graph
X-intercept, is when consumption tomorrow C_1 = 0, P0C0 = M_0 + M_1/(1+i)
C_0 = M_0/P_0 + M_1/(1+i)P_0
Y-intercept, is when consumption today C_0 = 0, P_1 C_1 /(1+i) = M_0 + M_1/(1+i)
C_1 = M_0 (1+i)/P_1 + M_1/P_1
Slope: -a/b = -P0/((P1C1)/(1+i)) = - P0 (1+i) / (P1C1)

Endowment point
In A, C_0 = M0/P0, C_1 = M1/P1. Here you consume each period’s income in that period, no borrowing or saving. Above and left of A, You are spending more on C_1 than you have money for, so you consume less today (save). Savings earn interest, allowing more future consumption.
Below and right of A, you are spending more on C_0 than today’s in come allows, so you consume more today (borrow). Repayment reduces future consumption.

Steepness of indifference curve, patience, and probability of borrowing
If you have a steeper curve, that means you have less patience, as you are willing to give up more C_1 for C_0, aka you prefer consumption today, therefore you have a higher probability of borrowing.
Flatter indifference curve, patience, and saving
If you have a flatter curve, that means you have more patience, as you are willing to give up less C_1 for C_0, aka you prefer consumption in the future, therefore you have a higher probability of saving.
What happens when we consider changes in price in inter-temporal choices on price ratio?
Price ratio = P_0/(P_1/(1+i)) = (1+i)P_0/P_1

General choice for inter-temporal choices
MRS = P_0(1+i)/P_1
Together with the budget equation P0C0 + (P1C1)/(1+i) = M_0 + M1/(1+i)

If MRS < (1+i)P0/P1 aka below endowment point
If MRS < (1+i)P0/P1
MRS measures how much future consumption you would give up for 1 extra unit today. The price ratio tells you how much you actually have to give up. You want to give up less than you actually give up. You think 1 unit today is worth only 1 unit tomorrow. But getting that extra unit today would cost you 1.1 units tomorrow. That sacrifice is too large for you. Therefore, cost exceeds willingness, hence you give up less of C1, increasing consumption of C1 and decrease C0. As MRS = aC1/bC0, so this increases MRS, so MRS = price ratio.
MRS vs Price ratio
MRS is my willingness to give up c1 for c0, and price ratio is the actual cost of gibing up c1 for c0.
MRS > (1+i)P0/P1 aka below endowment point
Willingness exceeds cost, hence you give up more of C1, decreasing consumption of C1 and increasing C0. As MRS = aC1/bC0, so this decreases MRS, so MRS = price ratio.. Giving up C1 and buying more C0 is worth more to you than it is worth to the market, so you consider it a cheap / good trade-off.
Does making MRS = price ratio increase utility?
Yes, moving towards MRS= price ratio along your budget line increases utility, until you reach your best affordable choice.
MRS > price ratio: increase C_0, reduce C_1.
MRS < price ratio: reduce C_0, increase C_1.
At equality, neither small adjustment makes you better off. With the usual convex preferences and an interior solution, this is where utility is maximised.
Why do we borrow or save?
tT increase utility. We borrow or save to shift consumption between today and the future in a way that increases our utility.
Borrow: consume more today and less in the future, aka we have a higher MRS as we are willing to give up more consumption in the future for more consumption today. MRS > price ratio for borrowers.
Save: consume less today and more in the future, aka we have a lower MRS as we are willing to give up less consumption in the future for more consumption today. MRS < price ratio for savers.

How does an increase in interest rate affect inter temporal consumption?
Interest rate rises - the budget line becomes steeper and rotates around the endowment point A, because consuming your income in each period remains affordable.
Slope: -P0(1+i)/Pi
If i increases, slope increases, and the y-intercept increases, while x-intercept decreases.

Why is endowment point constant with changing interest?
The endowment is the income you receive before borrowing or saving. We assume those incomes do not change when the interest rate changes.
How does increasing interest affect an initial borrower?
Borrowing becomes more expensive. The substitution effect reduces C0, and the loss of purchasing power also reduces C0 assuming consumption is normal. Borrowing falls.
How does increasing interest affect an initial saver?
Saving earns more interest. The substitution effect reduces C0 but the increase in purchasing power encourages more C0. The overall effect on saving is ambiguous.
What is the subsitution effect?
It refers to the shifting of consumption towards whichever period becomes relatively cheaper.
Could a saver become a borrower after i rises?
In the standard model, no, they may save more or less but they do not switch to borrowing. Similarly, an initial borrower may become a saver as borrowing falls. For the borrower, borrowing becomes more expensive, encouraging less consumption today. If today’s consumption falls below today’s income, they start saving.
What borrowing means?
Borrowing means someone lends you money today, and you promise to repay it using your future income, plus interest. So the same extra €100 of consumption today costs you more future consumption when interest is higher.
Purchasing power and higher interest
Borrower: purchasing power falls
Svaer: purchasing power rises (tomorrow) as you earn more on savings
