Income Taxes Practice Problems
 Call Kai
 Learn
 Practice Test
 Spaced Repetition
 Match
 Flashcards
 Knowt Play
1/17

There's no tags or description
Looks like no tags are added yet.
18 Terms
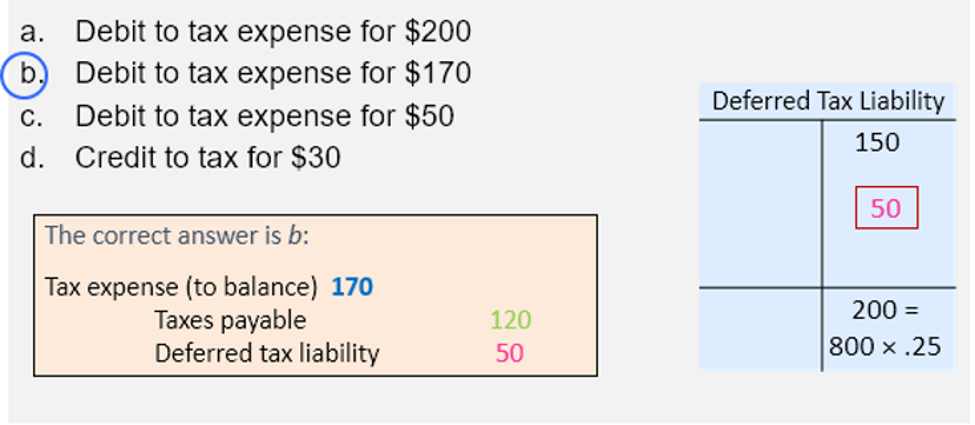
Windsor Company started 2024 with a deferred tax liability balance of $150. As of the end of the period, Windsor identifies future taxable amounts of $800. Windsor has a tax rate of 25% and calculates that taxes payable will be $120. Windsor’s tax expense journal entry will include a:
a. Debit to tax expense for $200
b. Debit to tax expense for $170
c. Debit to tax expense for $50
d. Credit to tax for $30
Shortly before the end of 2024, Colter Company makes an installment sale that generates $400 of before-tax income. Colter recognizes income for accounting purposes when the sale is made but will recognize income for tax purposes when cash is subsequently collected in 2025. Colter has a tax rate of 25%. As a result of this transaction, Colter’s tax expense journal entry would include a:
a. Debit to deferred tax liability for $400
b. Credit to deferred tax liability for $400
c. Debit to deferred tax liability for $100
d. Credit to deferred tax liability for $100

An installment sale is a DTL
Hardy Welders Inc. had purchased a machine at the beginning of year 1 for $2,000,000. The machine has a useful life of 10 years and a book value of $1,800,000 at the beginning of year 2. Hardy depreciates the machine on a straight-line basis for financial reporting purposes but fully depreciates it on the date of purchase for tax purposes. Hardy pays taxes at a rate of 25%. Hardy’s year 2 balance sheet should include a deferred tax liability of:
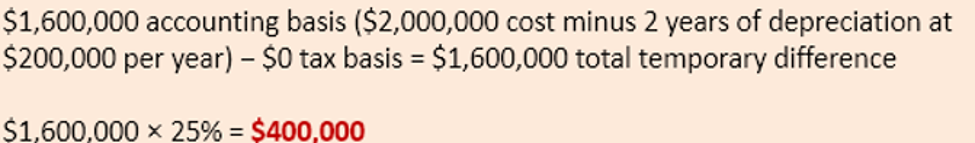
Management previously recorded a DTA of $8 million. However, due to declining income in some tax districts, management determines in 2024 that it’s more likely than not that $3 million of the DTA ultimately will not be realized in future years. Prepare the journal entry to adjust Deferred Tax Asset.
At the end of the following year, 2025, available evidence now indicates that only $500,000 of the deferred tax asset ultimately will not be realized. Prepare the journal entry to adjust Deferred Tax Asset.

As of the end of 2024, Elliott had a deferred tax asset of $100,000 and believed it was not more likely than not that it could realize any of the tax deductions associated with the deferred tax asset.
As of the end of 2025, Elliott needed to show a deferred tax asset of $150,000, and believed it was more likely than not that it would realize $20,000 of that deferred tax asset. Assuming tax payable of $300,000 and no deferred tax liabilities, Elliott’s 2025 tax expense journal entry includes a:
a. Debit to tax expense for $330,000
b. Debit to tax expense for $280,000
c. Debit to tax expense for $250,000
d. Credit to tax expense for $230,000

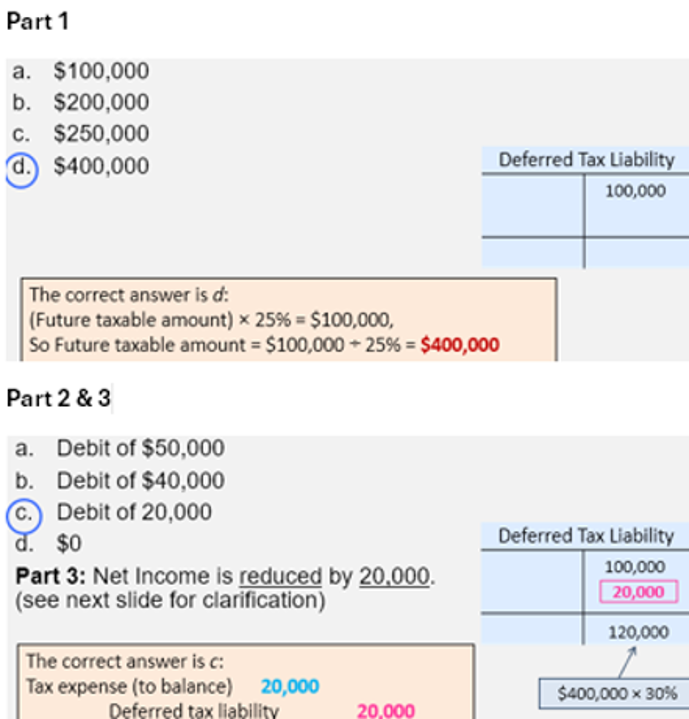
Dutch Bakers has a $100,000 deferred tax liability that will create taxable income in 2026. Dutch established the deferred tax liability in 2023 when the tax rate was 25%. In 2024, the tax rate enacted for 2026 was increased to 30%
Part 1: What is the amount of future taxable income that Dutch will incur in 2026 associated with the deferred tax liability?
a. $100,000
b. $200,000
c. $250,000
d. $400,000
Part 2: In 2024, the year the tax rate change for 2026 is enacted, the effect of the change on tax expense will be a:
a. Credit of $20,000
b. Debit of $40,000
c. Debit of 20,000
d. $0
Part 3: Net income is _____ (+ / -) by ______.
Company A reports a net operating loss in 2026. Their taxable income is 4 million and the tax rate is 25%. What is the maximum of the NOL they can carry forward as a DTA to reduce future taxes?
a. $4 million
b. $3.2 million
c. $1 million
d. $0
B; Companies are limited to offsetting a maximum of 80% of taxable income with NOL carryforwards in any given year.
4 × 80% = $3.2 million
Plaxco had a before-tax loss of $100,000 for both financial accounting and tax purposes in 2024, and pays tax at a rate of 25%. As a result Plaxco will have:
a.A 2024 net loss of $100,000 and a deferred tax asset of $100,000
b.A 2024 net loss of $100,000 and a deferred tax asset of $25,000
c.A 2024 net loss of $25,000 and a deferred tax asset of $75,000
d.A 2024 net loss of $75,000 and a deferred tax asset of $25,000
Prepare the journal entry to create the DTA.

Does it create a DTA or DTL?
Warranty expense
DTA
Is it a DTA or DTL?
Revenue collected in advance
DTA
Is it a DTA or a DTL?
Unrealized gain from recording investments at fair value
DTL
Accounting income is $75,000. Tax MACRS is $10,000 more than Income Statement SL depreciation. What is taxable income?
75-10= $65,000
For exam purposes, MACRS will always be higher than SL.
Accounting income is $75,000. Warranty expense is $7,000. What is taxable income? Is it a DTA or DTL?
75,000+7,000 = $82,000 taxable income
$82,000 taxable income > $75,000 Acct income
DTA
Valuation allowance shows how much of the DTA balance:
a. Will be realized
b. Won't be realized
B; Won't be be realized
Is it a DTA or a DTL?
Estimated expenses and losses
DTA
Is it a DTA or a DTL?
Prepaid expenses (tax deductible when paid)
DTL
Is it a DTA or a DTL?
Installment sales of property
DTL
Is it a DTA or a DTL?
Unrealized loss from recording investments at fair value
DTA