ACC210 - Chapter 4 - Bank Reconciliations
 Call Kai
 Learn
 Practice Test
 Spaced Repetition
 Match
 Flashcards
 Knowt Play
1/21

There's no tags or description
Looks like no tags are added yet.
22 Terms
Identify the control features of a bank account
The use of a bank contributes significantly to good internal control over cash
Minimize the amount of currency on hand
Creates a double record of bank transactions
Bank reconciliation

Bank reconciliation
The balance of cash in the company’s records may not equal the balance of cash in the bank’s records
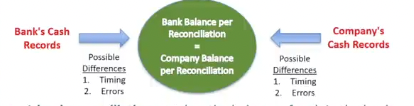
A bank reconciliation: matches the balance of cash in the bank with the balance of cash in the company’s own records
Timing differences: in cash occur when the company records transactions before or after the bank records the same transactions
Errors: can be made either by the company or its bank and may be accidental or intentional
Which of the following would be an adjustment to the Cash General Ledger account (per books) balance?
Checks outstanding
Company errors
Deposits in transit
Bank errors
Company errors —> Any errors we have made in our company records will need to be adjusted from our own Cash General Ledger account balance.
Company Records of Cash Activities

Bank statement

Non-Sufficient Fund (NSF)
Occurs when a payment has been declined, usually caused by a low balance
Reconciling the bank account
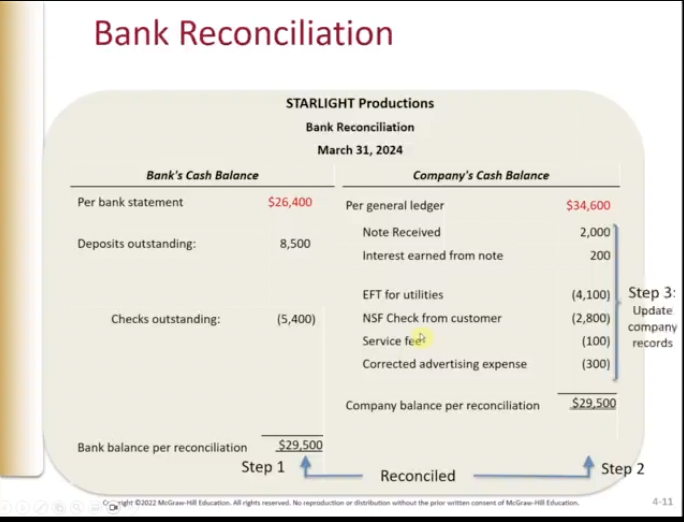
Reconciling the bank account involves three steps:
Reconcile the bank’s cash balance
Reconcile the company’s cash balance
Update the company’s cash account by recording items identified in step 2
When the bank debits my bank account:
They are reducing my balance
Step 1: reconcile the banks cash balance
Cash transactions recorded by the company but not yet recorded by its bank:
Deposits outstanding: cash receipts of the company that have not been added to the bank’s record of the company’s balance
Checks outstanding: checks the company has written that have not been subtracted from the bank’s record of the company’s balance
Bank errors
Step 2: Reconcile the company’s cash balance

Step 3: Update the company’s cash account

Differences in Cash Collections

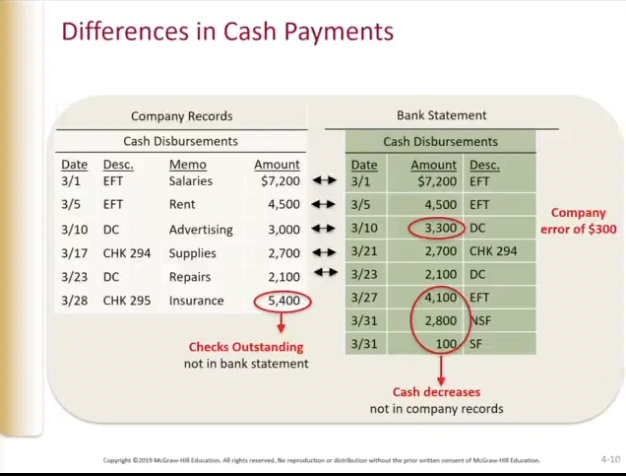
Differences in Cash Payments
Which of the following items would cause the balance of cash in the bank statement to be greater than the balance of cash in the accounting records? Assume that no errors have been made by the company or the bank.
The company wrote checks that have not cleared the bank.
The company purchased supplies using a debit card.
The company has cash receipts that have not been deposited in the bank.
The company deposited a customer check that was found by the bank to have insufficient funds.
The company wrote checks that have not cleared the bank.
Explanation:
Outstanding checks decrease the balance recorded in the company's accounting records (books) when written, but have not yet been deducted by the bank. This causes the bank statement balance to be greater than the book balance.
Deposits in transit (cash receipts not yet deposited) would make the book balance greater than the bank balance.
NSF checks (insufficient funds) reduce the book balance once discovered, but when initially processed, they cause the bank balance to drop relative to the books.
Debit card purchases reduce both bank and book balances immediately/simultaneously.
Bank Reconciliation
Information about a company's Cash G/L account balance and bank reconciliation as of 8/31:
Company cash account balance before reconciliation $5,000
Checks outstanding $2,500
Notes collected by the bank 1,200</span></p><p><span>Servicefee 50
Deposits in transit $2,000
What is the correct cash balance? That is, what amount should the company report on their Balance Sheet on 8/31?
$6150
5000+1200-50=6150
Journal entries are required for all adjustments to the:
Books balance
Summary of Reconciliation Procedures

Bank Reconciliation (Ex 1)
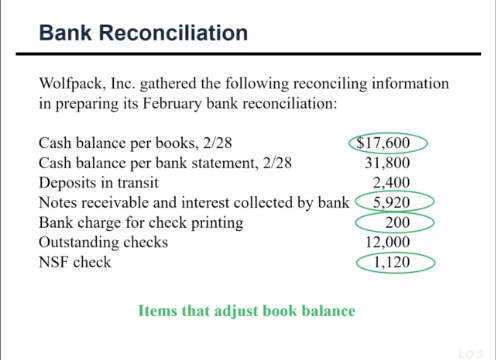
The correct cash balance as of February 28 for Wolfpack, Inc. is $22,200
From the Bank Statement Balance:
Cash balance per bank statement: $31,800
Add: Deposits in transit: +$2,400
Less: Outstanding checks: -$12,000
Correct Cash Balance: $22,200
From the Books Balance (Verification):
Cash balance per books: $17,600
Add: Notes receivable & interest collected: +$5,920
Less: Bank charge for check printing: -$200
Less: NSF check: -$1,120
Correct Cash Balance: $22,200

Bank Reconciliation (Ex 1 Journal Entries)

Items that adjust the bank balance

Items that adjust the book balance