ACTG
 Call Kai
 Learn
 Practice Test
 Spaced Repetition
 Match
 Flashcards
 Knowt Play
1/116

There's no tags or description
Looks like no tags are added yet.
Name | Mastery | Learn | Test | Matching | Spaced | Call with Kai | Chat |
|---|
No analytics yet
Send a link to your students to track their progress
117 Terms
Financial Accounting
Keeping the financial score for the entity
Follows GAAP
External
Managerial Accounting
Using accounting and non-accounting information to make decisions
Conventions (No GAAP)
Internal
FASB
Financial Accounting Standards Board
GAAP
Generally Accepted Accounting Principles
Financial Accounting
keeping the financial score for the entity
Cost
all costs are historical
Objectivity
arm’s length negotiation
Going Concern
company will be around long enough to use up assets and pay all liabilities
Revenue Recognition
Earned: rendered goods and services
Recognized: expectation of payment
Matching
match expenses with revenue in the period they occur
Consistency
follow the same procedures each accounting period so can compare financial statements
Conservatism
if multiple options exist, pick the least favorable
Materiality
if you knew the fact, it could change your mind; 5% of something
Full Disclosure
“Full Monty” must disclose all relevant information
Assets
something of future economic value
Are all assets shown on the balance sheet? If not, why not?
No. Assets must be objectively quantifiable to be recorded on the balance sheet
Liability
something owed
Are all liabilities shown on the balance sheet? If not, why not?
No. Liabilities must be objectively quantifiable to be recorded on the balance sheet.
Contingent liability
liability that cannot be objectively quantifiable.
Stockholder’s Equity
capital plus retained earnings
Capital
investment by the stockholders
Retained Earnings
Earnings retained in the business
Ending RE = Beginning RE plus NIAT minus Dividends
Dividend
distribution of retained earnings to stockholders
Expense
expired asset
Revenue
rendered goods and/or services with the expectation of payment
Chart of Accounts
list of the names and account numbers for all accounts
General Journal
shows the debits and credits for each accounting transaction
General Ledger
list of all transactions for the accounting period sorted by account number
Debit
entry on the left side of a general ledger account
Credit
entry on the right side of a general ledger account
Trial Balance
list of all accounts showing that the total debits equal the total credits
Adjusting Entry
reconciles a general ledger account to a backup schedule
Closing Entries
at end of period, all revenue and expense accounts closed to Retained Earnings
Reversing Entries
reversing an accrual entry from a previous period
Contra account
account used to keep the balance in another account visible
“Close” or “Close the books”
At the end of the period, close (move) all the revenue and expense account balances on the income statement to retained earnings; resets the income statement to zero to begin
the next period.
Accrual Basis vs. Cash Basis:
Accrual basis: accounting based on transactions
Cash basis: accounting based on cash in/cash out (i.e. Real World)
Debit l Credit

Controller
typically, the top accounting person in a company
Income Statement
matches revenue with expense over a period of time
Cost of goods sold
Def: cost of what is not there
formula: beginning inventory plus net purchases minus ending inventory
Non-cash charges
Def: deduction on income statement but no cash paid out
Ex: depreciation, amortization, depletion, gain or loss on asset sale
Gross Profit
= Net Revenue - cost of goods sold
SG&A
Selling, general, and administrative expense (aka operating expenses)
Operating income
= Gross profit minus S, G & A; income from the core business
Non-Operating Income (aka “other”)
interest income and expense, capital gain or loss
Balance Sheet:
shows assets equals liabilities plus stockholders’ equity at a point in time
Current
within 12 months or one operating cycle
Current assets
assets that will be used up or converted to cash within one year
Current liabilities
liabilities which are due within one year
Statement of Changes in Cash Position
difference between two balance sheets expressed in cash
Capitalize It
Put the amount on the balance sheet; generally, as an asset to be depreciated or amortized (Increases net income)
Expense It” = “Write It Off”
Deduct the amount on the income statement (Decreases net income)
why capitalize/expense/write it off important?
Want net income to be correct.
Fixed (plant) assets (aka PPE—property, plant, and equipment)
Assets with an estimated useful life of more than one year
Goodwill
amount paid above the identifiable assets in a transaction
Long term liabilities:
liabilities due beyond more than one year
Book value of an asset
original cost minus accumulated depreciation
Found on the balance sheet in assets
Market value of an asset
value paid by a willing buyer and willing seller
Not found on the financial statements
Book value of a company
common stockholders’ equity
Found on the balance sheet under stockholder’s equity
Market value of a company
value paid by a willing buyer and willing seller
Not found on the financial statements
Sales vs. revenue
there is no difference
Accrued
estimated
Gross revenue vs. net revenue (which is more important and why?)

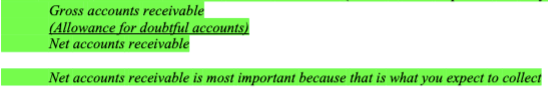
Gross accounts receivables versus net account receivables (which is more important and why?)
Net Income
revenue - expense
Expense
expired asset
Prepaid expense
paid cash but have not yet received the goods and services
Unearned revenue (aka customer deposits)
received cash but have not yet rendered the goods and services
Depreciation, Amortization, and Depletion
Definition – method of cost allocation of long-term assets over the estimated useful life under the Matching Principle (does NOT represent wear and tear or loss of value)
Depreciation
allocation of original costs over the estimated useful life of a tangible asset
Amortization
allocation of original costs over the estimated useful life of an intangible asset
Depletion
allocation of original costs over the estimated useful life of a natural resource asset
Depreciation, amortization or depletion versus accumulated depreciation, accumulated amortization, or accumulated depletion
expense for the period (expense on I/S) versus sum of the expense across all periods since the asset was placed in service (contra asset account on the B/S).
Six Elements of Internal Control
Establishment of responsibility – “who” is responsible
Segregation of duties – for “what” is “who” responsible
Documentation procedures – required paperwork to trace the transaction
Physical Controls – physical barriers
Independent internal verification – check by someone independent of the process
Human resource control – hiring people with the appropriate skills
Check and balance
organizing work so people naturally check on each other
Straight Line Depreciation
Def: Allocation of original cost evenly over the estimated life of the asset
on the income statement
follows GAAP
Purpose: matching, match expense with revenue
limit: total depreciation over the life of the asset per books and per tax will be the same
Accelerated Depreciation
Def: Any depreciation method faster than straight line
Used: Tax Return
Follows IRS
Accelerate depreciation expense per tax to reduce taxable income to incent business to purchase capital assets and thereby expand employment
limit: total depreciation over the life of the asset per books and per tax will be the same
Calendar year
accounting year ends December 31
Fiscal year
accounting years ends on any other month
Periodic inventory
every so often, i.e. daily, weekly, monthly, quarterly, annually
Perpetual inventory
every transaction (i.e. scanner)
Other Income and Expense (Non-operating portion of the income statement)
Interest income and interest expense
Gain or loss on the sale of assets
Normal assumption
buyer pays freight
FOB
“Free on Board”
point at which title transfers: FOB Plant, FOB destination
not to be confused with who ultimately pays the shipping cost
Freight In
part of inventory which is a current asset on B/S
cost of getting materials to the plant or warehouse
Freight Out
part of SG&A – sales/marketing expense of getting product to the customer; deduction from gross profit on I/S
Bad debt expense
the net (squeeze)adjustment to the ADA account; part of S,G &A on the income statement
ADA
the estimate of accounts that are uncollectible; contra account to A/R in current assets
“Bad debts go to the ADA to die”
Direct Write Off – bad debts go directly to I/S since there is no ADA history.
JIT – Just in time inventory
Delivery of inventory just as it is required for production
FIFO First-In-First-Out flow of goods sold
=> LISH – Last-In-Still-Here inventory valuation
FIFO First-In-First-Out flow of goods sold =>
LISH – Last-In-Still-Here inventory valuation
Fifo
first in first out
Lish
last in still here
Value Chain
all the processes and procedures which add value to product or service in the customers eyes
Supply Chain
all the activities to get the product made and in the hands of the customer.
Tax Expense
expense to company
appears on income statement
income tax, employer payroll taxes, sales tax paid by company on its purchases
Tax Pass Through
taxes collected on behalf of a governmental entity and passed through to the entity
neither a revenue nor an expense
may appear on balance sheet as liability if not yet paid
examples: sales taxes, excise taxes, employee payroll taxes
“C level”
the executive level of a company e.g. chief executive officer, chief financial officer, chief…
What is the purpose of a entity?
To satisfy a customer demand