MGT 109 Lec 11
 Call Kai
 Learn
 Practice Test
 Spaced Repetition
 Match
 Flashcards
 Knowt Play
1/12

There's no tags or description
Looks like no tags are added yet.
13 Terms
Perfect Competition
• Firms are price-takers
• Each produces only a very small portion
of total market or industry output
• All firms produce a homogeneous
product
• Entry into & exit from the market is
unrestricted
Demand for a Competitive Price-Taker
• Demand curve is horizontal at price determined by intersection of market demand & supply
• Perfectly elastic
• Can sell all they want at the market price
• Each additional unit of sales adds to total
revenue an amount equal to price
Marginal revenue equals price
• Demand curve is also marginal revenue curve
(D = MR = P)
shut down
If price is less than average variable
cost (P AVC), manager will _______
• Produce zero output
• Lose only total fixed costs
produce
Firm’s manager will ____ output where P = MC as long as:
• TR > TVC
• or, equivalently, P > AVC
Irrelevant
• Fixed costs are _______ in the production decision i.e. if you will be producing
• Level of fixed cost has no effect on marginal cost or minimum average variable cost
• Thus no effect on the optimal level of output
False
Fixed costs isn’t considered when shutting down
AVC
tells whether to produce
Shut down if price falls below minimum
SMC
tells how much to produce
If P > minimum AVC, produce output
where P =
ATC
(which includes total fixed cost) tells how much profit/loss if you produce
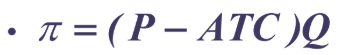
Long-Run Competitive Equilibrium
All firms are in profit-maximizing equilibrium (P = LMC)
Occurs because of entry/exit of firms in/out of industry
• Market adjusts so P = LMC = LAC
produce
If P > AVCmin then
shutdown
If P < AVCmin then