stocks exam 4
 Call Kai
 Learn
 Practice Test
 Spaced Repetition
 Match
 Flashcards
 Knowt Play
1/37

There's no tags or description
Looks like no tags are added yet.
38 Terms
Fama and French claim that after controlling for firm size and the ratio of firm's book value to
market value, beta is ______________.
I. highly significant in predicting future stock returns
II. relatively useless in predicting future stock returns
III. a good predictor of firm's specific risk
II only
In a simple CAPM world which of the following statements is/are correct?
I. All investors will choose to hold the market portfolio, which includes all risky assets in the world
II. Investors' complete portfolio will vary depending on their risk aversion
III. The return per unit of systematic risk will be identical for all individual assets
IV. The market portfolio will be on the efficient frontier and it will be the optimal risky portfolio
I, II, III and IV
In the context of the capital asset pricing model, the systematic measure of risk is captured by
_________.
beta
If enough investors decide to purchase stocks they are likely to drive up stock prices thereby causing
_____________ and ___________.
expected returns to fall; risk premiums to fall
If all investors become more risk averse the SML will _______________ and stock prices will
_______________.
have the same intercept with a steeper slope; fall
Investors require a risk premium as compensation for bearing ______________.
systematic risk
According to the capital asset pricing model, a fairly priced security will plot _________.
along the security market line
The beta of a security is equal to _________.
the covariance between the security and market returns divided by the variance of the market's
returns
According to the CAPM which of the following is not a true statement regarding the market portfolio.
It is always the minimum variance portfolio on the efficient frontier
In a world where the CAPM holds which one of the following is not a true statement regarding the
capital market line?
The capital market line is also called the security market line
According to the CAPM, the risk premium an investor expects to receive on any stock or
portfolio is _______________.
directly related to the beta of the stock
Which of the following variables do Fama and French claim do a better job explaining stock returns than beta?
I and III only
The SML is valid for _______________ and the CML is valid for ______________
both well diversified portfolios and individual assets; well diversified portfolios only
According to the CAPM, investors are compensated for all but which of the following?
Residual risk
The measure of unsystematic risk can be found from an index model as _________.
residual standard deviation
Standard deviation of portfolio returns is a measure of ___________.
total risk
A stock has a beta of 1.3. The unsystematic risk of this stock is ____________ the stock market as a whole
higher than
In a CAPM world, an investor's degree of risk aversion will determine his or her ______.
optimal mix of the risk-free asset and the market portfolio
Consider the CAPM. The risk-free rate is 6% and the expected return on the market is 18%. What is the expected return on a stock with a beta of 1.3
21.6%
Consider the CAPM. The risk-free rate is 5% and the expected return on the market is 15%.
What is the beta on a stock with an expected return of 17%?
1.2
Consider the CAPM. The expected return on the market is 18%. The expected return on a
stock with a beta of 1.2 is 20%. What is the risk-free rate?
8%
You have a $50,000 portfolio consisting of Intel, GE and Con Edison. You put $20,000 in Intel, $12,000 in GE and the rest in Con Edison. Intel, GE and Con Edison have betas of 1.3, 1.0 and 0.8 respectively.
What is your portfolio beta?
1.048
Security X has an expected rate of return of 13% and a beta of 1.15. The risk-free rate is 5% and the
market expected rate of return is 15%. According to the capital asset pricing model, security X is
overpriced
You invest $600 in security A with a beta of 1.5 and $400 in security B with a beta of .90. The beta of
this portfolio is _________.
1.26
Security A has an expected rate of return of 12% and a beta of 1.10. The market expected rate of
return is 8% and the risk-free rate is 5%. The alpha of the stock is _________.
3.7%
The risk-free rate is 4%. The expected market rate of return is 11%. If you expect stock X with a beta of .8 to offer a rate of return of 12 percent, then you should _________
buy stock X because it is underpriced
Consider the following two stocks, A and B. Stock A has an expected return of 10% and a beta of 1.20.
Stock B has an expected return of 14% and a beta of 1.80. The expected market rate of return is 9% and
the risk-free rate is 5%. Security __________ would be considered a good buy because _________.
B, it offers an expected excess return of 1.8%
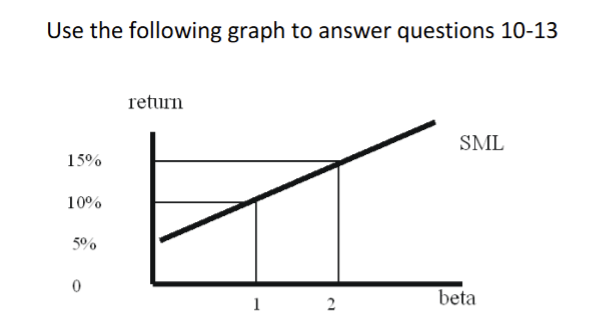
What is the expected return on the market?
10%

What is the beta for a portfolio with an expected return of 12.5%?
1.5

What is the expected return for a portfolio with a beta of 0.5?
7.5%

What is the alpha of a portfolio with a beta of 2 and actual return of 15%?
0%

If the simple CAPM is valid and all portfolios are priced correctly, which of the situations
below are possible? Consider each situation independently and assume the risk free rate is 5%
Opiton D
Two investment advisors are comparing performance. Advisor A averaged a 20% return with
a portfolio beta of 1.5 and Advisor B averaged a 15% return with a portfolio beta of 1.2. If the T-
bill rate was 5% and the market return during the period was 13%, which advisor was the better
stock picker?
Advisor A was better because he generated a larger alpha
You consider buying a share of stock at a price of $25. The stock is expected to pay a
dividend of $1.50 next year and your advisory service tells you that you can expect to sell the
stock in one year for $28. The stock's beta is 1.1, rf is 6% and E[rm] = 16%. What is the stock's
abnormal return?
1%
According to the CAPM, what is the market risk premium given an expected return on a
security of 13.6%, a stock beta of 1.2, and a risk free interest rate of 4.0%?
8.0%
Research has identified two systematic factors that affect U.S. stock returns. The factors are
growth in industrial production and changes in long term interest rates. Industrial production
growth is expected to be 3% and long term interest rates are expected to increase by 1%. You are analyzing a stock that has a beta of 1.2 on the industrial production factor and 0.5 on the interest rate factor. It currently has an expected return of 12%. However, if industrial production actually grows 5% and interest rates drop 2% what is your best guess of the stock's return?
12.9%
The risk premium for exposure to aluminum commodity prices is 4% and the firm has a beta
relative to aluminum commodity prices of 0.6. The risk premium for exposure to GDP changes is
6% and the firm has a beta relative to GDP of 1.2. If the risk free rate is 4.0%, what is the
expected return on this stock?
13.6%
The risk premium for exposure to exchange rates is 5% and the firm has a beta relative to
exchanges rates of 0.4. The risk premium for exposure to the consumer price index is -6% and
the firm has a beta relative to the CPI of 0.8. If the risk free rate is 3.0%, what is the expected
return on this stock?
0.2%