Economics: Micro and Macro Principles, Demand, Supply, and Market Equilibrium
 Call Kai
 Learn
 Practice Test
 Spaced Repetition
 Match
 Flashcards
 Knowt Play
1/102

There's no tags or description
Looks like no tags are added yet.
Name | Mastery | Learn | Test | Matching | Spaced | Call with Kai | Chat |
|---|
No analytics yet
Send a link to your students to track their progress
103 Terms
What is the primary focus of economics?
Economics studies how people use scarce resources, respond to incentives, and make decisions.
Define scarcity in economics.
Scarcity refers to limited time, money, and information.
What are incentives in economics?
Incentives are rewards or penalties that make a choice more or less attractive.
What is microeconomics?
Microeconomics studies how households and firms make choices and interact in markets.
What is macroeconomics?
Macroeconomics examines the economy as a whole, including inflation and economic growth.
What are the three key economic ideas?
1. People interact in markets. 2. People are rational. 3. People respond to incentives.
What is a market in economics?
A market is a group of buyers and sellers of a good or service and the institution by which they trade.
What does it mean for people to be rational in economic terms?
It means they use all available information to make the best possible decision for themselves.
What is an economic incentive?
An economic incentive encourages or discourages a particular behavior.
What is the optimal decision-making principle in economics?
Optimal decisions are made at the margin, comparing marginal benefits to marginal costs.
What are the three fundamental economic questions every society must answer?
1. What should be produced? 2. How should it be produced? 3. Who should receive what is produced?
Define opportunity cost.
Opportunity cost is the value of the next-best alternative given up when making a choice.
What is the circular flow diagram in economics?
The circular flow diagram illustrates the interactions between households and firms in two markets: goods and services, and labor.

What are the three types of economic systems?
1. Traditional economy. 2. Command economy. 3. Market economy.
Describe a traditional economy.
A traditional economy is agricultural, where production methods are based on historical practices.
What characterizes a command economy?
In a command economy, the government makes all economic decisions and owns resources.
What is a market economy?
A market economy is decentralized, where private individuals own resources and businesses supply goods based on demand.
What is demand in economics?
Demand is the amount of a good or service consumers are willing and able to purchase at each price.
What is the relationship between price and demand?
Price is what a buyer pays for a unit of a specific good or service.
What does it mean to make decisions at the margin?
It means evaluating whether the additional benefit of an action outweighs its additional cost.
What is the significance of trade-offs in economics?
Choosing to produce more of one good usually means producing less of another, highlighting the concept of trade-offs.
How do societies decide what goods and services to produce?
Societies make decisions based on resource availability and societal needs.
What methods can be used to distribute goods and services?
Goods can be distributed based on ability to pay, need, waiting lines, or lottery systems.
What is the role of government in a mixed economy?
The government may intervene in economic decisions to a greater extent than in a purely market-oriented economy.
What is the importance of economic models?
Economic models simplify reality to analyze real-world economic situations and rely on assumptions.
What is the concept of marginal benefit?
Marginal benefit is the additional satisfaction or utility gained from consuming one more unit of a good or service.
What is the concept of marginal cost?
Marginal cost is the additional cost incurred from producing one more unit of a good or service.
What does it mean when MB > MC?
It indicates that the next unit of production is worth pursuing because the marginal benefit exceeds the marginal cost.
What is quantity demanded?
The total number of units of a good or service consumers would purchase at a specific price.
What does the law of demand state?
If price goes up, then quantity demanded goes down; if price goes down, then quantity demanded goes up.
What is a demand schedule?
A table that shows a range of prices for a certain good or service and the quantity demanded at each price.
What is a demand curve?
A graphic representation of the relationship between price and quantity demanded of a certain good or service.
What does it mean when demand shifts to the right?
It indicates an increase in demand, meaning that at every given price, the quantity demanded is higher.

What does it mean when demand shifts to the left?
It indicates a decrease in demand, meaning that at every given price, the quantity demanded is lower.
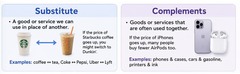
What is the substitution effect?
When the price of a product falls, consumers may substitute it for a more expensive alternative, increasing the quantity demanded.
What is the income effect?
When the price of a product falls, consumers have more purchasing power, allowing them to buy more of that product.
What does ceteris paribus mean?
It means 'all else equal' and is used to assume that other factors remain unchanged when analyzing demand or supply.
What factors can shift the demand curve?
Income, prices of related goods, tastes, population and demographics, expected future prices, natural disasters, and pandemics.
What is quantity supplied?
The total number of units of a good or service producers are willing to sell at a given price.
What does the law of supply state?
If price goes up, then quantity supplied goes up; if price goes down, then quantity supplied goes down.
What is a supply schedule?
A table that shows the quantity supplied at a range of different prices.
What is a supply curve?
A graphic illustration of the relationship between price and quantity supplied.
What does it mean when supply shifts to the right?
It indicates an increase in supply, meaning that at every given price, the quantity supplied is higher.
What does it mean when supply shifts to the left?
It indicates a decrease in supply, meaning that at every given price, the quantity supplied is lower.
What factors can change the supply of goods?
Technological change, transportation, resources, weather, number of sellers, expected future prices, prices of related goods in production.
What is the difference between supply and quantity supplied?
Quantity supplied refers to a specific point on the curve, while supply refers to the entire curve.
How do natural disasters affect demand?
Natural disasters can cause temporary disruptions to economic activity, potentially decreasing demand.

How do changes in consumer income affect demand?
An increase in income typically increases demand for normal goods and decreases demand for inferior goods.
What happens to demand if consumer preferences change?
If a product becomes more popular, demand increases; if it becomes less popular, demand decreases.
What is the impact of expected future prices on current demand?
An expected increase in future prices can increase current demand, while an expected decrease can decrease current demand.
What is the relationship between price and quantity demanded?
There is an inverse relationship; as price decreases, quantity demanded increases, and vice versa.
What is the role of demographics in shifting demand?
Changes in population characteristics, such as age and gender, can affect the demand for certain goods and services.
What is the effect of an increase in the price of related goods?
An increase in the price of a substitute good can increase demand for the original good, while an increase in the price of a complement can decrease demand.
What are inputs in production?
Inputs are anything used in the production of a good or service.
How does an increase in the price of an input affect supply?
It raises the cost of production, causing a decrease in supply.
What is technological change in production?
A change in a firm's ability to produce a given level of output with a given quantity of inputs.
What happens to supply when a new, more efficient production method is introduced?
Supply increases, shifting the supply curve to the right.

What are substitutes in production?
Goods that can be produced using the same resources, such as corn and soybeans.
What effect does a rise in the price of corn have on the supply of soybeans?
It decreases the supply of soybeans as farmers allocate more land to corn.
What are complements in production?
Goods that are produced together, such as beef and leather.
How does an increase in the price of beef affect the supply of leather?
It increases the supply of leather because more cattle are raised.
What is the relationship between the number of firms in the market and supply?
More firms result in greater supply, while fewer firms decrease supply.
How do natural disasters affect supply?
They disrupt production, leading to a decrease in the supply of goods.
What is market equilibrium?
It is the point where quantity demanded equals quantity supplied.

What is equilibrium price?
The price at which quantity demanded equals quantity supplied.
What is equilibrium quantity?
The quantity at which quantity demanded and quantity supplied are equal.
What happens when there is excess supply?
The quantity supplied is greater than the quantity demanded, leading to a surplus.
What is excess demand?
A situation where quantity demanded is greater than quantity supplied, resulting in a shortage.
What is the four-step process for determining changes in equilibrium price and quantity?
1. Draw the demand and supply model. 2. Identify the change affecting demand or supply. 3. Determine the direction of the shift. 4. Identify the new equilibrium.
What is the difference between movements and shifts in supply and demand?
Movements occur along a curve due to a change in price, while shifts occur when a non-price factor changes.
What is price elasticity of demand?
It measures how responsive quantity demanded is to a change in price.
What does a 10% increase in price indicate in terms of price elasticity of demand?
It shows how much quantity demanded changes, e.g., by 1%, 5%, or 20%.
What is price elasticity of supply?
It measures how responsive quantity supplied is to a change in price.
What does an increase in supply do to equilibrium price?
It typically causes the equilibrium price to fall.
What happens to equilibrium quantity when demand increases?
Equilibrium quantity rises as demand shifts to the right.
What is the effect of a decrease in supply on equilibrium price?
It generally causes the equilibrium price to rise.
What factors can shift the supply curve?
Prices of inputs, technological change, prices of related goods in production, number of firms, expected future prices, natural disasters.
What characterizes inelastic demand?
Elasticity is less than 1, indicating low responsiveness to price changes.
What characterizes elastic demand?
Elasticity is greater than 1, indicating high responsiveness to price changes.
What is unitary elasticity?
Elasticity equals 1, indicating proportional responsiveness of demand or supply.
What happens to demand for insulin when the price rises by 10%?
Demand is inelastic; patients must keep buying it.
What happens to demand for restaurant meals when the price rises by 10%?
Demand is elastic; many people cut back quickly.
What is the midpoint method for calculating elasticity?
It uses the average percent change in both quantity and price.
What is the effect of close substitutes on price elasticity?
Price elasticity is higher when close substitutes are available.
How does the time frame affect price elasticity?
Price elasticity is higher in the long run than in the short run.
What is consumer surplus?
The difference between the highest price a consumer is willing to pay and the actual price paid.
How is producer surplus defined?
The difference between the lowest price a firm would accept and the price it actually receives.
What is a price ceiling?
A maximum legal price that can be charged for a product or service.
What is a price floor?
A minimum legal price that must be paid for a good or service.
When does a price ceiling bind?
When it is set below the market price, causing a shortage.
When does a price floor bind?
When it is set above the market price, causing excess supply.
What is the relationship between total revenue and inelastic demand when price increases?
Total revenue increases when demand is inelastic.
What happens to total surplus when the market is not in equilibrium?
Total surplus decreases, leading to deadweight loss.
What is the formula for calculating total revenue?
Total revenue = Price per unit × Number of units sold.
How does a price increase affect total revenue with elastic demand?
Total revenue decreases when demand is elastic.
What is perfect inelasticity?
A situation where a change in price results in zero change in quantity demanded or supplied.
What is perfect elasticity?
A situation where a change in price results in an infinite change in quantity demanded or supplied.
What is the marginal cost?
The change in a firm's total cost from producing one more unit of a good or service.
What is the consumer surplus for chai tea at $3.50 per cup?
Total consumer surplus is calculated based on individual surpluses above the price paid.
How does a price ceiling affect consumer surplus?
It can increase consumer surplus if the price is set below the equilibrium price.