6.4 Black-Scholes Formula
 Call Kai
 Learn
 Practice Test
 Spaced Repetition
 Match
 Flashcards
 Knowt Play
1/8

There's no tags or description
Looks like no tags are added yet.
9 Terms
What is the purpose of the Black-Scholes Formula?
to calculate the theoretical value of a European Option directly
→ avoid calculating a large Binomial Tree
What happens when the number of steps in a Binomial model increases?
the calculated option price approaches the Black Scholes value
What five inputs are needed for the Black-Scholes Formula?
Stock Price: S
Strike Price: X
risk-free rate: r
volatility: σ
time to expiration: T
What formula is used for negative Z-values?
N(z)=1−N(−z)
What is the formula to calculate d1?
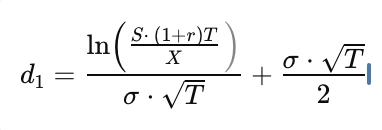
What is the formula to calculate d2
d2=d1−σT
What is the main Black-Scholes Call pricing formula?
C0(X)=N(d1)⋅S−N(d2)⋅(1+r)TX
What is the main Black-Scholes Put pricing formula?
use Put-Call Parity:
P0(X)=C0(X)+PV(X)−S
What are the steps of the Black-Scholes formula?
calculate d1 and d2
Determine N(d1) and N(d2)
Calculate the Call Option Price and Put Option Price (using Put-Call Parity)