advanced auditing. lecture 8 (unfinished)
 Call Kai
 Learn
 Practice Test
 Spaced Repetition
 Match
 Flashcards
 Knowt Play
1/11

There's no tags or description
Looks like no tags are added yet.
12 Terms
Substantive Analytical Procedures:
The comparison of quantitative relationships among account balances and other indicators to an auditor’s expectations
order of substantive
expectation: Build it from reliable data: prior year, budgets, nonfinancial measures
compare: Recorded amount vs. expectation; set a tolerable difference
investigate: Differences above the threshold: inquire and corroborate
Nonfinancial Measures and Fraud Risk
Fraud firms show a larger gap between financial growth and NFM growth
non financial measures for substantive analytics:
build expectations with NFMs; a gap between financial and nonfinancial growth is a red flag
draw audit testing hierarchy

what auditor does for all line items
recalculation
how does auditor perform recalculation
Agree sub-ledger totals to the general ledger
Agree the trial balance to the financial statements
Recalculate depreciation, interest, accruals
what to watch out for with recalculation
Precise, but only as good as the data used
Often done with data analytics (full population)
what does auditor do for PP&E
inpsection of tangible assets
how does auditor do inspection of tangible assets
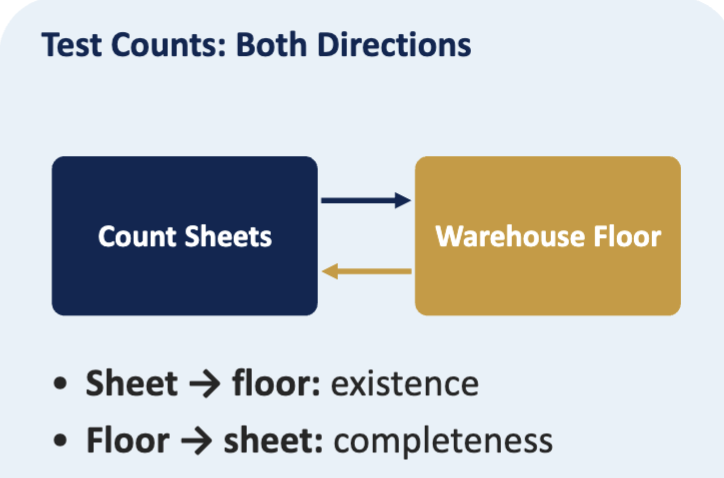
Register → floor: does the asset exist?
Floor → register: completeness
Check condition: impairment indicators (valuation)
Support: vouch additions to invoices; recalculate depreciation
what to watch out for with inspection of tangible assets
Seeing is not owning: rights need documents
Says little about valuation
what does auditor do for