chp 4 - independence and ethics
 Call Kai
 Learn
 Practice Test
 Spaced Repetition
 Match
 Flashcards
 Knowt Play
1/22

There's no tags or description
Looks like no tags are added yet.
23 Terms
AICPA Code of Professional Conduct (3 tier hierarchy)

(independence framework) to be independent, you must be independent in two things:
fact AND perception
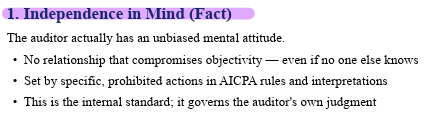
Independence in mind
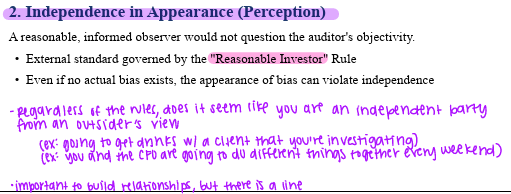
Independence in appearance
the reasonable investor rule
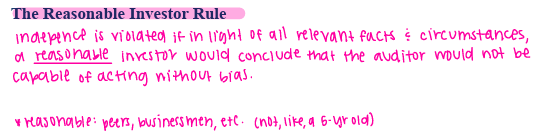
reasonable investor key reminder
even when a specific rule or interpretation addresses a situation, you must STILL apply the reasonable investor rule!
attest engagement team
any part of the audit team
All partners, managers, staff, and other professionals participating in any attest engagement for the client
Includes those who perform concurring reviews
immediate family (of engagement team)
spouse, spousal equivalent, and dependents (child or other dependent)
making sure they don’t violate the rules on your behalf
close relative
parent, sibling, or non-dependent child
less-stringent rules apply — but still relevant if a key position or material interest exists
covered member
includes:
individual on the engagement team
individual in a position to influence the engagement team
ex: employee inside company that the audit team consults with
partner or manager who provides > 10 hours of non-attest services to the client
ex: manager in tax for the company
partner in the office of the lead engagement partner
ex: higher up in the firms
the firm itself, including the firm’s employee benefit plans
ex: investing options will already be vetted by your firm and ensure independence
an entity that can be controlled by any covered member or combination of covered members
key position
a “key position” at a client means an individual who has primary responsibility for:
significant accounting functions
preparation of financial statements
ability to exercise influence over the contents of financial statements
ex of key positions: director, ceo, cao, coo, president, general counsel, controller, director of internal audit or financial reporting, treasurer, or equivalent
financial interests - direct
exists when the auditor owns equity or debt instruments of a client directly

financial interests - indirect

mutual fund example

employment relationships - former auditor joins the client

employment relationships - former client employee joins the audit firm

employment relationships - immediate family employment at client

employment relationships independence violations
the revolving door between audit firms and clients creates some of the most common independence violations
non-audit services (for public company clients, the following services are PROHIBITED)

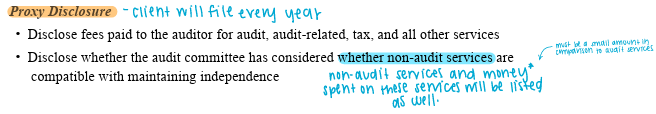
Other important facets of independence - proxy disclosure
Other important facets of independence - quality control safe harbor
SEC Rule 2-01(d) provides a limited exception when an individual “covered person” unintentionally lacks independence. The entire firm will not automatically be considered non-independent if all three conditions are satisfied
1. the individual did not know about the circumstances causing the violation
ex: finding out about a long lost sibling that owns shares in your client’s company
the violation is corrected as promptly as possible after the individual or firm becomes aware of it
ex: immediately telling them to sell it, as well as putting it in firm’s tracking and trading system
the firm had an effective quality control system providing reasonable assurance that the firm and its employees maintain independence
ex: firm having a tracking and trading system available to employees. shows them what they can and cannot invest in
ex of quality control safe harbor
An audit manager inherits stock in an audit client without initially knowing that the estate contains the investment. Once discovered, the stock is promptly sold, the person is removed if necessary, affected audit work is evaluated, and the matter is processed through an effective independence system.
aicpa 6 principles
