Math3075
 Call Kai
 Learn
 Practice Test
 Spaced Repetition
 Match
 Flashcards
 Knowt Play
1/25

There's no tags or description
Looks like no tags are added yet.
26 Terms
Single Period Model Theorems
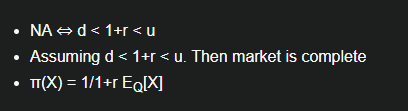
Arbitrage Definition

Q is an EMM if:

1st FTAP

Claim X is replicable if and only if…
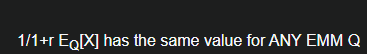
Market is complete if and only if…
EMM is unique
Tower Property for Conditional Expectation
Where we assume G1 is a sigma field containing LESS information than G2

Martingale Requirements for adapted/stochastic process
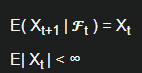
Super Martingale Requirements

Sub-Martingale Requirements

Self financing portfolio if:

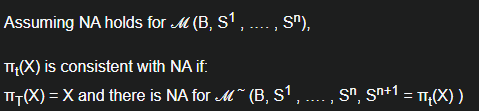
Arbitrage Pricing Principle
Assuming NA holds for ℳ (B, S1 , …. , Sn),
πt(X) is consistent with NA if:
πT(X) = X and there is NA for ℳ ~ (B, S1 , …. , Sn, Sn+1 = πt(X) )
Martingale Measure
What makes it equivalent is when Q is equivalent prob measure.

Risk Neutral Pricing Formula

2nd FTAP
Market Complete ⇔ EMM is Unique


American Option Price
The solution here being rational stopping time

Rational stopping time

Properties of Brownian Motion
Wt - Ws ~ N(0, t - s)
Wt4 - Wt3 is independent of Wt2 - Wt1
Cov(Wt , Ws) = min( t, s)
W is a martingale
Bank Account Dynamics

Stock price dynamics

Given X = f (ST), what is πt(X) under BM?

Delta/Hedge Ratio

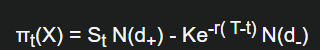
BS Formula
πt(X) = St N(d+) - Ke-r( T-t) N(d-)
d± =


= S0