TCP December 2026
 Call Kai
 Learn
 Practice Test
 Spaced Repetition
 Match
 Flashcards
 Knowt Play
1/106

Earn XP
Description and Tags
As above.
107 Terms
Corportion tax pro forma
Trading income X - Adjusted trading profits less capital allowances
Property income X - From UK and overseas let property
NTLR X - Non trade interest receivable less interest payable
Misc income X - e.g. royalties
Chargeable gains X - chargeable gains less capital losses
Total profits X
Qualifying donations (X) - National charity donations
Total taxable profit X
Difference between local + national donations for corporation tax calculation
National = Qualifying donations, deducted from total profits.
Local = Trading income, local charitable donation considered advertising
Threshold for a company private use when it comes to leased cars
ZERO
No private lease available for companies
Over how many emissions for a car is considered high emissions
>50g of Co2 per KM.
Flat rate 15% disallowance (leased cars only)
Low emissions under Co2 completely fine
Rule for gifts to customers to be allowable for tax adjusted trading profits
-Not food or drink or tobacco
-Under <£50 per head
-Contains company advertising
What is substantial shareholding exemption and what criteria is required to claim
Substantial Shareholding Exemption (SSE) is a UK corporation tax relief. Occurs when company disposes shares in another company. To qualify:
-Substantial shareholding of at least 10%
-Held for a continuous period of 12 months out of the 6 years prior to disposal
-Must be a trading company
If criteria met, 100% relief is provided.
Tax relief for ingangible fixed assets available
For intangibles other than goodwill, a company can claim either amortisation, or claim WDA @ 4% PA on cost as a tax allowable exepsnes.
(only worthwhile if UEL >25 years and not pro-rated)
Relief available for goodwill
If a company purchases goodwill, a deduction can be claimed at 6.5% if the goodwill was purchased from an unconnected party, and acquired with other qualifying intellectual property assets.
What is RDEC? And how would it be treated when calculating corporation tax.
R&D Capital expenditure.
Companies qualifying can claim a RDEC credit of 20% of qualifying revenue expenditure
R&D total cost would be deducted from trading profits, RDEC added back, to reach your TTP. Corporation tax calculated based on that figure then full RDEC fully took off the liability.
What is rollover relief and when is it applied
Available where a qualifying business asset is disposed, a replacement asset is acquired (1 year before disposal or 3 years after disposal) and both assets are used in the trade.
The ‘gain’ is therefore deferred, not exempt.
Replacement asset cost, less deferred gain = new base cost of replacement asset.
What is structure and building allowance (SBA)
a UK tax relief that provides a flat 3% annual deduction on the capital expenditure applied to new structured e.g. offices.
Relief is not available for land
Claim must be made from when a structure or building first comes into use
On disposal, add cumulative total of SBAs already claimed, increasing gain.
*INFO AVAILABLE IN TAX TABLES
What is DTR and how is it applied
Double tax relief.
Available if a UK company has income from UK and overseas
Always the lower
UK Corporation tax attributable to overseas income and Overseas tax suffered.
E.g. if three sources, UK income, overseas interest and overseas rent, should calculate DTR for each individual revenue stream
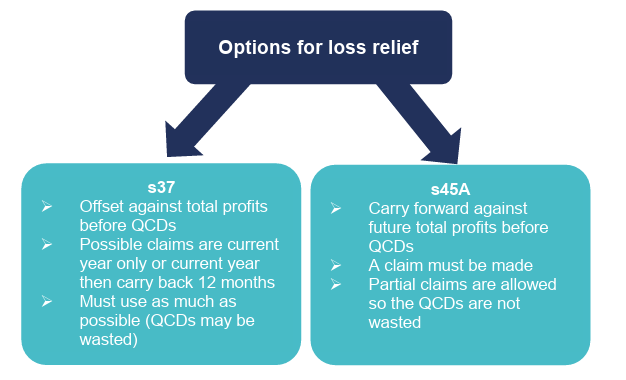
What are the two options for loss relief and difference for companies
S37(Carried back upto 2 years) S45A (Carried forward) → Claim Required
Note: S37 can be carried back 3 years if loss arises in last 12 months of trade.
Payment dates of CT - Large and small companies
Small → 9 Months and 1 day to pay liability
Large → Augmented profits > £1.5m → Pay by instalments (14th month of month 7,10,13,16, from start of accounting period)
If a group company, £1.5m large company limit is scaled down.
Difference between chargeable gains and loss groups
Chargeable gains group
-Principle company must have >75% in at least one subsidiary.
-Further subsidiaries can quality through a chain provided there is 75% at each level and >50% effective ownership by principal.
Loss relief group
Requires a 75% relationship between the subsidiaries.
Indirect subs: 75% at each level + 75% effective ownership by principal.
Company can be in more than one loss relief groups, unlike gain groups limited to one.
Implications of gross gift aid
Reduces Adjusted net income
Widens basic rate band
What are cash earnings (what calculating class 1 primary and secondary NIC)
Salary
Bonuses
Comission
Tips
Stat payments
Overtime
Expenses that are really remuneration (excess mileage)
Vouchers
What types of NIC are deducitble from trading profits
Class 1 secondary (employer)
Class 1a (bik)
Class 1b (paye settlement agreement)
How are leases and grants treated as a disallowable expense for companies and sole traders
Grant - disallowed
Renewal of a long lease (>50 years) disallowed
Renewal of a short lease (<50 years) allowed
Same for companies and sole traders
How to treat gift aid in relation to somebodys income
If somebody donated £240 gift aid for example, this is net as it is treated as a figure that had basic rate band deducted.
Need to gross up - multiply amount by 100/80. E.g. £240 ×100/80 = 300 Gross.
This amount is subsequently deducted from your total earnings, and added to basis rate band.
What is the saving income allowance depdning on tax bands
BRB - 12570-50270 - £1000
HR - 50271-125140 - £500
ADDITIONAL RATE - 1254110+ - £0
What are integral features and what capital allowances are made on them
Specific plant and machinery components that are integrated into a commercial building.
Companies can claim 50% FYA with remainder going into special pool
E.g. air con, ventilation, electrical and lighting systems
Difference between carried forward losses between companies and sole traders
Sole trader → automatically carried forward → Future profits of same trade only (S83)
Companies → claim required → Can set against subsequent total profits → Can be claimed against total profits before deducting QCDs (preserves these) (S45A)
Rules for trading loss relief for sole traders
S83 - Carry forward loss against first available trading profits of the same trade
S64 - Offset loss against total income in current tax year AND / OR previous. Choice, unlike companies who must offset against current year first.
Tax treatment for company purchase of own shares for individuals
Either have capital route or income route to treat
Capital route conditions:
Uncle bens sells orange rice
Unquoted trading company e.g. ltd
Benefit of trade - e.g. buying out retired director, shareholders that don’t get on
Substantial reduction - No more than 30% shares in company and 75% of prev shareholding. (both must be met)
Owned for 5 years (3 if inherited)
Resident in uk

How are distributions to shareholders treated pre appointment of liquidator v post appointment
Pre appointment
-Distribution treated as dividend, may be covered by dividend nil rate band, taxed @ dividend rates.
Post appointment
-Treated as capital distribution. Proceeds less costs. Deduct AEA to arrive at taxable gain, then charge capital gains tax @ relevant rate.
Chargeable gains group definition
For a chargeable gains group to exist, there must be a direct holding of at least 75%.
Indirect holding of principle company needs to only be greater than 50%.
E.g.
R LTD ownes 80% of L LTD, who owns 60% of P LTD.
R > 80% in L = group. Indirect holdings = 80% * 60% = 48% meaning P could not be in the group as his holdings do not exceed 50%.
What are class 1B contributions and due dates (electronic/other)
PAYE settlement agreement used by employer to settle PAYE/NIC due to HMRC on certain expenses or benefits.
1)Income tax that would had been due by the employee on an equivalent expense or benefit grossed up by employers marginal tax rate
2) Class 1B NICs on the grossed up value of these expenses.
Class 1Bs are payable at a flat rate of 15%
Electronic payment → 22nd October following end of tax year
Other → 19th October following end of tax year
Fractions to gross up
100/80 for a basic rate taxpayer
100/60 for a higher rate tax payer
100/55
Gross up when the question gives you a NET amount and you need to reconstruct the amount before tax/relief was deducted. E.g. pension (Gross contribution), gift aid.
What actions should be took in accordance with ICAEW guidance in professional conduct in relation to taxation if deliberate misstatement of tax return is identified.
-Review engagement letter for authority to disclose to HMRC
-Ask client for authority to disclose to HMRC due to confidentiality
-Amend tax return
-Deadline for amending the tax return for 2024/2025 tax year would be 31 jan 2027.
-Consider resignation, if decided to resign, inform the client in writing. Also inform HMRC of resignation without disclosing why.
-Consider a money laundering report to firms MLRO
-Avoid tipping off
For a company group loss relief, what is claimed against TTP.
Group relief claimed is the lower of maximum available losses and maximum available profits.
Make sure to time apportion both if groups do not have the same period.
Rule for a sole trader for loss relief deducted against trading and non trading income
Same trade → No £50k/25% Cap
General income → Restricted to higher of £50,000 and 25% of adjusted total income.
When is a directors bonus assessable as employment income
Earliest of the following key dates:
-When payment is made
-When they become entitled to it
-When its credited in the accounts, or period end
How to calculate accomodation benefit
Cost - £75,000 * interest rate.
(If 6 years between purchase and move in, replace cost with MV @ date of when employee first moved in)
Accomodation benefit is
The higher of annual value of the property V the rent paid by employer
Limit for a interest free loan
No benefit if loan @ official rate of interest or <10,000.
Anything above this amount, if the interest rate is favourable this is treated as a BIK compared to official rate of interest.
Property income assessment for sole trader - CASH V ACCRUALS BASIS
Cash basis is default if property receipts do not exceed £150,000 (state cash basis for mark)
If exceeds £150,000, must be accruals basis
Property income sole trader capex rules
P&M - Deduct from rental income as expense
Cars - Capital allowance (FYA)
Land & Buildings - no deduction
For capital allowance disposal purposes, what is the amount brought in restricted to
Lower of original cost and proceeds
How does loss relief on cessation work
Terminal loss relief - s89 available for loss in final 12 months of trading.
Taxpayer can carry abck trading income of three preceding tax years on a LIFO basis.
Formula for part disposal of a asset for which a individual will face capital gains on
Original cost * A / (A+B)
A = Proceeds of asset being disposed
B= Market value of party being retained
What is business asset disposal relief for capital gains tax
Tax paid that reduces capital gains tax when you sell or close part of your business.
14 % on disposals, compared to typial 18%
Rules in relation to overseas workday relief
Can’t exceed amounts earned relating to duties outside the UK.
Loses PA if elect to claim.
What is the rule in relation to pre trading expenditure
Qualifying revenue expenditure incurred 7 years before commencement of trade is treated as incurred on the first day of trading, provided it would have been deductible if incurred after trading commenced.
Difference between leased cars for disallowable expenditure between accruals and cash basis.
Accruals = Lease car → Restrict private use → Consider 15% disallowance based on co2 emissions
Cash = Lease car → Deduct cash paid → Restrict for private use → No separate 15% restriction
What administration is associated with stamp duty land tax
Land transaction return submitted to HMRC + SDLT paid within 14 days of the effective date of the transaction (usually completion).
What is a degrouping charge
is a UK corporation tax or capital gains tax rule that claws back the benefit of a "no gain/no loss" intra-group asset transfer when a company leaves a corporate group
Triggered if left the group within 6 years
departing company is treated as if it sold and immediately reacquired the asset at its market value at the time of the original intra-group transfer
Corporation tax payable proforma & when is CT due
Trading profit (less capital allowances) X
NLTR X
Property income X
Chargeable gains X
Total taxable profits X
TTP*CT Rate = CT Liability. Then deduct any further relief (e.g. RDEC)
Payment: 9 month + 1 day after accounting period end
Return: 12 months after accounting period end
What is double tax relief
The lower of :
Foreign tax suffered at applicable rate
UK tax attributable to foreign income at relevant rate
Difference between TTP and augmented profits
Augmented profits determine what marginal corporation tax rate zone the company falls into.
Corporation tax is charged on TTP.
TTP + Dividend income = Augmented profits
What is indexation applied to
Companies only, and on cost.
What is blind persons allowance
For the 2025/26 tax year, the UK Blind Person’s Allowance is £3,130. Added to the standard Personal Allowance of £12,570, this gives you a total tax-free income allowance of £15,700
For a 2025/2026 year, when would a sole traders Income tax liability and class 4 NIC liability be payable.
Payment on account on 1) 31/01/26 2) 31/07/26 3) and a balancing payment due 31/01/27.
Income tax liability
+
Class 4 NIC liability
=
Relevant amount for POA.
What are the conditions for BADR
Sole trader / Partner
-All or part of a business, owned for >2 years.
-Shares in a personal trading company where the individual is an employee. →FETT for shares=
Five%
Employee
Trading co
Two years for all
-Ensure to allocate losses/AEA against non-badr gains first to save allowance.
-Asset must had been held for at least 24 months.
-BADR must be claimed within 12 months from 31 Jan following the tax year qualifying disposal is made.
Stage 1 of IHT pro forma - Calculating the chargeable amount
TRANSFER
Less: (Specific exemptions)
Less: (CY AEA)
Less: (Previous year unused AEA)
=
Chargeable amount
What 3 transfers made in life or death are exempt from IHT
-Spouse or civil partner
-Charity donation
-Political donation
IHT Payment + Account dates
IHT Payment: 6 months after END of month of death
IHT Account: 12 months after END of month ne death
What is investors relief and how is it applicable
Reduction that lowers the tax rate on profits from selling ordinary shares in an unlisted trading company.
Tax rate for disposals is 14%.
Life time limit of £1mil in qualifying lifetime gains.
Gift relief
Gift or sale at undervalue, of qualifying business property. Defers the donors gain by pushing into the recipients base cost.
Transfer to a connected person will trigger market value proceeds when calculating the gain.
If company has non business assets, need to do Gain *Chargeable business assets / total chargeable assets
when assets are gifted shares in donors personal trading comapny, gain eligible to be held over is restricted to
Total gain * CBA / CA
CBA = Chargeable business assets
CA = Market value of chargeable assets. (Owned by company but not used in business)
Conditions for investors relief
For external investors selling or disposing qualifying shares in an unlisted trading company.
-Unlisted ordinary shares in a trading company for commercial reasons
-Held for minimum of 3 years (2 for badr)
-By a individual who is not a employee of company
BADR only available to those who own 5% of shares., Investors relief is a alternative to investors.
Relief available is the same as BADR - 14%
Private residence relief
Defers CGT when selling own property
Must be:
-Main residence
-No business use
-Gains apportioned for portion of gain attributable to periods of occupation
Special rules / exemptions
-Final period of ownership (9 months) always qualifies for PRR if not moved out elsewhere.
-3 years any reason allowable
-4 years working elsewhere in the uk allowable
-Unlimited time overseas.
(Divide qualifying occupation months by total ownership months, and multiply by total gain for relief available)
Matching rules for shares
Shares acquired on same day at disposal
Shares acquired within following 30 days of disposal on a FIFO basis
Shares bought prior to disposal date (s104)
Incorporation relief and when can it apply
Sole trader transfers business as a going concern. Relief only given on proportion of business paid for in shares.
Transferred with:
all its assets other than cash
To a company
In return wholly or partly for share
Incorporation relief can defer the chargeable gains, by reducing the base cost of shares received.
If consideration is partly shares & other items, gain is apportioned.
Total gain on business assets * (Value of share consideration / Total consideration).
Deferred gain is deducted from market value of shares to arrive at adjusted capital gains tax base cost.
Non deferred gain element = taxed immediately
**If original shares qualify for BADR, it may be better to tax now, as later shares would not quality for BADR. Assess ad compare to what’s better.
Difference between output VAT and input VAT
Collected on sales and paid over to HMRC → Output
Paid on purchases and reclaimed from HMRC → Input
Typically 1 month + 7 days after end of VAT period.
Related property formula
Higher of : Transfer of value
Value of property transferred formula:
Value of whole property * Transferors value/Transferors value + value of related property
Related property is just spouse or civil partner, or given to charity within 5 years.
Variation of will
Made by original beneficiary under terms of the will, must:
-Be made within 2 years of death
-made in writing (deed of variation)
-contain statement that variation is to have effect for iht purposes
What is business property relief not available on
Expected assets - not used mainly for business periods throughout the 2yars prior to transfer.
Value eligible for BPR =
Value of transfer * Net assets-Expected assets
/
Net assets
qualifying business assets for gift relief
-Business assets
-Ltd trading shares
-Plc trading shares (>5% holding required)
Conditions for a transfer of a going concern business
-Transfer of a whole business as a going concern
-no change in trade
-no significant break in trade
-transferee becomes vat registered immediately after transfer
Transfer of going concern takes transfer outside the scope of VAT.
For residential nil rate band transferred, what is the rule. Also how is it tapered.
Residence nil rate band is limited to:
-Net value of property left to direct descendants
-Available band (£175000 for tax year 25/26) + (100% * Unused % of NRB)
Tapered for £1 every £2 over estate value of £2mil.
For overseas administration expenses for IHT tax, what are administration costs capped at?
5% of the overseas property value
Capital goods scheme disposal
Taxable sale → Remaining intervals treated as 100% taxable. Exempt sale is 0%.
early year loss relief sole traders
Early trade loss relief allows sole traders to offset trading losses made in their first four tax years of a business against their general income from the previous three tax years on FIFO basis
When does a balancing charge / allowance arise on CA?
TWDV > Disposal → Balancing allowance
Disposal > TWDV → Balancing charge
When is IHT payable and by who
Payable by the executor/administrator of the will directly from the deceased assets.
Will = Executor, no will = administrator.
Payable 6 months from the end of the month of death. E.g. dies 2nd august, payment due 28 feb (6 months after)
What is a gift with reservation (IHT)
When someone gives a asset away but continues to use/benefit from it after the gift.
Therefore, it’s treated as still belonging to the individual when they die and included as part of the death estate, rather than PET.
What is S455 tax
Close company loan → s455 tax @ 33.75%.
Tax charge due on lower of value of loan / amount o/s @ due date
Due 9m 1 day (same as CT)
Once repaid/written off, tax repaid. Treated as a distribution to participator.
Interest at favourable rate is treated as a BIK, as such class 1A NIC charged on this. E.g. if interest was charged @ 3% and official interest rate was 3.75, difference would be taxable and subsequently deducted as a allowable expense.
Close companies - how are benefits to non employees treated
-Benefit treated as a distribution(dividend), not taxed through employment income rules.
-Cost to company = disallowable
-Value of benefit calculated under normal employment income rule
-No class 1A NIC on distribution.
When does S455 tax not apply
-Loan made in ordinary course of business
-Loan to director/ employees if:
<£15,000, full time owner and owns <5% of company.
Stage 2 of IHT pro forma
Calculating lifetime tax (CLTS only)
Chargeable amount X
Less: NRB (£325,000) X
Taxable amount X
Lifetime tax @ 20/25% X
Gross chargeable transfer X
Trustee pays 20% donor pays 25%
Stage 3 of IHT
Calculating death tax (gifts 7 years pre death & death estate only)
Gross chargeable transfer X
Less: Residence NRB (X)
Less: Nil rate band available (X)
Taxable amount X
Death tax @ 40%/36% X
Less: Taper percentage (X)
(hardmans)
Less: Lifetime tax paid (X)
Death tax payable
When does stamp duty apply, and difference to stamp duty reserve tax
Tax which is subject to the buyer.
stamp duty = stock transfer form required
applies to the purchase of existing shares from a previous owner, not to a new issue (or 'allotment') of shares created by the company itself.
Stamp duty is always rounded up to nearest £5
None due if consideration is <£1,000
stamp duty reserve tax
Due on electronic transactions (no stock transfer form), automatically corrected and not rounded.
Paid within 14 days
Stamp duty land tax
Tax payable on purchase on land and property.
Calculate based on the consideration inclusive of VAT using the rates available in hardmans.
Company buys a residential property → 5% surcharge
Non uk resident → 2% (in addition to companies surcharge)
If consideration >500,000, flat 17% charge.
Adjusted net income pro forma and implications
Total income X
Less: Gross gift aid donations (X)
Less: Gross qualifying pension (X)
Adjusted net income X
High income child benefit charge begins when ANI exceeds £60,000.
Reaches £100% when ANI reaches £80,000.
The charge is 1% of child benefit for every £200 of ANI above £60,000
For IHT rate to be reduced from 40% to 36% what needs to occur
must leave at least 10% of the net baseline amount (after deduction of NRB) of your estate to a qualifying registered charity.
Business property relief trigger
-Sole trade, partnership interest, unquoted trading co shares → 100% BPR
Unquoted company shares= Normally 100% BPR owned >2 Y
Shares in quoted trading co where shareholder has control → 50% BPR
BPR = Value transferred* (Qualifying business assets / Total relevant assets)
Make sure to strip out expected assets
Can be on both lifetime tax and death estate, unlike resident nil rate band what is a death estate.
Income tax POAs required and how much
Each POA = 50% of PY relevant liability (Income tax + Class 4 NIC)
No POA where liability <£1000
31 Jan - 50%
31 July - 50%
Following 31 Jan - Actual liability - both POAs = Balancing payment / refund
BADR vs Investors relief
BADR → Owner/Employee → >5% personal company → 2 year qualifying period. FETT for shares (five%, employee, trading co, two years)
Investors relief → External investor → brand new issued subscribed shares → no employment role → 3 year holding period.
Rollover relief rule for reinvesting proceeds into a depreciating asset
Gain is held over separately
Becomes chargeable on the earliest of:
-Disposal of replacement asset
-Replacement ceasing to be used in trade
-10 years after acquisiton
No gain / No loss transfer
Gains can be deferred automatically between:
-Spouses/civil partners
-Chargeable gains group
Recipient inherits groups historic base cost.
Degrouping charge arises if company sold within 6 years.
NGNL is a deferral, not a permanent exemption.
When will a degrouping charge arise and when to calculate.
NGNL Transfer → Company sells asset within 6 years → De grouping charge / gain which adds onto CGT calculation
Market value of asset at original transfer
Less:
Original/indexed group cost
= De grouping gain.
How can you treat a b/f capital loss in a company
Brought forward cant be moved.
In a gains group, gain can be moved into company with a b/f loss to offset against.
How to calculate marginal relief
Multiply by 25%
Marginal relief = (3/200 * (Upper limit - Augmented profits)
*Ensure to split accounting periods
How are normal dividends and group dividends treated for TTP
Normal = added to TTP to form augmented profits
Intra-group = not taxable and not part of augmented profits
Partial exemption VAT - Step to follow
1) Two simplified tests (hardmans)
2) Fail = do standard partial exemption method.
3) Allocate VAT between taxable and exempt supplies
4) Apply standard de minimus test to final figures
5) Pass = Recover all Input VAT, Fail = Recover only Input VAT on taxable supplies.
6) Annual adjustment comparing calculated recoverable VAT with that paid, difference being reclaimable.
When is VAT return due / payment
Return & payment both due 1 month 7 days
Who pays what rate of lifetime IHT chargeable on CLTs.
Trustees → 20%
Donor → 25%
DONOR QUARTOR
Fall in value relief - IHT
Donoe dies within 7 years of the gift (making a PET chargeable, or triggering additional death tax on a CLT).
Must had been sold at a fair value.
E.g. shares for £400,000 as a PET gifted 23/24, 25/26 died and shares were £400,000. FIV relief is 100k (decrease in value)
When is Resident nil rate band available
£175000 Available when a house is left to a direct descendent.
Deductible on death estate