Managerial Accounting: Costs, Reports, and Operations
 Call Kai
 Learn
 Practice Test
 Spaced Repetition
 Match
 Flashcards
 Knowt Play
1/60

There's no tags or description
Looks like no tags are added yet.
Name | Mastery | Learn | Test | Matching | Spaced | Call with Kai | Chat |
|---|
No analytics yet
Send a link to your students to track their progress
61 Terms
Managerial accounting vs Financial Accounting -Primary users of reports
FA- External users
MA - Internal users
Managerial accounting vs Financial Accounting- Types and Frequency of Reports
FA- External financial statements
MA - Internal reports
Managerial accounting vs Financial Accounting- Purpose of Reports
FA- General-purpose. MA- Special-purpose for specific decisions.
Managerial accounting vs Financial Accounting- Content of Reports
FA- condensed
MA- Very detailed.
Managerial accounting vs Financial Accounting- Verification Process
FA- Audited by C PA. MA- No independent audits.
Management Functions - Planning
Maximize short-term profit environmental protection and social
programs. Add value to the business
Management Functions - Directing
Implement planned objectives rewards to motivate employees
Hire and train employees make smooth-running operation
Management Functions - Controlling
keep activities on track
Determine if goals are met
Decide changes stay on track
informal or formal system of evaluations
-Managerial accountants have a single role within an organization: collecting and reporting costs to management
-Financial accounting reports are general-
purpose and intended for external users
-managerial accounting reports are special-
purpose and issued as frequently as needed.
-Managers' activities and responsibilities can
be classified into three broad functions: cost
accounting, budgeting, and internal control.
-Managerial accounting reports must now
comply with generally accepted accounting
principles (GAAP).
False
True
True
False
False
Manufacturing Costs
Activities and processes that convert raw materials into
finished goods
Direct Materials, Direct Labor, Manufacturing Overhead
Manufacturing Costs
Direct Materials
Raw materials are the basic materials and parts used in the manufacturing process and can be physically and directly associated with finished product during the manufacturing process
Manufacturing Costs Indirect Materials
Have one of two characteristics:
1. Not physically part of finished product
2. Are impractical to trace to finished product because
their physical association with finished product is too
small in terms of cost
Considered part of manufacturing overhead
Direct Labor and Indirect Labor
Direct Labor- Work of factory employees that can be
physically and directly associated with
converting raw materials into finished goods.
Indirect Labor - Work of manufacturing-related employees that has no physical association with the making of the finished product or costs for which it is impractical to trace to the goods produced.
Manufacturing Overhead
Costs indirectly associated with manufacture of the
finished product
-All manufacturing-related costs except direct materials
and direct labor
Also called factory overhead, indirect manufacturing costs
Product Costs
All manufacturing cost components:
o Direct materials
o Direct labor
o Manufacturing overhead (indirect materials, indirect labor, etc indirect costs)
Costs that are an integral part of producing product
Not an expense (COGS) until goods are sold
Period Costs
Nonmanufacturing costs
Includes all selling and administrative expenses
Charged to expense as incurred
(selling expenses, administrative expenses)
Suppose you started your own snowboard factory,
Terrain Park Boards. Here are some of the costs that your
snowboard factory would incur. Assign the following costs
Wood cores, fiberglass, and resin =
Labor to trim and shape boards=
Factory equipment depreciation=
Property taxes on factory building=
Advertising costs=
Sales commissions=
Factory maintenance salaries=
Salary of factory manager=
Cost of shipping boards to customers =
Salary of product quality inspector=
Direct materials
Direct labor
Manufacturing overhead
Manufacturing overhead
Period Cost
Period Cost
Manufacturing overhead
Manufacturing overhead
Period Cost
Manufacturing overhead
A bicycle company has these costs: tires, wages of employees who put tires on the wheels, factory building depreciation, advertising expenditures, factory machine lubricants, spokes, salary of factory manager, salary of accountant, handlebars, salaries of factory maintenance employees, and salary of product quality inspector. Classify each of these costs as a product cost or a period cost. Specify direct materials, direct labor, or manufacturing overhead for product costs
Tires = Direct materials
Wages of employees who put tires on the wheels = Direct labor
Factory building depreciation = Manufacturing overhead
Advertising expenditures =Period Cost
Factory machine lubricants = Manufacturing overhead
Spokes = Direct materials
Salary of factory manager = Manufacturing overhead
Salary of accountant = Period Cost
Handlebars = Direct materials
Salaries of factory maintenance employees = Manufacturing overhead
Salary of product quality inspector = Manufacturing overhead
merchandiser and a manufacturer differ in the cost of
goods sold section.
Formulas
Manufacturer = Beginning inventory + cost of goods purchased - Ending inventory = COGS
Merchandiser = Beginning Finished goods inventory + Cost of goods manufactured - Ending finished goods inventory= COGS
Total Manufacturing Costs-
Total Work in Process-
Total Manufacturing Costs - sum of direct material costs, direct labor costs, and manufacturing overhead incurred in the current year.
Total Work in Process - (1) cost of beginning work in process and (2) total manufacturing costs for the current period.
Cost of Goods Manufactured formula
beginning work in process inventory + total manufacturing costs = Total cost of work in process
Total cost of work in process - ending work in process inventory = Cost of goods manufactured
Refers to all business processes associated with providing a product or performing a service
For a manufacturing firm, these include the following

Just-In-Time (JIT) Inventory Method
System in which goods are manufactured or purchased just in time for sale
Total Quality Management (TQM)
System implement to reduce defects in finished products, with goal of zero defects
Theory of Constraints
Constraints ("bottlenecks") within the value chain that
limit company's potential profitability
Enterprise Resource Planning (ERP)
Software programs designed to manage all major business processes
Activity-Based Costing
Allocates overhead based on each product's use of
activities (more accurate product costing)
Sarbanes-Oxley Act
Clarifies management's responsibilities
Requires certifications by CEO and CFO
Match the descriptions to terms
a. Activity-based costing
b. Balanced scorecard
c. Corporate social responsibility
d. Just-in-time (JIT) inventory
e. Total quality management (TQM)
f. Statement of Ethical Professional Practice
g. Value chain
1. All activities associated with providing a product
or performing service.
2. A method of allocating overhead based on each
product's use of activities in making the product.
3. Systems implemented to reduce defects in finished
products with the goal of achieving zero defects.
4. A performance-measurement approach that uses
both financial and nonfinancial measures, tied to
company objectives, to evaluate a company's
operations in an integrated fashion.
G
A
E
B
Match the descriptions to terms
a. Activity-based costing
b. Balanced scorecard
c. Corporate social responsibility
d. Just-in-time (JIT) inventory
e. Total quality management (TQM)
f. Statement of Ethical Professional Practice
g. Value chain
5. Inventory system in which goods are manufactured
or purchased just as they are needed for use or sale.
6. A company's efforts to employ sustainable
business practices with regards to its employees,
society, and the environment.
7. A code of ethical standards developed by the
Institute of Management Accountants.
D
C
F
Cost Behavior Analysis def.
is the study of how specific costs respond to changes in the level of business activity.
activity levels include - sales dollars, miles driven, room occupancy.
Activity index:
Allows costs to be classified as variable, fixed, or mixed. identifies activity that causes change in behavior of cost
Variable Costs
Costs that vary in total with changes in the activity level.
Example: If the activity level increases by 10 percent, total variable costs increase by 10 percent
Remain the same per unit at every activity level.
Damon Company manufactures cell phones that contain a $10 camera. The activity index is the number of cell phones produced.the total cost of the cameras used increases by $10 with each manufactured phone. graph. shows, total cost of the cameras will be $20,000 if Damon produces 2,000 cell phones, and $100,000 when it produces 10,000 cell phones. unit variable costs remains the same as the level of activity changes. 2nd graph shows, the unit cost of $10 for the camera is the same whether Damon produces 2,000 or 10,000 cell phones

Fixed Costs
Costs that remain the same in total regardless of
changes in the activity level
Unit fixed costs varies inversely with activity: As ____
volume increases, unit cost declines, and vice versa
ex. rent, insurance
Company leases its productive facilities at a rent cost of $10,000 per month. Total fixed costs of the facilities will remain constant at every level of activity, as graph A shows. (Illustration of total fixed costs). But, on a per unit basis, the cost of rent will decline as activity increases, as graph B shows. At 2,000 units, the unit cost per cell phone is $5 ($10,000 ÷ 2,000). When Damon produces 10,000 cell phones, the unit cost of the rent is only $1 per cell phone ($10,000 ÷ 10,000).

Relevant Range
- Range of activity over which a company expects to
operate during a year. Relationship between variable costs and changes in activity level is often curvilinear. no straight-line relationship variable costs or fixed costs. fixed costs= nonlinear

Mixed Costs
Costs that have both a variable cost and a fixed component.
Change in total but not proportionately with changes in activity level
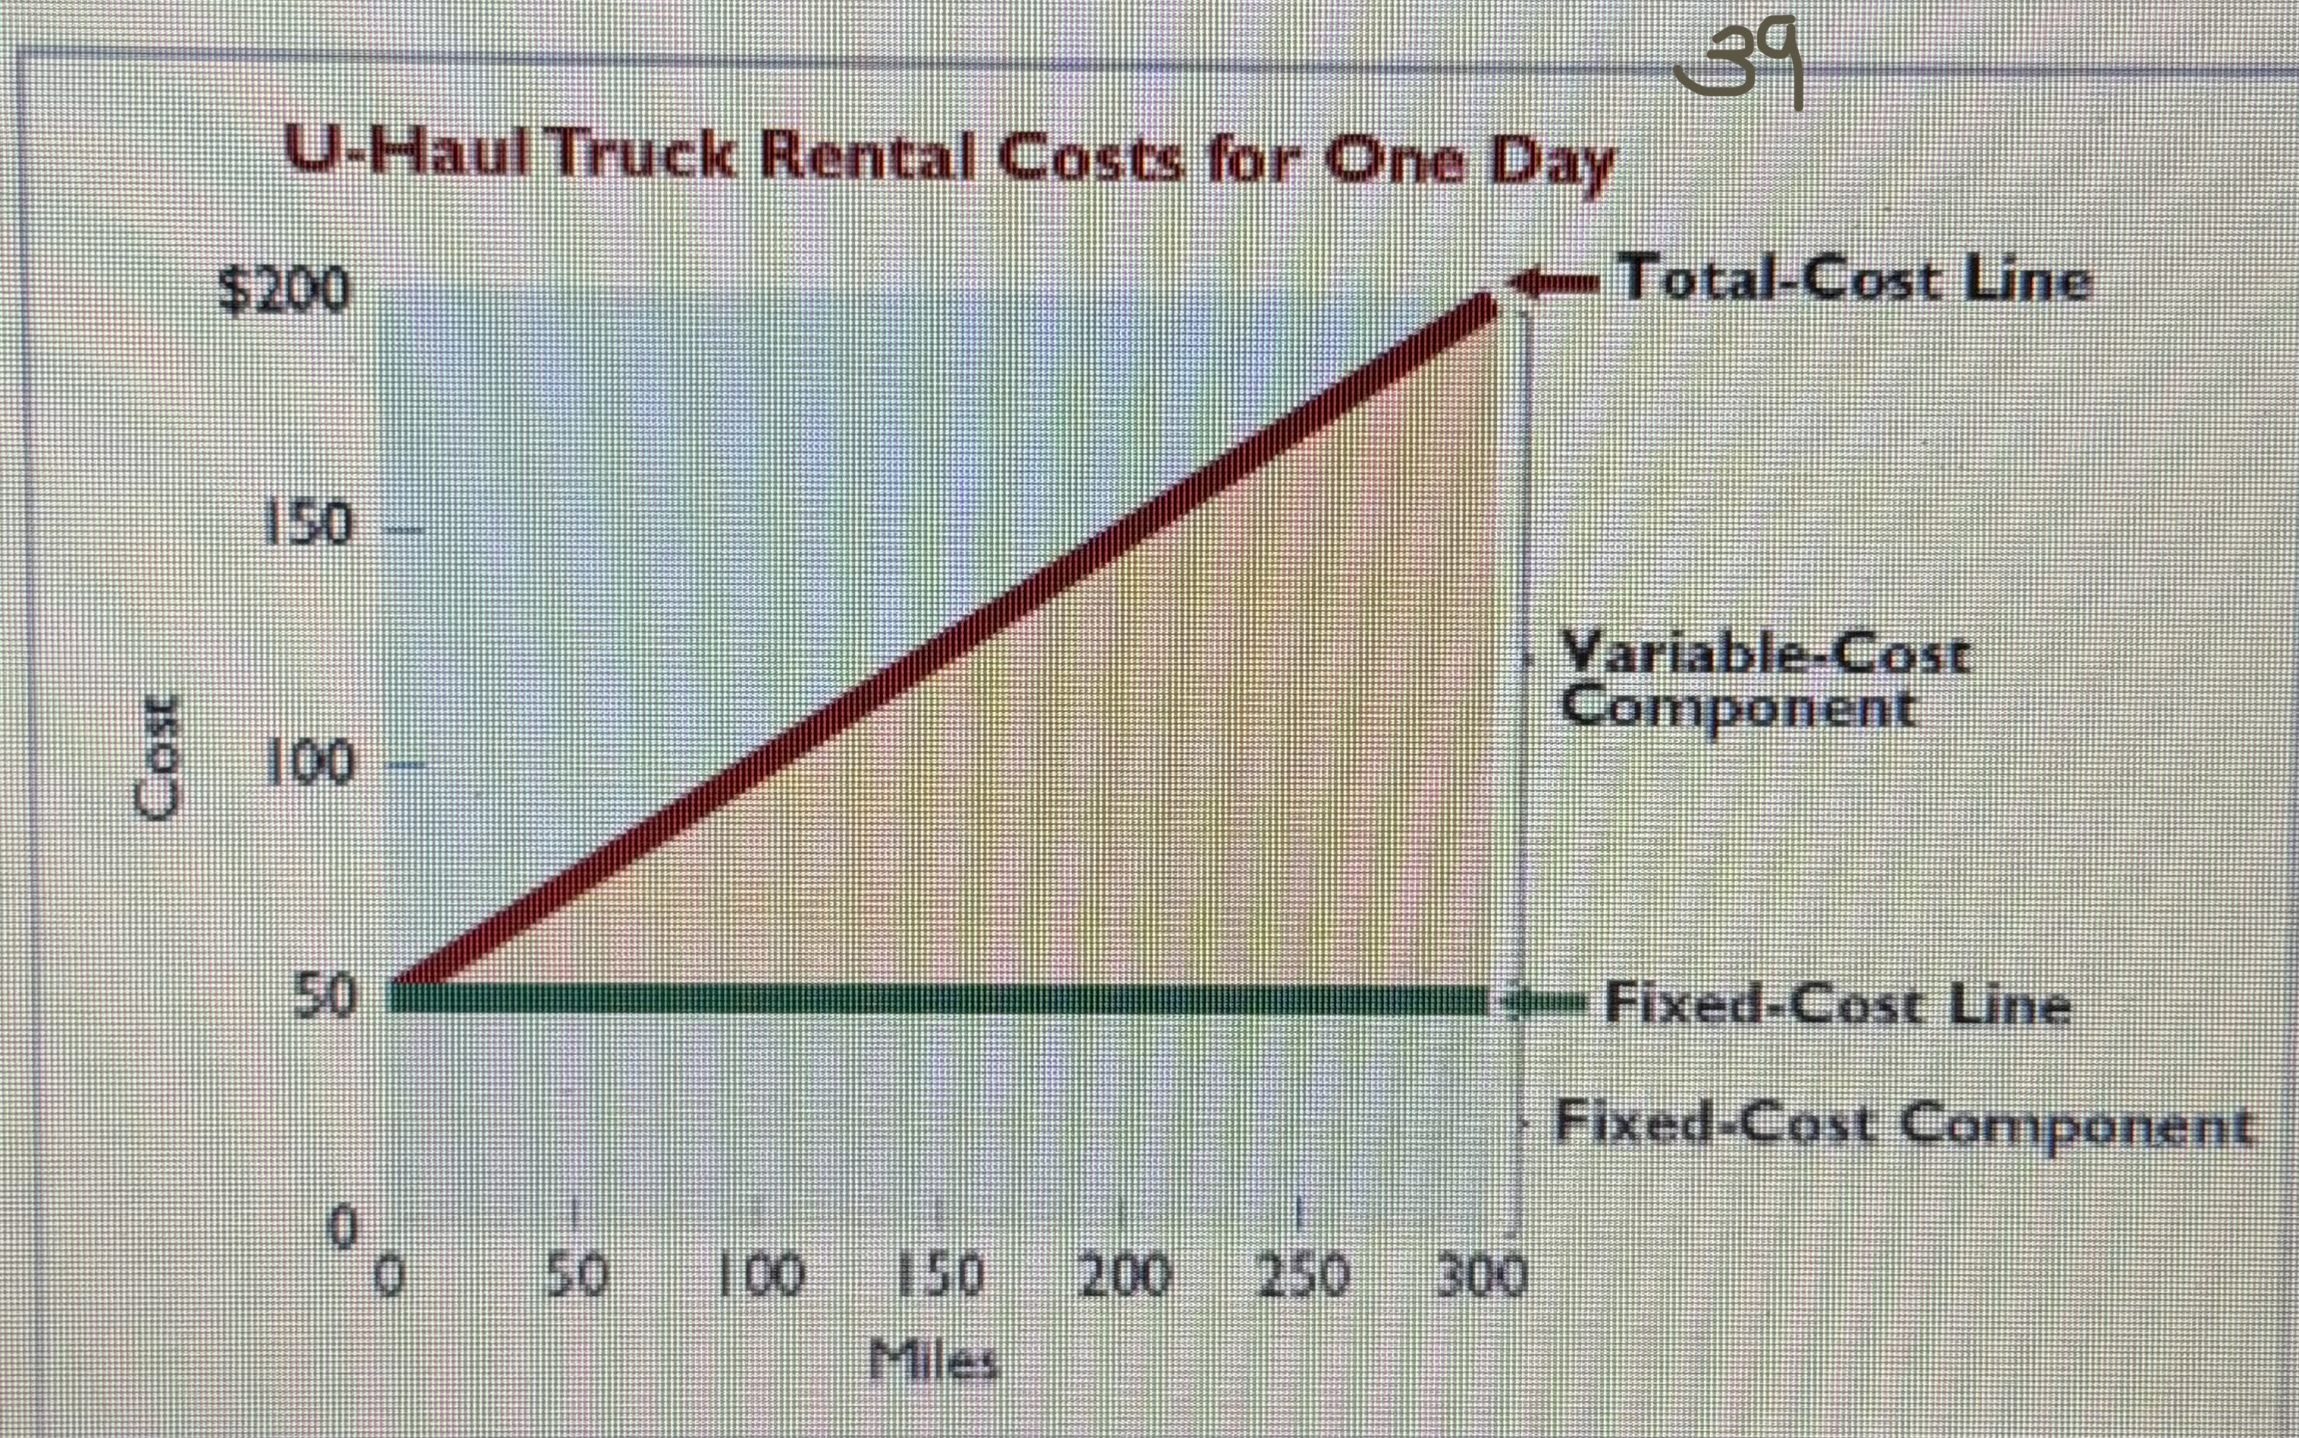
Classify each cost as variable, fixed, or mixed
direct materials
maintenance
direct labor
indirect materials
depreciation
utilities
rent
Variable= direct materials, direct labor, indirect materials
fixed= depreciation, rent
mixed= maintenance, utilities
High-low method
uses the total costs incurred at the high and the low levels of activity to classify mixed costs into fixed and variable components.
Equation for unit variable costs
Change in total cost as high versus low activity level / high minus low activity level = unit variable costs

High-Low Method
Computation of fixed costs

High-Low Method
Total costs for 45,000 miles Maintenance costs are therefore $8,000 per month of fixed costs plus $1.10 per mile of variable costs. This is represented by the following equation
Example: At 45,000 miles, estimated maintenance costs would be
(FC) 8,000 * (VC) (1.10 * miles driven) = total maintenance costs
8,000* (1.10*45,000) =57,500

(14,740) highest activ. lev. , lowest activ. lev. (11,100)
Variable cost= (14,740 - 11,100) / (9,800 - 7,000) = $1.30 per unit
Fixed cost= (14,740 - 12,740(1.30×9800)) = $2000 OR $11,100 − 9,100(1.30 × 7,000) = $2,000
Part b- Cost = $2,000 + ($1.30 × (8,000) units produced) which is Total cost is $8,000 2,000+10,400= 12,400
Cost-volume-profit
analysis is the study of the effects of changes in costs and volume (quantity) on a company's profits.
Classifies costs as fixed or variable.
Cost-Volume-Profit Analysis
Basic Components

Contribution margin and contribution margin ratio
amount of revenue remaining after deducting variable costs.
May be expressed as unit contribution margin.
Unit selling price - unit variable costs = unit contribution margin
unit contribution margin / unit selling price = contribution margin ratio
When the break-even-point in sales units is desired,
unit contribution margin is used
fixed costs / unit contribution margin =break even point in sales units
When the break-even-point in sales dollars is desired,
contribution margin ratio is
fixed costs / contribution margin ratio=break even point in sales dollars
Gossen Company is planning to sell 200,000 pliers for $4 per unit. The contribution margin ratio is 25%. If Gossen will
break even at this level of sales, what are the fixed costs?
$200,000
Lombardi Company has a unit selling price of $400, unit variable costs of $240, and fixed costs of $180,000. Compute the break-even point in sales units using (a) a mathematical equation and (b) unit contribution margin
sales - variable costs - fixed costs = net income
400Q - 240Q - 180,000 = 0
160Q - 180,000
Q=1,125 units
fixed costs / unit contribution margin = break even point in sales units
180,000 / 160 = 1,125 units
Target Net Income
Level of sales necessary to achieve a target income.
Can be determined from each of the approaches used to
determine break-even sales/units
sales - variable costs - fixed costs = target net income
Equation for sales in units and Equation for sales in dollars
(fixed costs + target net income) / unit contribution margin = sales units
(fixed costs + target net income) / contribution margin ratio = sales dollars
The mathematical equation for computing required sales to
obtain target net income is:
Variable costs + Fixed costs + Target net income.
Equation for margin of safety in dollars
actual (or expected) sales - break even sales = margin of safety in dollars
Equation for margin of safety ratio
margin of safety in dollars / actual (or expected) sales= margin of safety ratio
The higher the dollars or percentage, the greater the
margin of safety.
Marshall Company had actual sales of $600,000 when break even sales were $420,000. What is the margin of safety ratio?
(600,000 - 420,000) = 180,000
180,000 / 600,000 = 30%
30%
Zootsuit Inc. makes travel bags that sell for $56 each. For the coming year, management expects fixed costs to total
$320,000 and unit variable costs to be $42. Compute the
following:
a) break-even point in sales dollars using the contribution
margin (CM) ratio;
b) the margin of safety and margin of safety ratio assuming
actual sales are $1,382,400
c) the sales dollars required to earn net income of $410,000.
a) Contribution margin ratio = [($56 − $42) ÷ $56] = 25%
Break-even sales in dollars = $320,000 ÷ 25% = $1,280,000
b) Margin of safety = $1,382,400 − $1,280,000 = $102,400
Margin of safety ratio = $102,400 ÷ $1,382,400 = 7.4%
c) Required sales in dollars = ($320,000 + $410,000) ÷ 25% = $2,920,000

The high and low activities are 65,000 miles in December
and 15,000 miles in July.
• The maintenance costs at these two levels are $63,000 and
$39,000, respectively
Total variable cost = number of miles × cost per mile. At the low activity level of 15,000 miles, total variable cost is $7,200
(15,000 × $0.48).
To determine fixed costs, subtract total variable costs at the low activity level from the total cost at the low activity level.
Fixed costs = $39,000 − ($0.48 × 15,000) = $31,800
the cost equation based on the high-low method
for this data produces the following calculation:
maintenance costs = intercept (31,800) + slope x quantity (0.48 x miles driven)
Regression analysis
is a statistical approach that estimates the cost equation by employing information from all data points, not just the highest and lowest ones. fixed cost variable costs
total maintenece costs = intecept + slope x quantity
18,502 + (0.81 x miles driven)