ch1-7
 Call Kai
 Learn
 Practice Test
 Spaced Repetition
 Match
 Flashcards
 Knowt Play
1/36

There's no tags or description
Looks like no tags are added yet.
37 Terms
Relevance
Information is capable of making a difference in users' decisions. It has predictive value, confirmatory value, or both.
Expected Cash Flow =

Recoverable Amount
Recoverable Amount = the GREATER of
Value-in-Use (VIU)
Fair Value Less Costs of Disposal (FVLCD)
Find Compound Interest
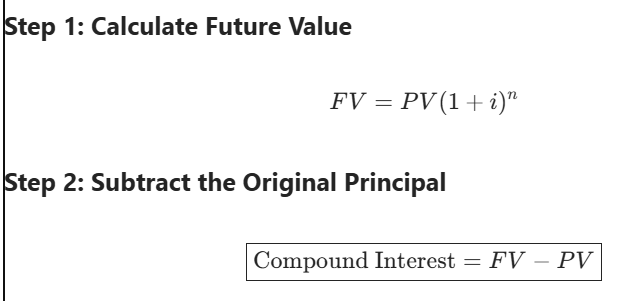
Impairment Calculation
When carrying amount is greater than recoverable amount, asset is impaired.
If CA is less than RA no entry no gain, do nothing.

Journal Entry for Impairment
Dr Impairment Loss
Cr Asset

Earning Per Share =

Price Earnings Ratio
Market Price per Share/EPS
Single-Step Income Statement
Revenues+Gains−Expenses−Losses
No subtotals like gross profit or operating income.
Profit Margin
Net Income/Sales
Return on Assets
Net Income/Avg. Assets
Multi Step Income Statement Formula
Multi-Step = GP → OI → IBT → NI
Gross Profit
Operating Income
Income Before Tax
Net Income

Operating Income =
Gross Profit - Operating Expense
Gross Profit - Operating Expense
Sales Revenue - COGS
Multi-Step Income Statement looks like:
Sales Revenue
- Cost of Goods Sold
--------------------
= Gross Profit
- Selling Expenses
- Administrative Expenses
--------------------
= Operating Income
+ Other Revenues/Gains
- Other Expenses/Losses
--------------------
= Income Before Tax
- Income Tax Expense
--------------------
= Net Income
weighted avg common shares formula
=SUM(shares*fraction of year outstanding)

Quick Ratio =
(Cash + Accounts Receivable)/Current Liabilities
Better if higher or lower?
Cash Debt Coverage Ratio =
Net Cash Provided by Operating Activites/Average Total Liabilities
Direct Method Components:
Cash received from customers 800,000
Cash paid to suppliers (300,000)
Cash paid to employees (200,000)
Cash paid for taxes (50,000)
-----------------------------------------
Cash from Operations 250,000
ndirect Method
Net Income 200,000
Add: Depreciation 50,000
Less: Increase in AR (20,000)
Add: Increase in AP 10,000
-----------------------------------------
Cash from Operations 240,000
Free Cash Flow to Operating CF
(Net Cash Provided by Operating Activities - Capital Expenditures - dividends)/Cash flow from operations
Current Cash Debt Coverage Ratio
Net cash provided by operating activities/Average Current Liabilities
Free Cash Flow
(Net Cash Provided by Operating Activities - Capital Expenditures - dividends)
Revenue Recognition Steps
Identify the contract
Identify performance obligations
Determine transaction price
Allocate transaction price
Recognize revenue when performance obligation is satisfied
Percentage of Completion
Cost Incurred/Estimated Total Costs
Revenue Allocation Formula

Assurance Warranty
A warranty that guarantees the product works as intended and complies with agreed-upon specifications. It is not a separate performance obligation.
✅ Recognize all product revenue immediately.
✅ Estimate future warranty costs.
✅ Record warranty liability.
Dr Warranty Expense
Cr Warranty Liability
Unearned Revenue Entries
Dr Cash
Cr Unearned Revenue
Later: Dr Unearned Revenue
Cr Revenue
Service Warranty
A warranty sold separately or providing an additional service beyond assuring the product functions properly. It is a separate performance obligation
Customer buys:
Laptop = $1,000
Extended 3-year warranty = $200
The warranty is a separate service the customer purchased.
Revenue Treatment
❌ Do not recognize all revenue immediately.
✅ Allocate revenue to warranty.
✅ Defer warranty revenue.
✅ Recognize revenue over the warranty period.
Intial Sale
Dr Cash 1,200
Cr Revenue 1,000
Cr Unearned Revenue 200
After part of warranty period expires:
Dr Unearned Revenue
Cr Warranty Revenue
Receivable Turnover Ratio

Days to Collect =
365÷AR Turnover
Percentage-of-Sales Method
Credit Sales × Estimated Uncollectible
Net Realizable Value =
NRV = Receivables we actually expect to collec
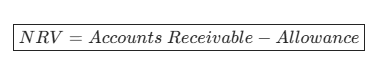
Allowance Method write-off entr
Dr Allowance for Doubtful Accounts
Cr Accounts Receivable
Direct Write-Off Method
Dr Bad Debt Expense
Cr Accounts Receivable
What happens to NRV after the write-off
