ECON0103 Tax Policy
 Call Kai
 Learn
 Practice Test
 Spaced Repetition
 Match
 Flashcards
 Knowt Play
1/121

There's no tags or description
Looks like no tags are added yet.
122 Terms
W1 - what is a tax incidence?
determination of who should pay tax
W1 - what is formal/statutory incidence? what is effective/economic incidence?
formal = who is legally paying tax
effective = who is actually bearing the tax burden
W1 - what determines the tax incidence?
Elasticity of demand. The number of alternatives and market conditions determines how much of the tax a business can pass to its customers
W1 - how do taxes affect asset prices? Example: government decides to make a thing tax exempt ?
Taxes distort asset prices as asset prices embed the taxation element
IF for example bonds are made tax exempt, its price would rise. Those who originally held the bond before exemption was announced would ‘gain’
W1 - what makes an income tax progressive?
a progressive income tax is where avg. tax rate rises with income
W1 - what are some costs to taxation?
admin, compliance costs
DWL/economic distortion
W1 - what is the income and substitution effect of tax? What measure of tax rate influences each?
income effect - i am being taxed more, therefore i should work more to increase my income. avg tax rates influence income effect. someone with higher ATR may decide to work more to maintain living
substitution effect - assuming leisure is a normal good, tax means working is no longer so attractive and i may want to consume more leisure. marginal tax rates influence substitution effect. one with higher MTR may substitute labor with leisure
W1 - what was the Window Tax issue and what did it demonstrate?
the issue in the UK whereby tax laws created economic distortions, leading people to board up their windows to pay less tax. The tax was meant to be on the rich but led the poor to cover up windows.
It also showed that many people will stay just below the threshold, e.g. if the law said 8+ windows incurred a tax, people would just report 7 windows.
W1 - who should be taxed according to Mirrlees, J. et al. (2011)?
final consumers. or else there will be economic distortions.
transactions such as exchanging of ownership should not be taxed either (property, for example)
W1 - wwhat are the arguments for and against a uniform taxation?
for: promotes simplicity, promotes equity regardless of goods preference
against: inverse elasticity rule - we could charge goods w inelastic demand more than goods with elastic demand. (But this also creates problems as necessities would be taxed - problem of unfairness)
W1 - what are corrective taxes according to Mirrlees, J. et al. (2011)?
taxes on negative externalities or internalities
→ smoking, alcohol, bad practices like gambling
by the Pigouvian Principle, the tax should equal the marginal damage caused by the externality
W1 - what is input VAT? Output VAT?
input VAT is the output VAT of the supplier you bought from - you can reclaim this as a tax refund
output VAT is the amount of tax you pay HMRC, calculated on the total value of the selling price to customer
W1- A good passes through three VAT-registered businesses. VAT = 25%.
Seller A produces a good worth $100.
Seller B purchases it and adds $100 in value.
Seller C purchases it and adds another $100 before selling to the final consumer.
Calculate for each seller: (i) input VAT, (ii) output VAT, (iii) net VAT remitted, and (iv) VAT-inclusive selling price.
Seller A | Seller B | Seller C | |
|---|---|---|---|
Pre-VAT selling price | $100 | $200 | $300 |
Input VAT | $0 | $25 | $50 |
Output VAT (25%) | $25 | $50 | $75 |
Net VAT remitted | $25 | $25 | $25 |
VAT-inclusive selling price | $125 | $250 | $375 |
Total VAT revenue: $25 + $25 + $25 = $75.
Final consumer price: $300 + $75 = $375.
W1 - What is a Retail Sales Tax? problems?
tax on the final retailer. problem is that if they avoid tax, then govt collects zero tax. That is the case for VAT.
W1 - what is a cascade tax?
A variation on VAT whereby businesses cannot reclaim input VAT. Therefore they are necessarily paying tax at every stage with no reclaims. This distorts the economic picture.
W1 - VAT, zero rating versus exempting
Zero-rating means output VAT is exempt, but can still claim input VAT
Exempting means the business does not pay output VAT nor is able to claim input VAT
W1 - what are the arguments for and against a VAT threshold?
Most agree that some VAT threshold is important because
reduces admin costs, compliance costs for small firms
encourages small businesses to thrive
However, some argue it should not be too high or should not exist because
Window Tax issue - lots of firms will choose to deliberately stay below the threshold
Firms below the threshold and choose not to pay VAT may suffer from incentive issues, because “downstream” firms cannot claim input VAT from them. They may need to lower prices to attract customers.
W1 - what are the ways of VAT fraud?
Overreporting input VAT or underreporting output VAT
Not reporting at all, or reporting but not paying to HMRC
W1 - how does VAT work on international transactions?
The exporter does not pay VAT, but is instead zero-rated (can claim input VAT) but the importer pays VAT. This makes sense becuase the importer is the consumer of the good.
W1 - what is carousel fraud? illustrate with an example
Carousel fraud is a form of missing trader VAT fraud exploiting zero-rated cross-border supplies and the input VAT credit system.
Example (Germany → France → Germany; 20% VAT assumed):
German Firm A sells goods to French Firm B for €1,000, with no VAT charged on the qualifying intra-EU supply.
Firm B (missing trader) sells them to French Firm C for €1,200 + €240 VAT, collects €240 but disappears without remitting it.
Firm C exports the goods back to Germany, charging 0% VAT, and claims a €240 input VAT refund.
The goods may circulate repeatedly, generating further fraudulent claims.
Government loss: €240 refunded/credited without the corresponding VAT having been remitted by B.
W1 - What is excess burden?
Excess burden is the same as DWL - it is equal to RL - Rs
Where RL is the lump-sum payment agents would be willing to make to avoid the tax
And RS is the revenue raised from the tax.
noting for lumpsum taxes there is no DWL
W1 - what is marginal excess burden? (MEB)
The marginal excess burden of taxation is the additional economic loss (or deadweight loss) to society caused by raising one more dollar or unit of tax revenue
W1 - What is the margin value of public funds? MVPF
The additional unit of social benefit brought about by one addtl pound of spending by govt
W1 - Hicks-Kaldor compensation principle
Idea that to maximise social efficiency, you probably need to make one or more parties worse off in order to compensate the ‘poorest’ parties. In turn, this would not be a Pareto outcome
W1 - Production efficiency theorem? What assumptions underpin?
Idea that revenue-raising taxes should NOT affect/distort production. Instead, final consumption shd be taxed
→ Constant returns to scale
→ Government has the freedom to set consumption and income taxes and address distributional concerns
→ no pre-existing production inefficiencies.
W2 - What are the different arguments surrounding higher/lower VAT on necessities like food?
Some economists like Ramsey suggest higher VAT on food, due to inverse elasticity rule meaning there’s less DWL
Other economists like Mirrlees say that we should do lower VAT, as poor households receive greater social welfare weight, so their consumption matters more
Stiglitz might argue a uniform VAT on all goods, not just food, and then take the tax receipts and redistribute it to the poor.
W2 - Corlett-Hague argument on taxing leisure-complementary goods. And what assumption is needed?
Corlett–Hague suggests that goods more complementary to leisure should face relatively higher commodity tax rates to counteract the labour-supply distortion from taxation.
This requires goods to differ in their complementarity with leisure.
W2 - Diamond-Mirrlees theorem: Apply it to trade tariffs. What is one counterargument?
The Diamond–Mirrlees theorem favours production efficiency and suggests taxing final consumption rather than intermediate inputs.
Therefore, they would argue against trade tariffs, especially for small countries as there will be economic distortions.
Counterargument: governments may lack the information or administrative capacity to compensate workers harmed by import competition. Adjustment costs, unemployment and imperfect competition may also undermine the theorem's assumptions. Tariffs can therefore sometimes be justified as second-best policies, although they introduce production distortions.
W1 - trade taxes vs excise taxes?
trade taxes are on imports/exports
excise taxes are on goods (e.g. alcohol, tobacco)
W1 - what key questions does public economics try to answer?
when should govts intervene? How shd they intervene? What effects shd the interveention have
W1 - when should governments intervene?
When the 1st welfare thm fails, i.e. markets inefficient
imperfect competition or incomplete markets
externalities
and
to redistribute wealth (2nd welfare thm)
W1 - how do govts intervene ? give 3
price mechanism (carbon tax, rent controls)
quantity constraints (fishing quotas, 3rd party car insurance)
direct or indirect provisions (like govt-run organisations, or NHS)
W1 - specific vs ad valorem tax?
specific tax: stays the same no matter how expensive the good is
ad valorem tax: is higher as the good gets more expensiveW1 w
W1 - what are the issues associated with raising taxes, in the real world? Discuss salience issues, market adjustment issues, and tax credits.
Salience - consumers may not realise the tax they pay, and may underreact
Markets adjust - like the Window Tax, etc. markets behave rationally and adjust. If taxes are levied on sellers, they may simply pass the cost to consumers
Tax credits - Inelastic party tends to bear both the costs AND the benefits of any tax credits.
W1 - what is the issue with Hysterisis?
hysterisis is the temporary reduction of tax in a good/service/
But empirical research shows that it may actualyl lead to its ultimate LT price being higher, making consumers worse off in the LR
W1 - is VAT progressive or regressive?
this is a trick question bc it depends on how you view it.
VAT when assessed as a % of total income is a regressive tax as poorer households tend to spend more of their total income in paying VAT
but VAT when assessed as a % of total expenditure is a progressive tax, as richer households spend more and therefore are taxed more in absolute amounts
What is a social welfare function (SWF), and what are its two key properties?
A framework for aggregating individual utilities into social welfare. W=U(U1,U2, …,Un) Two key properties:
Monotonicity: higher individual utility raises social welfare. Concavity: higher utility levels receive lower marginal social welfare weight, supporting redistribution.
What are the three main normative criteria used to evaluate tax systems?
Economic efficiency, fairness and administrative costs.
Utilitarian and Rawlsian SWFs
Utilitarian: maximise the sum of individual utilities.
Rawlsian: maximise the utility of the worst-off individual.
W2 - Draw the Rawlsian and utilitarian SWF indifference curves
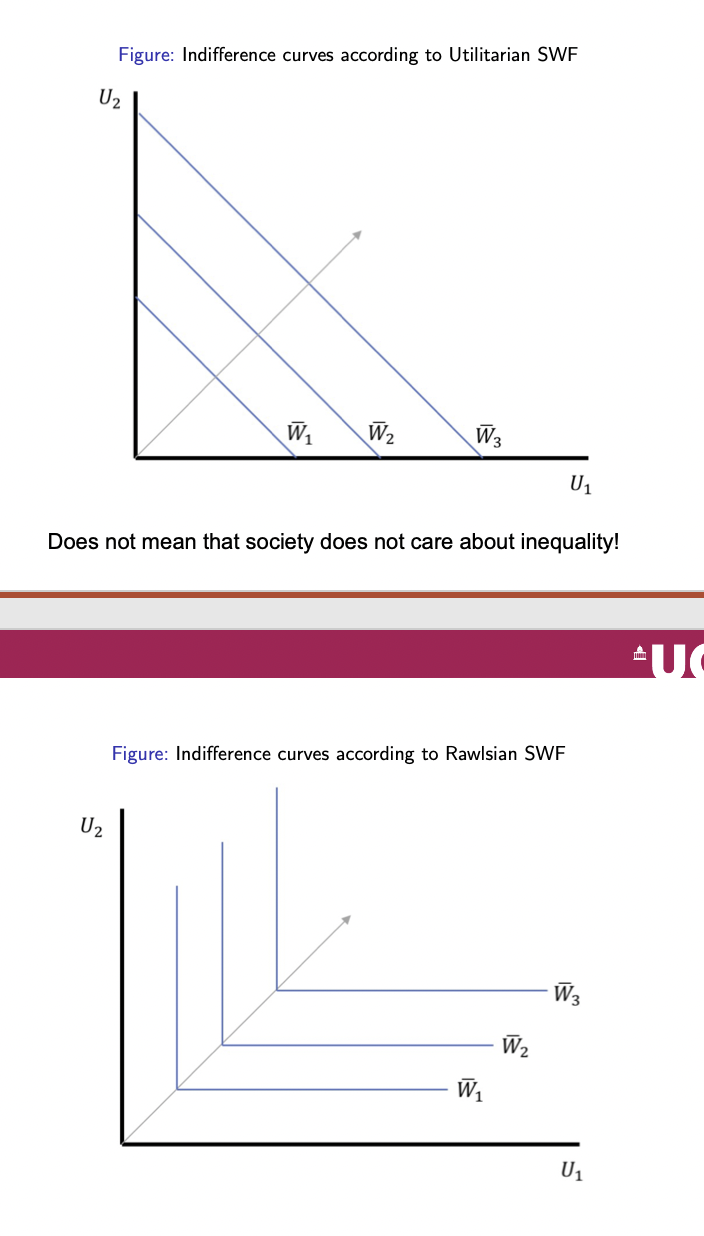
W2 - what is the ‘first best’ and ‘second best’ world models described in lectures? What is the ‘third best’?
First best = government has all information and can use lump-sum taxes based on individual endowments. efficient production and consumption, so governments can redistribute through lump-sum instruments
Second best = government does not observe endowments but observe true outcomes costlessly – eg sales, profits – and can use outcomes as tax base. production efficiency can still be achieved and is desired
Third best = governments does not observe endowments, but does observe true outcomes, but the info is costly.
under what conditions are VAT and RST equivalent?
in the first-best and second-best worlds, VAT and RST are equivalent
in the third-best world, VAT is better than an RST
W1 - draw the D/S curves in PC, with supply perfectly inelastic and perfectly elastic.
show how tax incidence falls depending on elasticity.
in PC world, the buyer/seller who is more inelastic will bear a greater portion of the tax incidence. when supply is perfectly elastic, the consumer bears 100% of the tax. when supply perfectly inelastic, the producer bears 100% of tax
W1 - Under monopoly, what determines the incidence of a per-unit sales tax?
Tax incidence depends on the shape/curvature of demand and the slope of marginal cost.
Linear demand + flat MC: Consumers bear 50%.
Constant-elasticity demand + flat MC: Tax is over-shifted; consumers bear more than 100%.
Linear demand + increasing MC: Consumers bear less than 50%.
Nonlinear demand + increasing MC: Indeterminate without more information.
W2 - what might a welfare approach fail to capture? I.e. what are some possible disadvantages to using a SWF? (list 3)
→ Doesn’t measure equality in opportunity
→ SWF doesn’t measure income equality. A system can be utility-maximised but very unfair
→ Commodity egalitarianism: Society may believe everyone deserves access to essential goods (e.g. healthcare, education), regardless of individual preferences or WTP. This cannot always be captured by a purely utility-based framework.
W2 - in a one-period model, where income comes solely from labour and consumption taxes apply uniformly to all goods, when will income taxes be the same as consumption taxes?
where t is the tax on consumption, and tau is the tax on income

W2 - in a two-period model, where income comes solely from labour and consumption taxes apply uniformly to all goods, where agents can also save their earnings in period 1, what result do we get when we tax consumption?
→ The tax does not change the relative price of consuming today versus consuming tomorrow, so saving is unaffected. However, the decision to supply labour is distorted
W2 - in a two-period model, where income comes solely from labour and consumption taxes apply uniformly to all goods, where agents can also save their earnings in period 1, what result do we get when we tax all income?
both labour supply and savings decisions are distorted
W2 - in a two-period model, where income comes solely from labour and consumption taxes apply uniformly to all goods, where agents can also save their earnings in period 1, what result do we get when we tax only labour income?
only labour supply is distorted, saving decision remains the same. This is the same result as only taxing consumption.
W2 - what are the flaws with the analyses done on the two-period model? (Recall that we said in a two-period model, we assume that a DWL in uniform tax on labour income = uniform tax on consumption)
→ we assumed no tax evasion is possible
→ we assumed no other sources of income are possible
W2 - In the two-period model: Who gains when we switch from income tax to consumption tax? Who gains when we switch from consumption tax to income tax?
Imagine a person who works in p1 and retires and consumes in p2.
When we switch from income tax to consumption tax - this person is worse off
When we switch from consumption tax to income tax - this person is better off
W2 - explain Ramsey’s tax problem - “How should the government choose tax rates across different goods to raise a fixed amount of revenue while minimising the welfare loss caused by taxation?”
State the assumptions and how Ramsey solves the problem
ASSUMPTIONS: assumes a one-period model with CRS, labour as only input, and no inefficiencies. We also assume only linear taxes are available
SOLUTION: individuals optimise based on their utility function, while the government maximises their welfare SWF. We check whether we are at an optimum by using pertubation: increase the tax on any good k by a small amount. It should NOT improve social welfare, or else we are not at an optimum.

W2 - explain the results from Ramsey’s findings from his investigation of “How should the government choose tax rates across different goods to raise a fixed amount of revenue while minimising the welfare loss caused by taxation?” by breaking down the equation and using an example to illustrate
The LHS of the eqn measures proportional reduction in compensated demand for good k caused by the taxation.
The RHS remains constant regardless of what good we look at.
Hence the tax optimum is so that the govt should set a tax s.t. proportional reduction in compensated demand is same across all goods.
If a tax reduces egg demand by 20%, it should also reduce milk demand by 20%. Or else it is not a tax optimum.
W2 - Explain the broad discouragement rule with an example
Ramsey's broad discouragement rule states that optimal commodity tax rates (which can, AND OFTEN WILL, differ across different goods) should equalise the proportional discouragement of compensated demand across all goods.
Example (assuming no cross-price effects): Suppose a 20% tax on hairbrushes produces a 10% reduction in compensated demand. At the tax optimum, the government should choose a tax rate on pizza that also produces 10% proportional discouragement of compensated demand. And so on for all other goods.
Key takeaway: Different goods may require different tax rates to achieve equal discouragement.
W2 - How would Ramsey respond to a uniform commodity tax?
He would likely say that it is unoptimal! He showed the result of broad discouragement rule, which inherently encourages different tax rates for different commodities s.t. the reduction in compensated demand is proportionally same.
W2 - Baumol and Bradford: What did they show with Ramsey’s rule?
They showed that with no cross price effects, we have the inverse elasticity rule. I.e. that govts should tax inelastic goods at a higher rate than elastic goods.
They also showed broad tax base rule. Taxing many goods at a low percent should reduce overall DWL than taxing a few goods heavily.
W3 - draw the situation with an externality. (MPC/MSC and MSB)
MSC will be on the left /higher than MPC. The intersection between MSB and MSC is the society optimum, but often production happens at where MPC=MSB, i.e. too much.

Identify the variables in the graph (W3) - assuming supply is perfectly elastic. Who bears the tax?
pt - p0 = size of per-unit tax
Area A = govt revenue from the tax
Area B+C = benefit from correcting the externality
Area C = area lost from the reduction in consumption
Area B = net welfare gain from introducing the tax
D1 = MPB
D2 = MSB
note that for an internality, the bearer of the “externality” is the individual themselves
The tax is entirely born by the consumers - since supply is perfectly elastic
W3 - what is the regressive/progressive nature of internalising an internality like a sugar?
The financial cost for internalising an internality is likely regressive - poorer households tend to pay more because they tend to consume more sugar
But the welfare benefit from internalising is likely progressive - poorer households may not have the information to know not to consume lots of sugar
i.e. they may pay more in “area A” but gain more from “area B”

Identify the variables in the graph (W3) - assuming supply is upward sloping. Who bears the tax?
note that the tax does not fully internalise the externality, hence why we don’t intersect at the D2m and S point.
X = transfer from producers to govt
Y = transfer from consumers to govt
Z = welfare gain from correcting the externality

W3 - what the axioms that tax policy makers typically focus on when designing a tax? what are some of the typical challenges associated?
ensuring it is
→ economically efficient
→ fair
→ low admin costs
challenges:
→ we cannot rely on the Pareto efficient point of production. there will be losers and winners at that point
→ we might want to have transfers from rich to poor, but this is often infeasible (who is “the poor”? How will we transfer?)
W3 - what are the conditions for a SWF? Name two extremes of SWFs
Monotonicity (first derivative is positive)
Concavity (second derivative is negative)
You have two extremes of SWFs - the utilitarian SWF which maes the case that everyone’s utilities are of equal weight (U1 + U2 + … )
Then you have the Rawlsian SWF, where we try to maximise the utility of the poorest / lowest utility person.
W3 - draw a basic diagram of indifference curves - Utilitarian SWF vs Rawlsian SWF
pictured is Rawlsian. A Utilitarian SWF should be lines going down (decreasing linear)

W4 - What are excise duties? Relationship between VAT and excise duties?
Indirect taxes paid on manufacturing/production/importation of goods (usually those that create EXTERNALITIES)
→ Legally paid by supplier, but buyer can still of course bear the cost
→ VAT is usually charged on the excise-duty-inclusive price.
W4 - What is the definition of an externality? Is competition for a scarce resource an externality?
When an agent’s action has spillover effects to others and the agent does not bear the benefits/costs of the spillovers.
NOTE: competition for a scarce resource through the price (competing on price) is not an externality and is simply a result of the market working its forces
W4 - If the first welfare theorem holds, what can we say about MPC, MPB, MSC, MSB?
If the first welfare theorem holds, that means the competitive equilibrium is also socially optimal. I.e. MPC=MSC=Supply, and MPB=MSB=Demand

W4 - Consider the simply economy of cars. A consumer has utility u(x) with wealth m and price of car p. Firms have cost c(x). External costs are created from use of cars at d(x).
Write the utility function of the consumer, the profit function of the firm
Then write the Welfare function.

W4 - apply the Perturbation argument to the case of a negative externality
a neg externality is when consumption is greater than what is socially optimal.
we can thus increase social welfare by decreasing consumption Q by a small amount
W4 - What are some shortcomings of the MPB/MSB/MSC/MSB model?
difficult to measure the shape and slope of these, as we don’t know the exact profit functions nor utility functions of all agents
W4 - What is the Coase Theorem? (2 conditions)
idea that mkt participants can internalise externalities without much govt intervention
as long as governments assign clearly property rights to one/some parties, and
there is an opportunity for these parties to bargain costlessly in a market
W4 - key criticisms of Coase Theorem?
there are high transaction costs in bargaining
how does the govt decide who owns ‘the property right’?
W4 - what is a Pigouvian tax?
a tax that corrects for the marginal external cost
this tax is t = d’(x)
where d’(x) is the marginal external cost at the socially optimum point
W4 - what is the polluter-payer principle and why is it fallable?
the principle (which is politically popular) says the polluter should ‘pay’ for their damages caused to the environment
economics however, tells us that the incidence is shared between buyers and sellers, depending on elasticity
W4 - what happens when a Pigouvian tax is too small? Too big?
too small is not necessarily a problem as it still reduces the DWL
too big (the tax discourages production BEYOND the point of coverage of DWL) is not so good
W4 - what is Sandmo’s additivity property?
the optimal tax, in a world with externalities, is = Ramsey tax + Pigouvian tax for the externality good

W4 - explain the mathematical equation presented here for a Ramsey tax with externality.
t’’j is equal to t’j for “all other goods” (non-externality goods) - we arrive back at the Ramsey tax without externality
t’’j is equal to the result pictured left for the externality good. t’1 is defined as total tax levied on the good (by additivity, equals the Ramsey tax + Pigouvian tax). the Pigouvian tax is defined as: d’(X1)/λ
you can see that the Pigouvian tax cancels out, and we also arrive back at Ramsey tax!
Intuitively: t’’j is total tax minus pollution correction. Hence it is just equal total tax for the no-externality case, and equal Ramsey tax for the externality case.
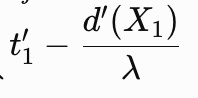
w4 - How does Sandmo's targeting principle generalise beyond the representative-agent Ramsey model? (GIVE AN EXAMPLE)
The targeting principle continues to hold under the relevant extended-model assumptions when:
Individuals are heterogeneous: Environmental externalities should still be targeted directly, while distributional concerns can influence taxes and transfers.
Optimal nonlinear income taxation is available: Income taxation can address redistribution but cannot directly correct pollution, so corrective environmental taxes remain justified.
Example: Tax fuel according to its greenhouse-gas emissions, rather than simply taxing miles driven. A mileage tax may nevertheless be appropriate for other externalities, such as congestion.
W4 - what is the double dividend fallacy?
Environmental taxes generate a first dividend by correcting negative externalities. Their revenue may finance reductions in other distortionary taxes, but this does not automatically generate a second efficiency dividend.
A second dividend is only possible if the pre-existing tax system was suboptimal — for example, the polluting good was under-taxed relative to its Ramsey-optimal rate, while other goods were over-taxed.
W3 - when discussing corrective taxes, what is heterogeneity problem?
Idea of non-allocational efficiency. The person that values the item (e.g. housing) the most, is not necessarily the one who gets it. This is because the price ceiling on the good makes it affordable to everyone.
IN context of corrective taxes, it pertains to how some firms have higher abatement costs than others. This leads to allocational inefficiency when you set a quantity restriction, as lower cost firms could abate more
W3 - In the case without heterogeneity, write the equation for the social optimum amount of pollution and maximise the function. (Assume marginal benefit for abatement is 10)
Social optimum = environmental benefit - abatement cost
W = 10q - c(q)
max(10q - c(q)) → 10 - c’(q) = 0
c’(q) = 10
W3 how has governments solved the abatement with heterogeneity problem? what assumption is needed?
Using “cap and trade” mechanisms. So that those who can abate at a low cost can abate more, and then sell credits to high cost firms.
assume firms are price takers in abatement mkt
W3 - what is the rule to determine whether you shd be a buyer or seller in the abatement market?
If MCabate < MBabate at the optimum pt, you should be a seller. You should be a buyer vice versa

Draw the case of abatement/cap and trade following the Kyoto Protocol - labeling East and West Europe’s gain from trading
The gain from trading is W4 and E3

Faced with uncertainty, what are the arguments for/against Pigouvian taxes vs cap and trade?
Pigouvian taxes: You may abate way more or way less than expected due to costs being unknown. However, in the case that you abate way less, (since abate costs are high) the costs are as they are - and not forced upon producers
Cap and trade: You know for certain how much you will abate, but in the case that costs are very high to abate, you are forcing such costs into the market.
Faced with uncertainty, under what extreme case will a Pigouvian tax never generate DWL? What about a Cap and Trade
If the MEB is flat/constant, a Pigouvian tax never generates a DWL, since t=MEB
If the MEB is perfectly vertical, a cap and trade never generates a DWL
What are non-pecuniary incentives? give an example
Is pecuniary or non-pecuniary incentives better for social efficiency?
Ways to influence behavior besides taxation or subsidies
→ for example, public shaming, or encouragement (textbook example is telling neighbor whether you voted in US election)
Is pecuniary or non-pecuniary incentives better for social efficiency?
→ Non-pecuniary can be thought of as a “discriminating” tax proxy, as those who feel shamed more will act more strongly than those who don’t
→ Pecuniary incentives cost money. Pecuniary taxes raise revenue so in the tax case, a pecuniary tax is good → can be used for transfers, other projects. But a non-pecuniary incentive is good as it doesn’t cost the government anything.
What is an internality?
when agent fails to fully internalise effect of their own actiosn on their own welfare
What are the curves named in internalities? Where is social optimum?
People have “perceived” Marginal Private Benefit and “actual/true” Marginal Private Benefit
and same for private costs.
The social optimum is where actual/true MPB meets actual/true MSC
What is paternality in the case of internalities?
When government intervenes on a perceived “internality”, even though it is not really an internality - as the agent reached that decision from rationality (even if the government may think it’s “suboptimal” - the govt may be imposing their own views)
Correction of internalities via information
Some internalities may arise from lack of information - rather than correct for these internalities using a tax/subsidy or other government policy, one can imagine education to increase information can solve the internality
Common reasons for internalities? (Name 2) What taxes work well in each reason?
Myopia (e.g. retirement) - individuals misperceive their welfare, but still respond well to corrective policies - e.g. can impose sin taxes
Switching between rational and irrational self (e.g. drunk vs sober) - rational self buys good if true benefits outweigh true costs, irrational self buys good even when costs are sky high - e.g. can impose delays like 1 week between gun sale and delivery to regulate people emotions
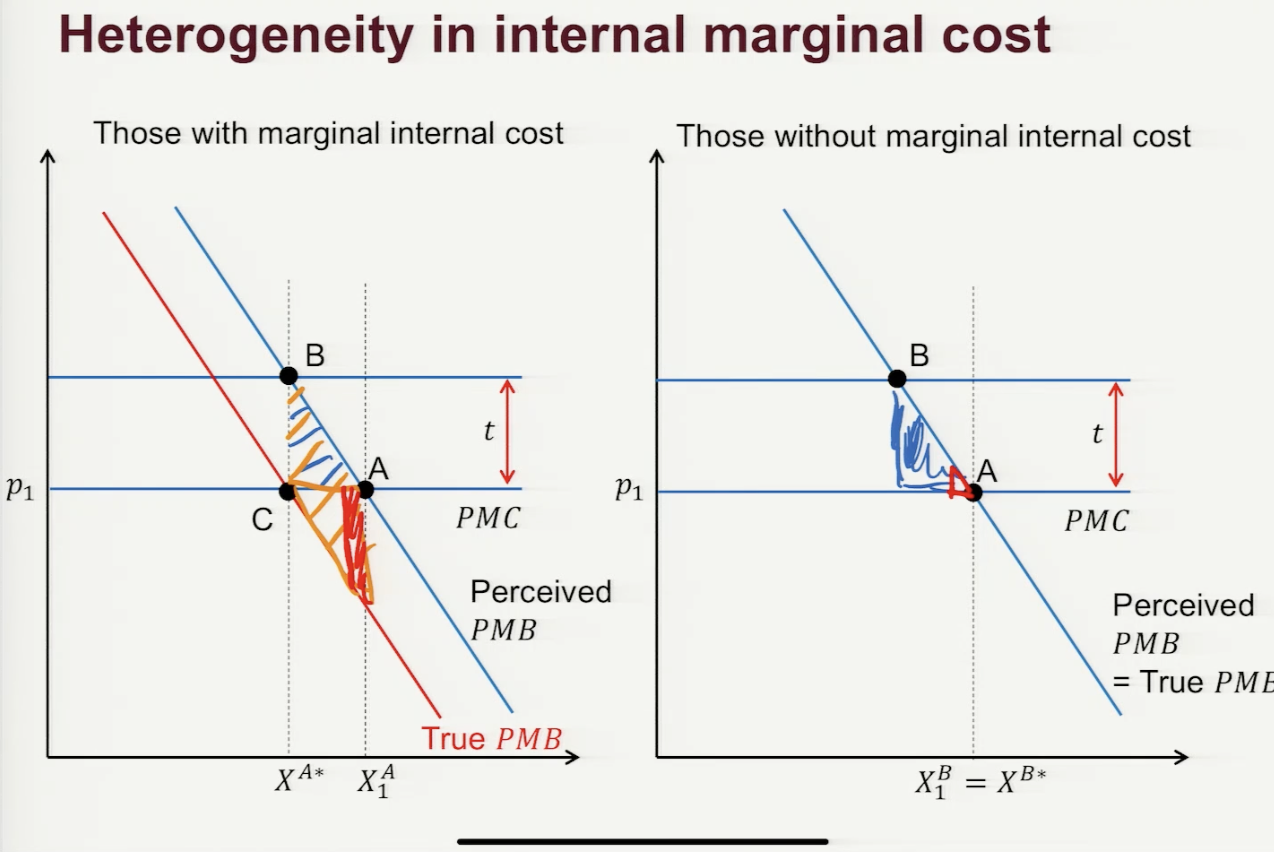
Heterogeneity in the case of internalities? Explain then draw a diagram.
This is when some people make mistakes and others don’t. IDeally, you should only impose corrective policies on those who make the mistakes.
If you impose blanket policies, you may hurt people that don’t make those mistakes

In the case of heterogeneity and internalities, why is imposing a small tax likely a benefitial thing? Explain with a graph
Although heterogeneity w internalities means some people are making mistakes (perceived MPB is higher than true MPB) whereas others are not (perceived = true MPB), a small tax can increase welfare.
The DWL from taxing the “Rational” consumer is less than the gain in surplus from taxing the “irrational” consumer. (See on left the red areas)
Intuition for why correcting an internality for low-income households is socially beneficial? Versus an externality.
Note that any “gains” from reducing DWL go to society in the case of externalities. But in the case of internalities, they go to the person!

Explain what sigma means. Then define g(Z) and spref and interpret the covariance term.
Progressivity of bias correction is essentially asking who benefits more from having their behavioural mistakes corrected? If it’s poor people, this variable is higher.
g(z) is the welfare weight - how you value your SWF
spref asks how much of consumption of goods in scope of sin tax is attributable to preferences?
Covariance term is asking: Do people with higher social welfare weights (typically poorer people) consume more sugary drinks because of their preferences? If yes, reduce the tax

Assume no redistributional motive, what does the equation simplify to?
The cov term disappears, the sigma disappears. We then arrive at t=average marginal internal cost + marginal external cost
equiv to Pigouvian
What did researchers find about the sugar tax?
Conclusion?
To check whether poorer households tend to prefer consuming more of sugary drinks, they gave these households a cheque of free money.
Found that all households, at any income level, consumed more, so it was not an inferior good but a normal good. Therefore the researchers showed that consumption of sugary drinks comes from preferences and not income.
→ In ‘redistributive' motive world, govts should be subsidising sugary drinks for financial reasons. But they also showed that poor households respond more to the tax, have higher internality benefit.
Conclusion: a tax that looks regressive in monetary terms may be progressive in health terms
What are the trends in capital income inequality and top income inequality?
Both capital income inequality and top income (vs low income) has increased over the past decades.
English-speaking countries experienced “u-shaped” curve (high in the 1920s, dropped in 60s-80s, back up in the 2000s). Whereas countries like France, Japan, Sweden, experienced “L-shaped” (previously high, now low)
What is the function that maximises the tax revenue on the Laffer curve? (assume the tax is linear)
NO need to derive this. Explain that as elasticity increases, tax revenue that maximises falls
