ch4 - preparing financial statements
 Call Kai
 Learn
 Practice Test
 Spaced Repetition
 Match
 Flashcards
 Knowt Play
1/9

There's no tags or description
Looks like no tags are added yet.
Name | Mastery | Learn | Test | Matching | Spaced | Call with Kai | Chat |
|---|
No analytics yet
Send a link to your students to track their progress
10 Terms
Gross Salary = £10,000
PAYE = £2,000
Employee NIC = £500
Employer NIC = £700
1) what is staff cost
2) what is the net salary
3) Tax owed to HMRC
4) Double-entry
1) 10000 + 700 = 10,700
2) 10,000 - 2000 - 500 = 7500
3) 2000 + 500 + 700 = 3200
4) -
dr wages expense 10700
cr cash 7500
cr income tax payable 3200
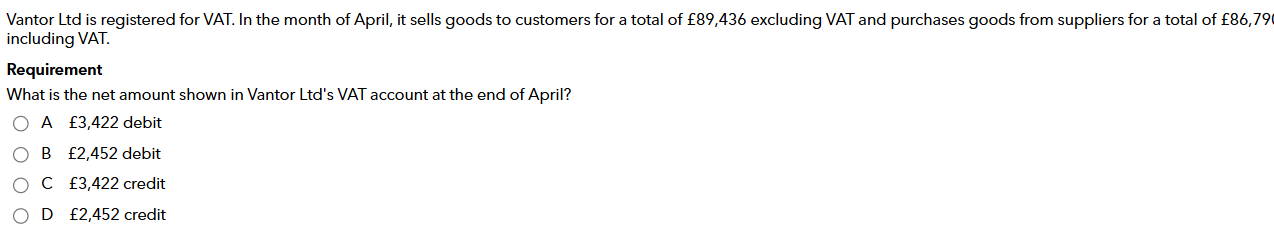
C)
1) sales excludes VAT: 89436 × 0.2 = £17,887
2) purchases include VAT: 86790 × 20/120 = £14465
17887 - 14465 = credit as this is amount owed to HMRC
which of the following would be a credit balance in the trial balance?
bank overdraft
drawings
purchases
delivery outwards
A) bank overdraft

C)
revenue (89,400) - purchases (69,600 × 100/120 as VAT registered so don’t pay the VAT) = 31,400
*VAT registered businesses record sales and purchases excluding VAT when calculating profit
if it weren’t VAT registered it would have been:
89400 ( ( no VAT) - 69600 keep full amount) = 19800

1) opening balance: cr 3450 trade payables
2) purchased goods on credit: cr 5100
3) payment to credit suppliers: dr 4200
(3450 + 5100) - 4200 = 4350

1) Debits: non-current assets (85000 + 7000) + inventory (400) + prepayments (2000) = 98,000
2) Credits: trade-payables (3000) + bank loan (15000) + accumulated, depreciation non-current assets (15000) + accruals (1000) + bank overdraft (2000) = 36000
3) 98000 - 36000 = 62000
Which of the following is the correct accounting treatment of a trade discount received from a supplier?
It is recorded as income in the statement of profit or loss.
It is deducted by the supplier from the list price and the net invoice amount is recorded as an expense and as a payable.
It is recorded in the cash payments.
It is recorded in the journal.
It is deducted by the supplier from the list price and the net invoice amount is recorded as an expense and as a payable. (1 Mark)
Tallinn Ltd purchased goods on credit from Oslo Ltd. When Tallinn Ltd recorded the purchase invoice in its ledgers, it did not expect to take advantage of the early settlement discount terms.However, Tallinn Ltd has now decided to take advantage of the early settlement discount terms and make early payment to Oslo Ltd.
What double-entry should Tallinn Ltd use to record the payment made to Oslo Ltd (ignore VAT)?
Debit: Cash at bank, Debit: Purchases, Credit: Trade payables
Debit: Trade payables, Debit: Purchases, Credit: Cash at bank
Debit: Trade payables, Credit: Cash at bank, Credit: Purchases
Debit: Trade payables, Credit: Cash at bank
Debit: Trade payables, Credit: Cash at bank, Credit: Purchases (1 Mark)
AK Ltd sold goods on 30 days credit to BN Ltd for £300. Included in the terms and conditions of sale is the opportunity for BN Ltd to take advantage of 5% early settlement discount if the invoice is paid within 10 days of invoice date. At the point of raising the invoice, AK Ltd expected BN Ltd to take advantage of the early settlement discount terms offered.
BN Ltd subsequently paid the amount due within 30 days of invoice date, but not within the time period eligible for the early settlement discount.
What accounting entries are required to be made by AK Ltd to properly account for the amount received from BN Ltd?
Debit Cash £285, Credit Revenue £285
Debit Cash £300, Credit Receivables £285, Credit Revenue £15
Debit:Cash £300, Credit Receivables £300
Debit Cash £285, Debit Revenue £15, Credit Receivables £300
Available Answers
Debit Cash £300, Credit Receivables £285, Credit Revenue £15 (1 Mark)
Expected BN take advantage of settlement (300 × 0.95) = 285
receivables 300 as they paid that in the end, excess being treated as cash sale for £15 (cr revenue)
he following was extracted from the ledger accounts of a business:
| £ |
Net pay to employees | 150,000 |
PAYE | 50,000 |
Employer’s NIC | 20,500 |
Employees’ NIC | 17,500 |
What was the wages expense for the month?
£200,000
£150,000
£238,000
£188,000
wages cost or staff cost = gross salary + employer NIC
1) gross salary = net pay + PAYE + employee NIC: 150000 + 50000 + 17500 = 217,500
2) gross salary + employer NIC: 217,500 + 20,500 = 238,000