financial acounting
 Call Kai
 Learn
 Practice Test
 Spaced Repetition
 Match
 Flashcards
 Knowt Play
1/11

There's no tags or description
Looks like no tags are added yet.
12 Terms
types of buissneses
NOT SEPERATED: meaning if the company has debts its payed out of pocket.

accounting equation
assets = capital + liabilities
CAPITAL = AMOUNT INVESTED MY OWNERS
NCA VS CA
NCA: an asset held for more than 12 months not ment to be sold
CA: an asset held for less than 12 months that will be converted to cash
NCL VS CL
NCL: liability due after more than 12 months
CL: liability due before 12 months
HOW TO MAKE BALANCE SHEET
BRACKETS MEAN MINUS
1)START WITH PROFIT/LOSS
2)start with incomes
sales
(returns) = income
3)cost of sales
opening inventory
purchases
(purchase returns) (you gain money from these)
carriage inwards
(closing inventory)(gain money since asset)
all equals === cost
4) find gross profit
gross profit = income - costs (should be positive)
5) sundary income if any
rent recived ( add this to final profit)
6) expenses
carrige out
salaries
rent paid
motor expenses
sundary expenses
all equals to expenses
7)find net profit
net profit = gross profit - expenses + sundary income
8) START BALANCE SHEET
9)start with assets non current then current
NCA
motor vehicles
future fitting
CA
closing inv
recivables
cash in bank
cash in hand
10) NCA + CA = ASSETS
11) capital
opening capital
net profit (FROM SOPL)
drawings
12)NCL AND CL
CL
payables
13) does assets = capital + liabilities
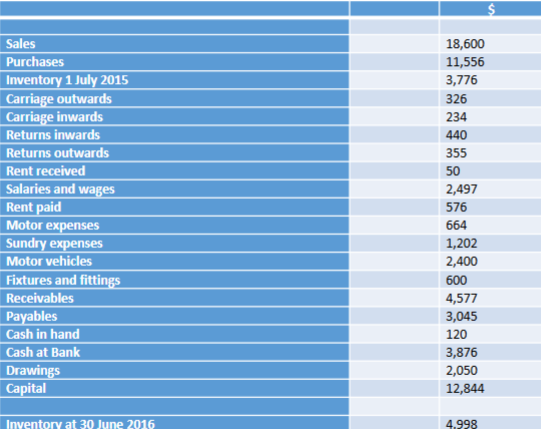
how sopl, how to know where each one goes
1. Revenue (Sales)
This is the money earned/lost from selling/returning goods or services.
2. Cost of Sales
These are the costs directly associated with buying or producing the goods sold.
3. sundry Income
These are earnings other than the main sales revenue.
4. Expenses
These are the costs of running the business that are not included in cost of sales.
how to know where each thing goes in sofp
1. Non-current assets
These are assets the business expects to keep and use for more than one year.
2. Current assets
These are assets expected to be sold, used or converted into cash within the normal operating cycle or generally within 12 months.
3.Capital
The amount of money or resources invested in a business by its owner
4. Current liabilities
These are amounts the business owes that are generally due within 12 months.
5. Non-current liabilities
These are amounts owed that are generally due more than 12 months in the future.
capital vs revenue expenditure
capital: purchase of a NCA
revenue: costs related to a transaction, eg repairs/ maintenance
whats a nominal ledger and how to use it
when you put the 2 effects on debit and credit side of a transaction
DEBIT : expenses, assets, drawings
CREDIT: liabilities, income, capital
WHEN INCREASING DR left AND CR right
total DR should be equal to total CR

make a nominal ledger for the first 6

whats a t acount and how to make one (cash acount where trader makes 10000 in sales but looses 6000 in purchases)
t acount is too see what goes into an aocunt and what comes out
FOR CASH ACOUNT, if cash increases credit, decreases debit
for the question above
sales is on left, even tho its income,since its a cash acount and cash(assets) aer increasing, while purchases is right since cash is decresing hence credit


how to do brought forward carry forwards for this
1) choose the bigger value and thats the total for both sides
2)find differance 10000- 6000 = 4000 thats balance C/F and u put on lower side
3)for balance B/F, you put it on the opposite side of C/F and its same value as C/F
