W5 & W7 - Audit Procedures and Evidence
 Call Kai
 Learn
 Practice Test
 Spaced Repetition
 Match
 Flashcards
 Knowt Play
1/27

There's no tags or description
Looks like no tags are added yet.
28 Terms
What are the stages of the audit process?
Acceptance and continuance
Planning, risk and response (W3)
Execution
Completion and reporting
Explain the execution stage of the audit process.
The auditor performs test of controls and substantive tests to gather audit evidence to address the risks of material misstatement identified during phase 2.
How do we collect sufficient appropriate audit evidence?
Substantive procedures: Test of detail, substantive analytical procedures
Test of controls: evaluating the operating effectiveness of a firm's internal control systems
What are substantive tests designed to?
Designed to detect material misstatement at the assertion level.
What are test of controls designed to?
Designed to evaluate the operating effectiveness of controls in preventing, or detecting and correcting material misstatement.
Can auditors give absolute assurance?
No, highest is reasonable assurance as they are not testing all the account balances.
Auditors use a sampling process.
What are sampling procedures?
Two ways:
Statistical sampling
Non statistical sampling
What is statistical sampling?
Can use
Random selection ( using random number geenerator)
Systematic selection ( fixed selection interval with a randomly selected first one)
Monetary unit selection
What is Non statistical sampling?
Auditor uses their own judgement to decide what to pick as a sample
E.g. block selection- all the transactions in a particular week
Haphazard selection- there is no structure to it but should not be too predictable and avoid bias
What are the sources of evidence for sales?
Sales orders
Sales day book
Customer contracts
Revenue control account
Goods delivery notes
Sales invoices
What are the substantive tests we can use to test assertions for sales/revenue?
Cut-off: Select a sample of Goods delivery notes both pre- and post-year-end and trace these to sales invoices in the correct accounting period.
Presentation: Complete the disclosure checklist to ensure that all the disclosures relevant to revenue have been made and comply with IFRS 15.
Completeness: Obtain a listing of sales revenue from the sales ledger and agree the totals to the general ledger and the financial statements
Occurrence: Select a sample of sales transactions recorded in the sales ledger and agree the details back to a sales invoice, Goods delivery notes and customer order.
Accuracy: Select a sample of sales invoices for larger customers and recalculate the discounts allowed.
What are the key auditing words we must use???
Inspection
Observation
Inquiries
External confirmation
Recalculation
Re performance
Analytical procedures
What are the sources of evidence for receivables? ( credit sales)
Auditors are concerned with whether the client really owes this money and whether it can be recovered.
Sales invoice
Goods delivery notes
Receivables circularisation letters
Post-year-end bank statements
Policy allowance for doubtful receivables
What are some substantive tests we can perform to test the assertions for receivables?
Presentation: Complete the disclosure checklist to ensure that all the disclosures relevant to receivables have been made
Completeness: Obtain a list of trade receivable, recalculate it and agree to the general ledger and financial statement.
Existence: Select a sample of customer and send circularisation requests ask them to confirm the balances they owe the company
Valuation: Calculate average receivable days and compare this to prior year. OR inspect the aged receivables report to identify any slow-moving balances and discuss with management to assess whether an allowance is necessary.
Receiving payment for a year-end receivable proves that the underlying scale was genuine? True or false
False
E.g. round tripping ( It looks like a sale has been made because money has been received but that may not be the case)
What is customer circularization?
Obtain permission from the client first and get details
Auditors select clients based on material balances

What is positive circularisation?
The customer can either reply or not reply.
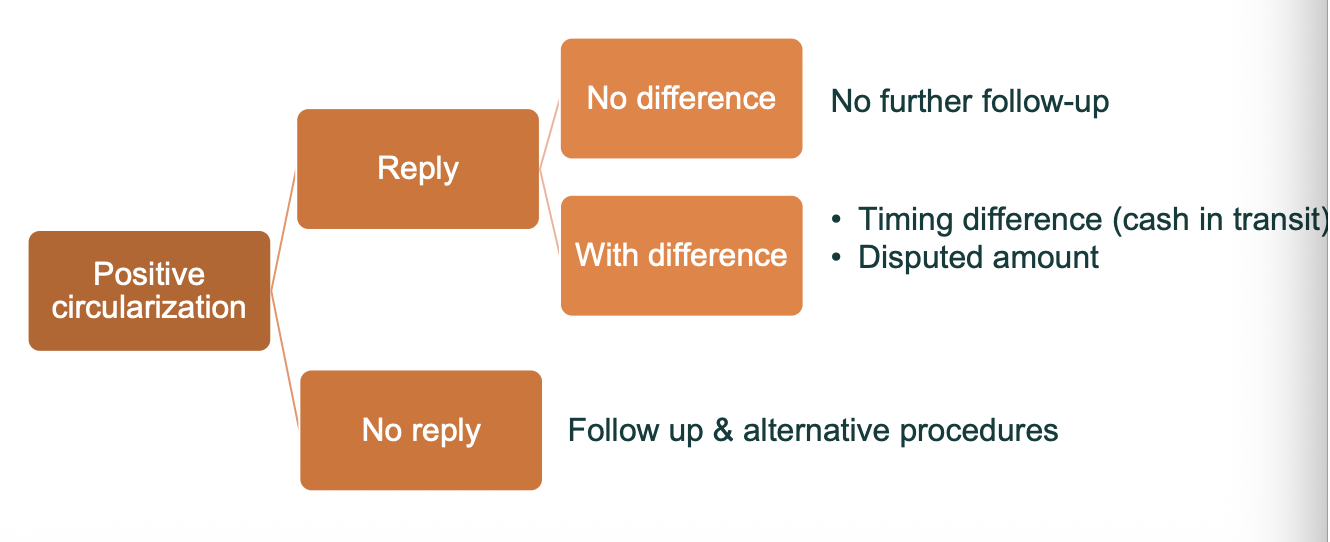
A credit sale is made and the customer confirms that they owe £10,000 at year-end. This proves the full amount is recoverable. True or fasle?
FALSE
confirms existence not whether its a recoverable amount.
WHat are the sources of evidence to confirm cash & bank?
Bank statement
Bank confirmation
Bank reconciliation
Physical cash held at the clients’ premises
What is the substantive procedure to test the assertions for a bank statement?
Existence, Accuracy & Completeness: Agree selected receipts and payments on the bank statement to the cash book and investigate differences
What is a bank confirmation?
The auditor will directly reach out to the bank and ask for confirmation and the bank will respond to the auditor.
Obtain the client’s authorisation for the bank to release information
Obtain the bank’s response directly, under the auditor’s control
External, direct written response, in paper or electronic form
Request confirmation of all accounts and balances held with the bank
What are some substantive tests to check the assertions for bank reconciliations?
Completeness, Classification & Presentation: Check that accounts and liabilities identified in the confirmation are appropriately recorded and presented.
Accuracy & Existence: Agree confirmed bank balances shown on the year-end reconciliations
What is a bank reconciliation?
Explains differences at a specific date between the bank statement balance and the bank balance in the client’s cash book.
What are the substantive tests to check the assertions for bank reconciliation?
Existence, Accuracy, Valuation & Completeness:
Recalculate the bank reconciliation to check arithmetic accuracy
Agree the balance per bank shown on the reconciliation to the year-end bank statement and bank confirmation.
What are the substantive tests to check the assertions for cash & bank?
Existence, Accuracy:
Cash count: Calculate the cash, agree the total to the cash book/general ledger and investigate any differences.
All cash balances to be counted simultaneously where practical
Auditors must be accompanied by a member of the client
What are the sources of evidence for inventory?
Inventory
Inventory count sheets
Purchase invoices
Goods received notes
Sales invoices
Good delivery notes
Aged inventory listing
What are the substantive procedures to check the assertions for inventory?
Cut off: Select a sample of good received notes and goods delivery notes around the year-end and trace to the year end inventory balance
Rights and obligations: Inspect the ownership documents such as purchase invoices. Can also ask for an external confirmation if goods are stored with a third party and ask what goods are held, what quantity and what condition.
Completeness: Trace test counts to the inventory listing ( inventory record)
Existence: Observe physical inventory counts
Valuation: Obtain and inspect a copy of the inventory listing and agree the totals to the general ledger. Recalculate the inventory listing to ensure it is mathematically correct
An auditor selects items from the inventory listing and locates them in the warehouse. This primarily tests completeness and rights and obligations.
True or false??
False!
This tests existence.