acttax3 le1 ot
 Call Kai
 Learn
 Practice Test
 Spaced Repetition
 Match
 Flashcards
 Knowt Play
1/59

There's no tags or description
Looks like no tags are added yet.
60 Terms
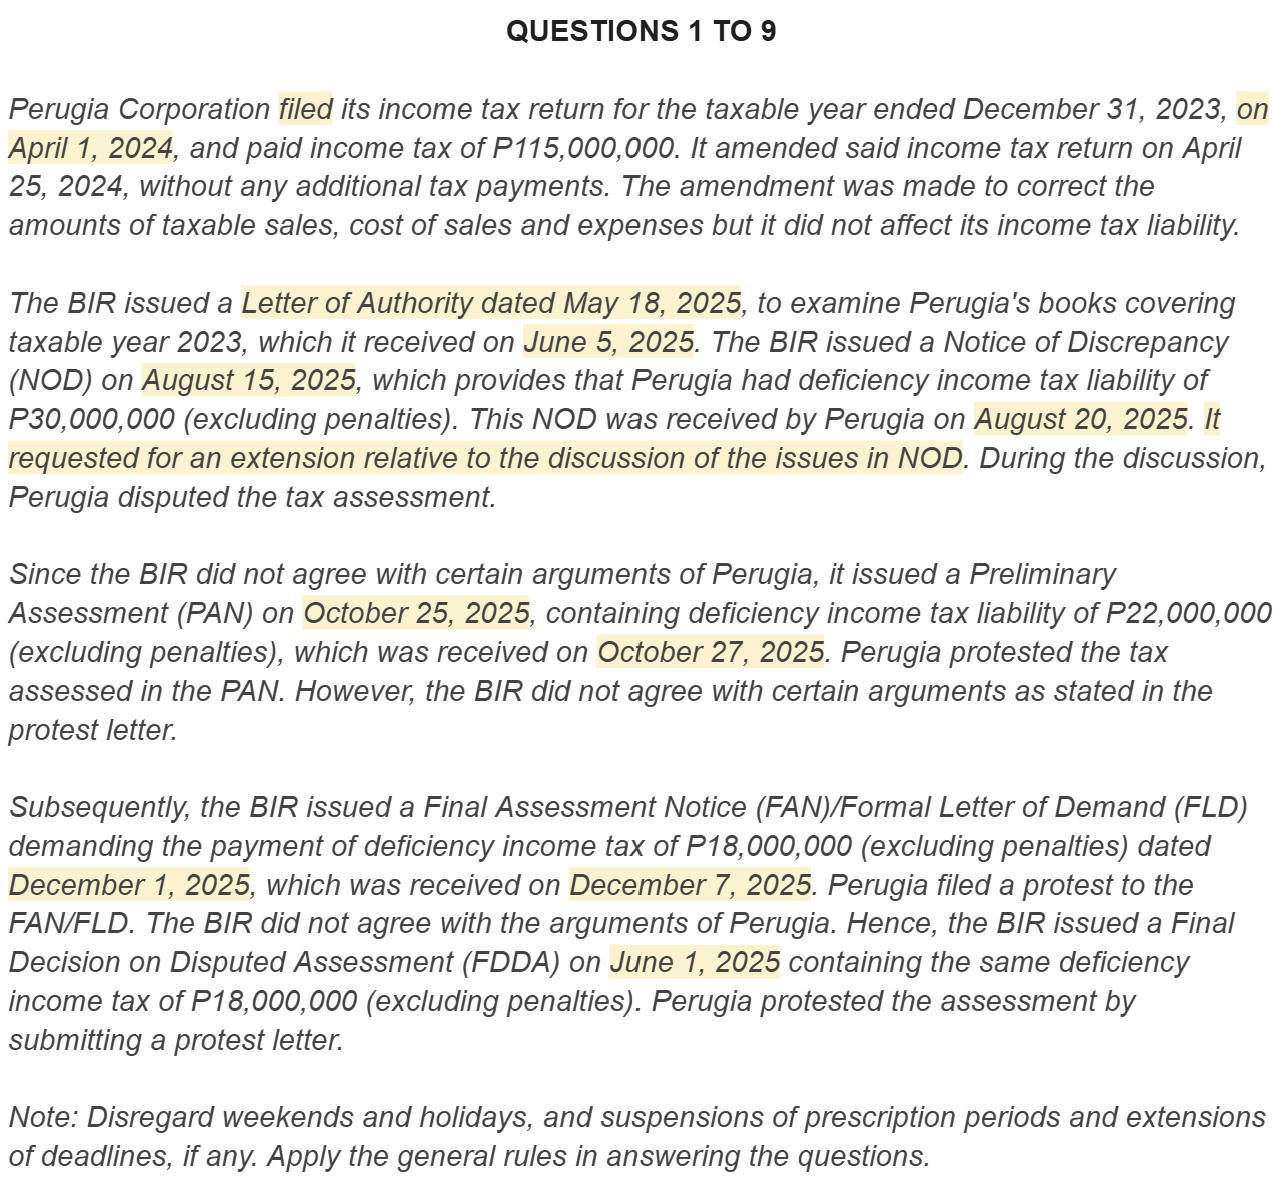
Question 1: Prescription Period for Assessment
The BIR can assess Perugia's income tax liability for the year ended December 31, 2023 until:
a. December 31, 2026.
b. April 25, 2027.
c. April 15, 2027.
d. April 1, 2027.
e. None of the choices
b
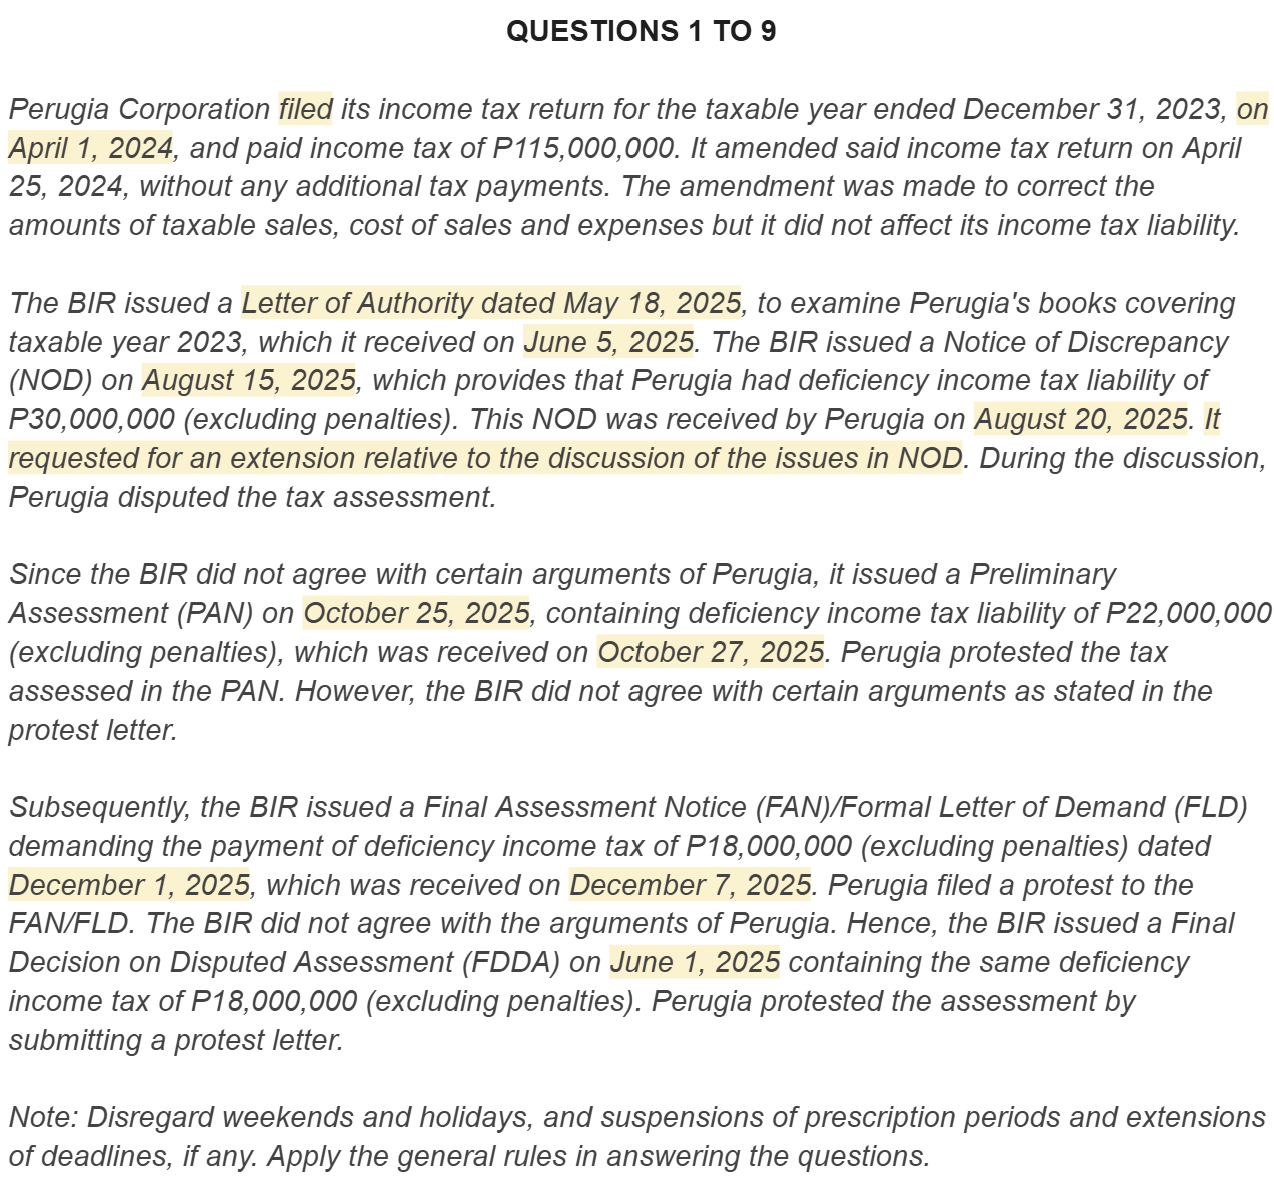
Question 2: Validity of LOA Service
Was the LOA served by the BIR within the prescribed date?
a. No, since it was served on June 5, 2025. The BIR is given until June 4, 2025 to serve the LOA. The BIR revalidated the LOA to address the issue.
b. Yes, since it was served on June 5, 2025. The BIR is given until August 18, 2025 to serve the LOA.
c. Yes, since it was served on June 5, 2025. The BIR is given until June 17, 2025 to serve the LOA.
d. Yes, since it was served on June 5, 2025. The BIR is given until June 7, 2025 to serve the LOA.
c
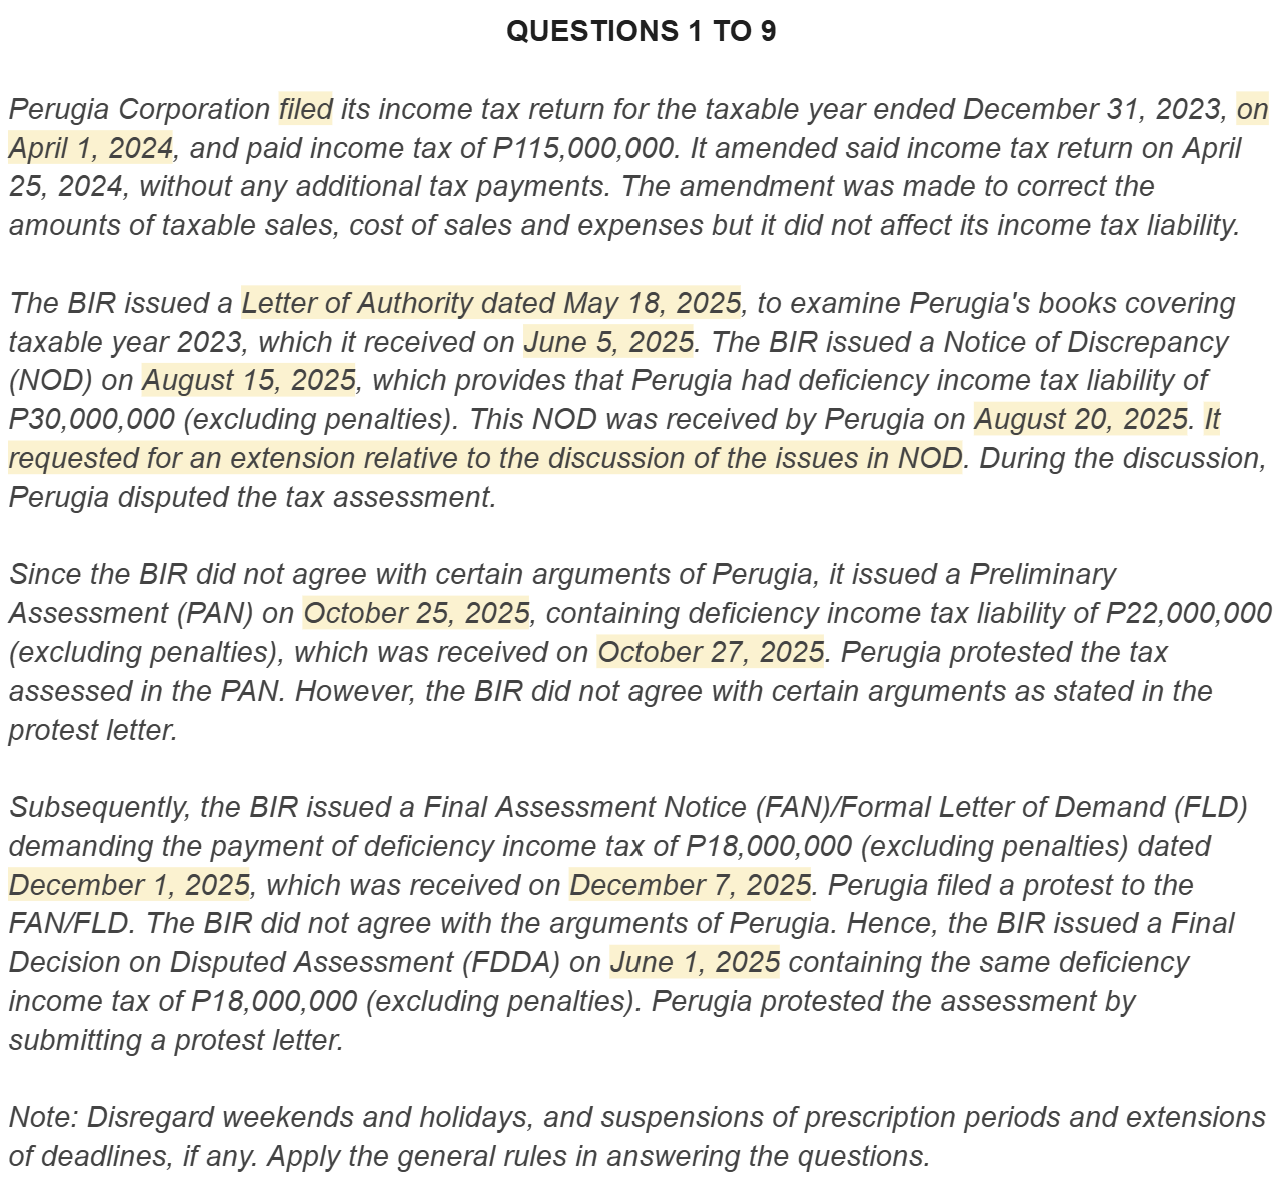
Question 3: NOD Discussion Deadline
Assuming the discussion with the BIR relative to the NOD was made on the last day required under the regulations, when was the said discussion made?
a. August 30, 2025.
b. None of the choices
c. September 4, 2025.
d. September 14, 2025.
e. September 19, 2025.
e
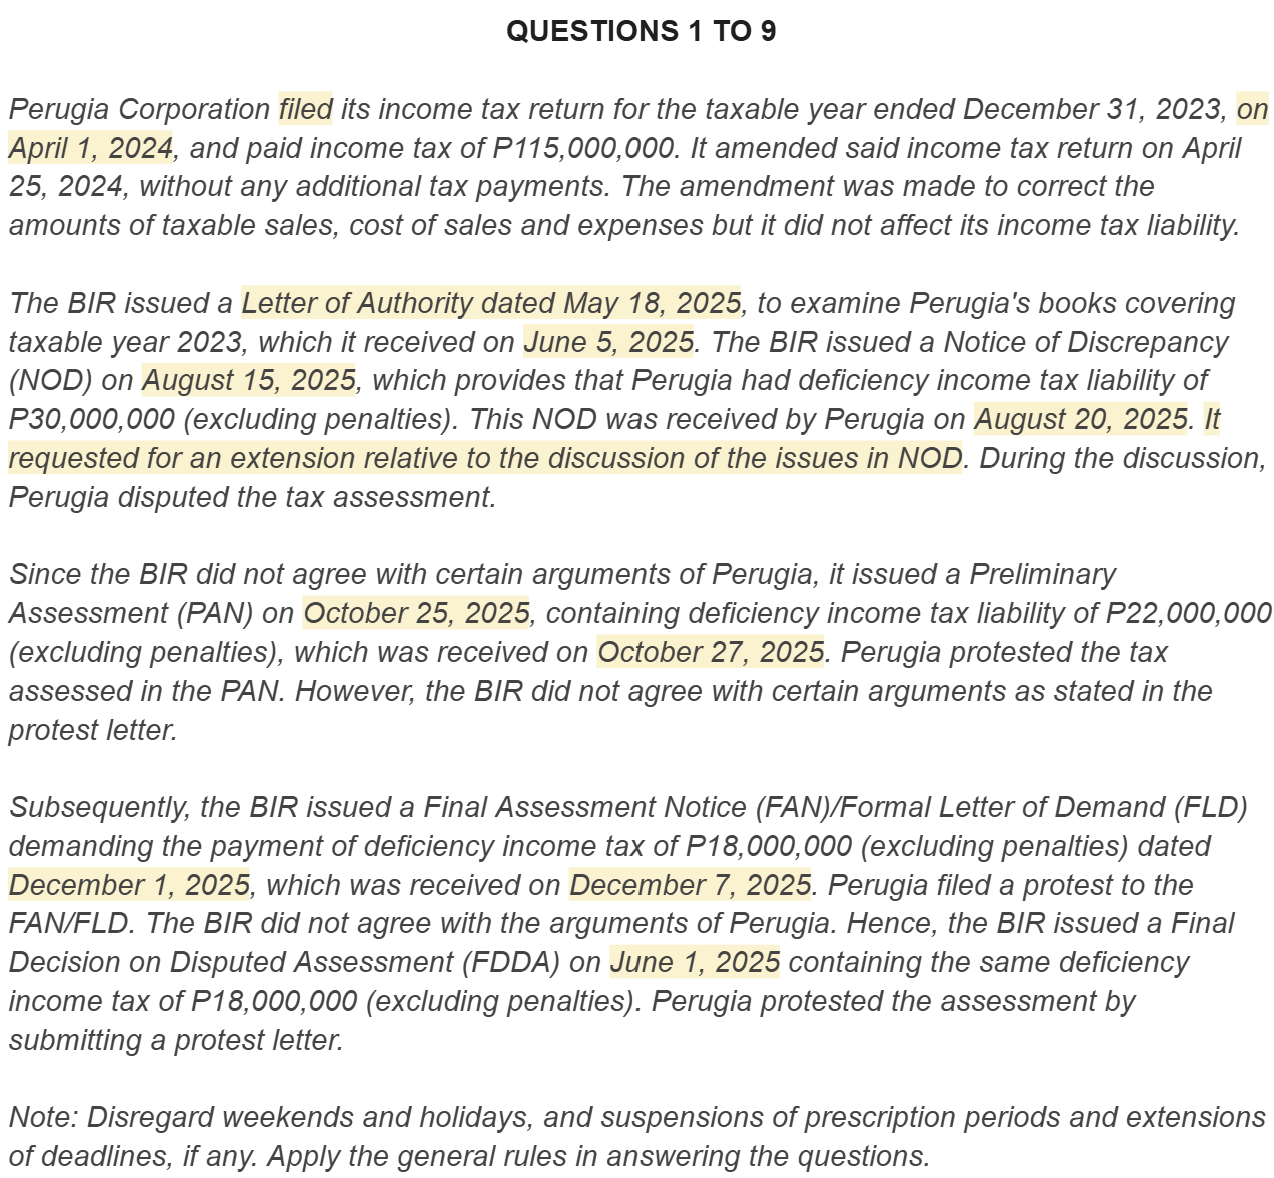
Question 4: PAN Protest Deadline
Assuming the protest to the PAN was submitted on the deadline, when was it made?
a. November 9, 2025.
b. November 24, 2025.
c. November 26, 2025.
d. November 11, 2025.
e. None of the choices
d

Question 5: FAN Protest Deadline (Request for Reconsideration)
Assuming Perugia filed a request of reconsideration to protest the FAN/FLD, when is the deadline for filing the protest?
a. December 22, 2026.
b. None of the choices
c. December 31, 2025.
d. January 6, 2026.
e. December 16, 2025.
d

Question 6: Reinvestigation Document Submission
Assuming Perugia filed a request of reinvestigation to protest the FAN/FLD on the deadline, when is the deadline for submitting the additional documents, assuming the protest letter was submitted on the deadline?
a. March 7, 2026.
b. January 6, 2026.
c. None of the choices
d. April 6, 2026.
e. February 5, 2026.
a

Question 7: Total Amount Payable upon Agreement
Assuming Perugia agreed with the assessment as contained in the FAN/FLD and the deadline for payment of the deficiency tax plus penalties was on December 31, 2025, how much is the total amount that should be paid (excluding compromise penalties)?
a. P26,198,630.
b. P21,781,479.
c. P21,639,452.
d. None of the choices
e. P21,698,630.
e

Question 8: Voluntary Amendment
Assuming Perugia amended its income tax return to pay the additional income tax of P18,000,000 on May 25, 2024, how much was the amount paid (excluding compromise penalties)?
a. P22,736,712.
b. None of the choices
c. P18,177,534.
d. P18,000,000.
e. P18,236,712.
e

Question 9: FDDA Appeals
Assuming Perugia does not agree with the assessment contained in the FDDA and it wanted to appeal, the following are the remedies of Perugia, except:
a. If the Regional Director signed the FDDA, Perugia may file an appeal with the Court of Tax Appeals.
b. If the Commissioner signed the FDDA, Perugia may file another appeal with the Commissioner.
c. If the Regional Director signed the FDDA, Perugia may file an appeal with the Commissioner.
d. If the Commissioner signed the FDDA, it should file an appeal with the Court of Tax Appeals.
b
Question 10: The Administrative Claim Deadline
Rosenberg Corporation erroneously paid its documentary stamp tax (DST) for the month ended May 31, 2023 by P5,000,000. It filed a claim for refund with the BIR on May 15, 2025.
Until when can Rosenberg file a claim for refund of its erroneous DST the month ended May 31, 2023?
a. June 5, 2026.
b. May 31, 2025.
c. June 10, 2025.
d. June 5, 2025.
e. None of the choices
d
*Question 11: The BIR's Deadline to Decide
Rosenberg Corporation erroneously paid its documentary stamp tax (DST) for the month ended May 31, 2023 by P5,000,000. It filed a claim for refund with the BIR on May 15, 2025.
Until when should the BIR render its decision on Rosenberg's claim for refund?
a. None of the choices
b. November 27, 2025.
c. December 7, 2025.
d. December 2, 2026.
e. December 2, 2025.
a
Question 12: The CTA Appeal Deadline (With Denial)
Rosenberg Corporation erroneously paid its documentary stamp tax (DST) for the month ended May 31, 2023 by P5,000,000. It filed a claim for refund with the BIR on May 15, 2025.
Assuming the BIR denied Rosenberg's claim for refund, in which it received said decision on September 10, 2025, until when can it file an appeal with the CTA?
a. November 9, 2025.
b. October 10, 2025.
c. None of the choices
d. March 19, 2026.
e. December 9, 2025.
b
*Question 13: The CTA Appeal Deadline (Without Action)
Rosenberg Corporation erroneously paid its documentary stamp tax (DST) for the month ended May 31, 2023 by P5,000,000. It filed a claim for refund with the BIR on May 15, 2025.
Assuming the BIR did not act on Rosenberg's claim for refund, until when can it file an appeal with the CTA?
a. None of the choices
b. December 27, 2025.
c. January 1, 2026.
d. January 6, 2026.
e. May 15, 2026.
a
Question 14: Jurisdiction Over the Tax Audit
Montreuil Company is a domestic corporation under the jurisdiction of BIR Revenue District Office (RDO) No. 47 until December 31, 2022. Subsequently, it received a notice from the BIR as Large Taxpayer effective January 1, 2023. On February 20, 2024, it received a Letter of Authority (LOA) to audit its books of accounts for the year ended December 31, 2022. Which BIR office will handle the audit of its books of accounts for the year ended December 31, 2022?
a. RDO No. 47 or Large Taxpayer at the discretion of the BIR.
b. Large Taxpayer.
c. RDO No. 47 or Large Taxpayer at the discretion of Montreuil.
d. RDO No. 47.
b
Question 15: Post-Protest Remedies (FAN/FLD Stage)
Flamenco Corporation was assessed deficiency taxes and penalties by BIR. Said assessment is already at the FAN/FLD stage. It filed a protest to the FAN/FLD with the BIR. Which of the following statements is not correct?
a. If the BIR denies the protest to the FAN/FLD, Flamenco may elevate its protest by requesting for reconsideration to the Commissioner within 30 days from the receipt of denial.
b. If the BIR denies the protest to the FAN/FLD, Flamenco may appeal to the Court of Tax Appeals (CTA) within 30 days from the receipt of denial.
c. Flamenco is required to submit the relevant supporting documents in support of its protest within 60 days from the date of filing its Request for Reinvestigation.
d. If the Commissioner did not act on Flamenco's request for reconsideration after denial of its protest to the FAN/FLD, it does not have any option to file a petition for review with the Court of Tax Appeals (CTA) since it opted to elevate its protest to the Commissioner.
d
Question 16: The 180-Day Inaction Rule on Protests
Lisieux Corporation is a company engaged in manufacturing. It was audited by the BIR for the taxable ended December 31, 2024 which is covered by a Letter of Authority (LOA). The assessment was at the Final Assessment Notice (FAN)/Formal Letter of Demand (FLD) stage where it filed a Request for Reconsideration. The said Request was filed on July 15, 2026. If the BIR did not act on the Request for Reconsideration and Lisieux wanted to appeal with the CTA, until when should said appeal be filed?
a. February 10, 2027.
b. January 26, 2027.
c. December 12, 2026.
d. None of the choices
e. January 11, 2027.
a
Question 17: Tax Returns, LOAs, and Prescriptive Periods
Statement 1: When the BIR already issued a Letter of Authority (LOA), the taxpayer can no longer amend its tax return that is covered by said LOA.
Statement 2: When the taxpayer made substantial amendment in its tax return, the counting of the prescription to assess commences from the date when the amended tax return is filed.
a. True, True
b. False, True
c. False, False
d. True, False
a
Context for Questions 18 to 19
ACTTAX Corporation received a Formal Letter of Demand requiring payment of the following:
Deficiency Taxes:
Income Tax - 1,500,000
Value-Added Tax - 800,000
Expanded Withholding Tax - 200,000
Penalties:
Surcharge - 625,000
Interest - 400,000
Compromise - 175,000
Question 18
Assuming it progresses into a tax compromise in view of the doubtful validity of the assessment, how much is the minimum amount that the BIR can collect from the assessment
a. 1,480,000
b. 370,000
c. 2,200,000
d. 1,450,000
e. None of the choices
c
Context for Questions 18 to 19
ACTTAX Corporation received a Formal Letter of Demand requiring payment of the following:
Deficiency Taxes:
Income Tax - 1,500,000
Value-Added Tax - 800,000
Expanded Withholding Tax - 200,000
Penalties:
Surcharge - 625,000
Interest - 400,000
Compromise - 175,000
Question 19
Assuming it progresses into a tax compromise in view of financial incapacity of the taxpayer, how much is the minimum amount that the BIR can collect from the assessment?
a. None of the choices
b. 370,000
c. 2,200,000
d. 1,450,000
e. 1,480,000
d
Context for Questions 20 to 21
ABAKADA Corporation filed its income tax return on April 1, 2025 and paid income tax of P11,500,000 for the taxable year ended December 31, 2024. The BIR issued a Letter of Authority on May 10, 2026 to examine its books covering taxable year 2024, which was received by ABAKADA Corporation on May 28, 2026. A Notice of Discrepancy (NOD) was issued by the BIR on July 15, 2026 which provides that ABAKADA Corporation had deficiency income tax liability of P5,500,000 (excluding penalties). This NOD was received by ABAKADA Corporation on July 20, 2026. A discussion was conducted where ABAKADA Corporation disputed the tax assessment as contained in the NOD. Since the BIR did not agree with certain arguments of ABAKADA Corporation, it issued a Preliminary Assessment (PAN) on August 25, 2026 containing deficiency income tax liability of P3,200,000 (excluding penalties), which was received on August 27, 2026. ABAKADA Corporation protested the tax assessed in the PAN. However, the BIR did not agree with certain arguments as stated in the protest letter. Subsequently, the BIR issued a Final Assessment Notice (FAN)/Formal Letter of Demand (FLD) demanding the payment of deficiency income tax of P2,500,000 (excluding penalties) dated October 5, 2026 which was received on October 15, 2026. ABAKADA Corporation filed a protest to the FAN/FLD. The BIR did not agree with the arguments of ABAKADA Corporation. Hence, the BIR issued a Final Decision on Disputed Assessment (FDDA) on June 10, 2027 containing the same deficiency income tax of P2,500,000 (excluding penalties). ABAKADA Corporation protested the assessment by submitting a protest letter.
Question 20
Assuming ABAKADA Corporation agreed with the assessment as contained in the FAN/FLD and the deadline for payment of the deficiency tax plus penalties was on November 15, 2026, how much is the total amount that should be paid (excluding compromise penalties)?
a. P3,600,890.
b. P2,975,890.
c. P3,612,397.
d. None of the choices
e. P2,987,397.
b
Context for Questions 20 to 21
ABAKADA Corporation filed its income tax return on April 1, 2025 and paid income tax of P11,500,000 for the taxable year ended December 31, 2024. The BIR issued a Letter of Authority on May 10, 2026 to examine its books covering taxable year 2024, which was received by ABAKADA Corporation on May 28, 2026. A Notice of Discrepancy (NOD) was issued by the BIR on July 15, 2026 which provides that ABAKADA Corporation had deficiency income tax liability of P5,500,000 (excluding penalties). This NOD was received by ABAKADA Corporation on July 20, 2026. A discussion was conducted where ABAKADA Corporation disputed the tax assessment as contained in the NOD. Since the BIR did not agree with certain arguments of ABAKADA Corporation, it issued a Preliminary Assessment (PAN) on August 25, 2026 containing deficiency income tax liability of P3,200,000 (excluding penalties), which was received on August 27, 2026. ABAKADA Corporation protested the tax assessed in the PAN. However, the BIR did not agree with certain arguments as stated in the protest letter. Subsequently, the BIR issued a Final Assessment Notice (FAN)/Formal Letter of Demand (FLD) demanding the payment of deficiency income tax of P2,500,000 (excluding penalties) dated October 5, 2026 which was received on October 15, 2026. ABAKADA Corporation filed a protest to the FAN/FLD. The BIR did not agree with the arguments of ABAKADA Corporation. Hence, the BIR issued a Final Decision on Disputed Assessment (FDDA) on June 10, 2027 containing the same deficiency income tax of P2,500,000 (excluding penalties). ABAKADA Corporation protested the assessment by submitting a protest letter.
Question 21
Assuming ABAKADA Corporation amended its income tax return to pay the additional income tax of 2,500,000 on June 25, 2025, how much was the amount paid (excluding compromise penalties)?
a. P2,558,356.
b. None of the choices
c. P2,569,863.
d. P3,194,863.
e. P3,183,356.
a
Context for Questions 22 to 23
Lisieux Corporation is a company engaged in manufacturing. It had taxable income of P6,000,000 for the year ended December 31, 2025. It had direct labor expense of P3,500,000. It hired on-the-job trainees from public schools and incurred training expense of P850,000. Its accountant advised that Lisieux is allowed to claim additional 50% training expenses. Hence, it deducted P425,000 from its taxable income. It filed its annual income tax return and paid the related tax on time. Its minimum corporate income tax is significantly lower than its regular corporate income tax. However, when the BIR conducted its examination in 2027 as covered by a Letter of Authority, it was noted that Lisieux erroneously calculated its taxable income because the additional 50% training expense exceeded the threshold. A Notice of Discrepancy was sent by the BIR. Subsequently, the BIR issued Preliminary Assessment Notice (PAN) which was no longer protested by Lisieux. Hence, the BIR issued Final Assessment Notice (FAN)/Formal Letter of Demand (FLD). Based on the FAN/FLD, the deadline for payment of the deficiency tax was October 31, 2027.
Question 22
How much is the deficiency income tax excluding penalties?
a. P18,750.
b. P127,500.
c. P106,250.
d. P22,500.
e. None of the choices
a
Context for Questions 22 to 23
Lisieux Corporation is a company engaged in manufacturing. It had taxable income of P6,000,000 for the year ended December 31, 2025. It had direct labor expense of P3,500,000. It hired on-the-job trainees from public schools and incurred training expense of P850,000. Its accountant advised that Lisieux is allowed to claim additional 50% training expenses. Hence, it deducted P425,000 from its taxable income. It filed its annual income tax return and paid the related tax on time. Its minimum corporate income tax is significantly lower than its regular corporate income tax. However, when the BIR conducted its examination in 2027 as covered by a Letter of Authority, it was noted that Lisieux erroneously calculated its taxable income because the additional 50% training expense exceeded the threshold. A Notice of Discrepancy was sent by the BIR. Subsequently, the BIR issued Preliminary Assessment Notice (PAN) which was no longer protested by Lisieux. Hence, the BIR issued Final Assessment Notice (FAN)/Formal Letter of Demand (FLD). Based on the FAN/FLD, the deadline for payment of the deficiency tax was October 31, 2027.
Question 23
How much is the deficiency income tax plus surcharge, if any, and interest?
a. P26,914.
b. P125,951.
c. None of the choices
d. P26.672.
e. P22,227.
e
Question 24
The taxpayer timely filed his ITR and paid the tax due as shown therein on April 15, 2022. The BIR subsequently determined that a deficiency tax of P100,000 was still due. The BIR sent a letter of demand and assessment notice asking to pay the deficiency income tax plus interest by July 15, 2022. The taxpayer paid only on August 15, 2022. The total amount due on August 15, 2022 (excluding compromise penalty) is:
a. P129,296
b. P115.300
c. P133,333
d. None of the choices
e. P129,880
a
Context for Questions 25 to 26
ACTTAX Corporation, a company engaged in sale of goods, filed its other percentage tax (OPT) return and paid the related tax due thereon under Section 116 of the Tax Code, as amended, for the quarter ended June 30, 2023 on July 25, 2023. It declared gross sales of P2,700,000. However, when the BIR conducted its examination in 2025 as covered by Letter of Authority, it was noted that ACTTAX Corporation was not able to declare its other income from sale of scraps of P350,000 realized during the same quarter. The BIR issued Notice of Discrepancy (NOD) followed by Preliminary Assessment Notice (PAN) after the discussion of the NOD. ACTTAX Corporation did not protest the PAN. Hence, the BIR issued Final Assessment Notice (FAN)/Formal Letter of Demand (FLD). Based on the FAN/FLD, the deadline for payment of the deficiency tax is on June 30, 2026. Note: Disregard the effect of weekends, holidays, and/or leap year/s, if applicable, in the deadlines.
Question 25
How much is the deficiency OPT excluding penalties?
3,500
Context for Questions 25 to 26
ACTTAX Corporation, a company engaged in sale of goods, filed its other percentage tax (OPT) return and paid the related tax due thereon under Section 116 of the Tax Code, as amended, for the quarter ended June 30, 2023 on July 25, 2023. It declared gross sales of P2,700,000. However, when the BIR conducted its examination in 2025 as covered by Letter of Authority, it was noted that ACTTAX Corporation was not able to declare its other income from sale of scraps of P350,000 realized during the same quarter. The BIR issued Notice of Discrepancy (NOD) followed by Preliminary Assessment Notice (PAN) after the discussion of the NOD. ACTTAX Corporation did not protest the PAN. Hence, the BIR issued Final Assessment Notice (FAN)/Formal Letter of Demand (FLD). Based on the FAN/FLD, the deadline for payment of the deficiency tax is on June 30, 2026. Note: Disregard the effect of weekends, holidays, and/or leap year/s, if applicable, in the deadlines.
Question 26
How much is the deficiency OPT plus penalties (excluding compromise penalties) to be paid on October 31, 2025?
4,731
Context for Questions 27 to 30
ACTTAX Corporation, a large corporation, filed its annual income tax return and paid its income tax of P18,000,000 for the taxable year ended December 31, 2024 on May 10, 2025, which is beyond the prescribed deadline. It subsequently amended said tax return on May 15, 2025 by paying additional income tax of P7,500,000 plus penalties. However, it was discovered that it erroneously overpaid income tax amounting to P2,750,000. Hence, it claimed for tax refund or tax credit certificate (TCC).
Question 27
How much did ACTTAX Corporation pay when it amended its income tax return on May 15, 2025 (deficiency tax plus penalties, if any, excluding compromise penalties)? (Round-off your answer to the nearest peso).
9,448,973
Context for Questions 27 to 30
ACTTAX Corporation, a large corporation, filed its annual income tax return and paid its income tax of P18,000,000 for the taxable year ended December 31, 2024 on May 10, 2025, which is beyond the prescribed deadline. It subsequently amended said tax return on May 15, 2025 by paying additional income tax of P7,500,000 plus penalties. However, it was discovered that it erroneously overpaid income tax amounting to P2,750,000. Hence, it claimed for tax refund or tax credit certificate (TCC).
Question 28
Given the same set of information except that ACTTAX Corporation is classified instead as a medium taxpayer, how much did ACTTAX Corporation pay when it amended its income tax return on May 15, 2025 (deficiency tax plus penalties, if any, excluding compromise penalties)? (Round-off your answer to the nearest peso).
9,448,973
Context for Questions 27 to 30
ACTTAX Corporation, a large corporation, filed its annual income tax return and paid its income tax of P18,000,000 for the taxable year ended December 31, 2024 on May 10, 2025, which is beyond the prescribed deadline. It subsequently amended said tax return on May 15, 2025 by paying additional income tax of P7,500,000 plus penalties. However, it was discovered that it erroneously overpaid income tax amounting to P2,750,000. Hence, it claimed for tax refund or tax credit certificate (TCC).
Question 29
Assuming instead that the original annual income tax return was filed on time on April 15, 2025, how much did ACTTAX Corporation pay when it amended its income tax return on May 15, 2025 (deficiency tax plus penalties, if any, excluding compromise penalties)? (Round-off your answer to the nearest peso).
7,573,973
Context for Questions 27 to 30
ACTTAX Corporation, a large corporation, filed its annual income tax return and paid its income tax of P18,000,000 for the taxable year ended December 31, 2024 on May 10, 2025, which is beyond the prescribed deadline. It subsequently amended said tax return on May 15, 2025 by paying additional income tax of P7,500,000 plus penalties. However, it was discovered that it erroneously overpaid income tax amounting to P2,750,000. Hence, it claimed for tax refund or tax credit certificate (TCC).
Question 30
Assuming the BIR granted the claim for tax refund or TCC without any disallowance on July 15, 2026. How much will be the amount of said refund or TCC, including interest, if any?
2,750,000
Question 31
Which of the following entities will be subject to local business tax (LBT)?
a. BOI-registered entities paying the 5% special corporate income tax (SCIT) under the CREATE Act.
b. SBMA-registered entities paying the 5% gross income tax (GIT) under the SBMA Law.
c. Enterprises engaged in the export of computer products.
d. PEZA-registered entities paying the 5% gross income tax (GIT) under the PEZA Law.
c
Question 32
The following are considered essential commodities for local business tax purposes (LBT), except:
a. Cement.
b. Office supplies.
c. Dairy products.
d. Wheat flour.
b
Question 33
Real property tax (RPT) is calculated based on:
a. Fair market value.
b. Purchase price.
c. Assessed value.
d. Book value.
c
Question 34
The following real properties are exempt from real property tax (RPT), except:
a. Machinery and equipment used for pollution control and environmental protection.
b. Building owned by the government which is being used by a private company under a lease arrangement.
c. Land owned by a duly registered cooperatives in accordance with RA No. 6938.
d. Leasehold improvement actually, directly, and exclusively used for charitable purposes by a charitable institution.
b
Question 35
Deficiency RPT and LBT are subject to interest at:
a. 12% per annum until paid but not exceeding three (3) years.
b. 12% per annum until paid.
c. 2% per month until paid.
d. 2% per month until paid but not exceeding 36 months.
d
Question 36
The Local Government Unit (LGUs) can assess deficiency LBT for a period of:
a. 2 years from due date.
b. 10 years from due date.
c. 5 years from due date.
d. 3 years from due date.
c
Question 37 Real property declared for the first time for RPT purposes shall be assessed deficiency RPT for a period not more than:
a. 5 years prior to the date of initial assessment.
b. 10 years prior to the date of initial assessment.
c. 3 years prior to the date of initial assessment.
d. 2 years prior to the date of initial assessment.
b
Question 38
If there are underpayments of real property tax (RPT) accrued as of January 1, 2024 for land and building, until when can the local government unit (LGU) assess Kastoria for deficiency RPT plus penalties?
a. March 31, 2029.
b. March 31, 2029 for first quarter, June 30, 2029 for second quarter, September 30, 2029 for third quarter and December 31, 2029 for fourth quarter.
c. January 20, 2029 for first quarter, April 20, 2029 for second quarter, July 20, 2029 for third quarter and October 20, 2029 for fourth quarter.
d. January 20, 2029.
b
*Question 39
The specialized machineries were acquired in 2010 and these are still used until December 31, 2025. On July 1, 2025 it was discovered by the local government unit (LGU) that Kastoria failed to declare these for RPT purposes. What period will be covered by the assessment?
a. January 1, 2020 to December 31, 2025.
b. July 1, 2020 until June 30, 2025.
c. January 1, 2015 to December 31, 2025.
d. July 1, 2015 until June 30, 2025.
c
Context for Questions 40 to 41
The following data are taken from the books of Melilla Manufacturing Company for the year ended December 31, 2023: Gross sales - P49,000,000; sales returns - P3,000,000; sales discount, granted at the time of sale - P1,000,000; and prompt payment discount - P1,200,000.
Question 40
Assuming the local government unit where Melilla is located imposes a local business tax (LBT) of 75% of 1%, how much is its LBT liability?
a. None of the choices
b. P367,500.
c. P337,500.
d. P328,500.
e. P345,000.
c
Context for Questions 40 to 41
The following data are taken from the books of Melilla Manufacturing Company for the year ended December 31, 2023: Gross sales - P49,000,000; sales returns - P3,000,000; sales discount, granted at the time of sale - P1,000,000; and prompt payment discount - P1,200,000.
*Question 41
Assuming the LBT is paid quarterly, when should the third quarter tax be paid?
a. October 20, 2024.
b. September 30, 2023
c. October 20, 2023.
d. None of the choices
e. September 30, 2024.
d
Context for Questions 42 to 44
Palencia Company, Inc. had the following gross receipts for the year ended December 31, 2023: leasing of commercial spaces - P10,800,000; parking spaces - P3,500,000; other income - P1,000,000. The other income pertains to gain from sale of certain fully-depreciated assets. The local government unit (LGU) where Palencia is located imposes LBT on leasing including parking of 1.5%.
Question 42
When will these gross receipts of Palencia be subject to LBT?
a. Calendar year 2025.
b. Calendar year 2023.
c. Calendar year 2022.
d. None of the choices
e. Calendar year 2024.
e
Context for Questions 42 to 44
Palencia Company, Inc. had the following gross receipts for the year ended December 31, 2023: leasing of commercial spaces - P10,800,000; parking spaces - P3,500,000; other income - P1,000,000. The other income pertains to gain from sale of certain fully-depreciated assets. The local government unit (LGU) where Palencia is located imposes LBT on leasing including parking of 1.5%.
Question 43
How much is the LBT of Palencia for the covered taxable year? Assume that other income is considered incidental to its main activity.
a. P162,000.
b. P229,500.
c. P214,500.
d. P57,375.
e. None of the choices
b
Context for Questions 42 to 44
Palencia Company, Inc. had the following gross receipts for the year ended December 31, 2023: leasing of commercial spaces - P10,800,000; parking spaces - P3,500,000; other income - P1,000,000. The other income pertains to gain from sale of certain fully-depreciated assets. The local government unit (LGU) where Palencia is located imposes LBT on leasing including parking of 1.5%.
Question 44
When should Palencia pay the LBT on the above taxable year assuming that it is paid lump-sum?
a. None of the choices
b. January 20, 2024.
c. January 20, 2023.
d. December 31, 2023.
e. January 1, 2024.
b
Context for Questions 45 to 46
Avignon Corporation is engaged in the business of manufacturing of food products. The following financial information pertains to the year ended December 31, 2024:
Sales recorded in Locality A where the principal office is located amounts to P20,000,000
Avignon has a factory in Locality B and a plantation in Locality C where the primary raw materials of its food products are grown.
The following are the applicable LBT rates on local sales:
Locality A - 75% of 1%
Locality B - 50% of 1%
Locality C - 30% of 1%
Question 45
How much is the LBT payable to Locality A?
a. None of the choices
b. P105,000.
c. P150,000.
d. P45,000.
e. P60,000.
d
Context for Questions 45 to 46
Avignon Corporation is engaged in the business of manufacturing of food products. The following financial information pertains to the year ended December 31, 2024:
Sales recorded in Locality A where the principal office is located amounts to P20,000,000
Avignon has a factory in Locality B and a plantation in Locality C where the primary raw materials of its food products are grown.
The following are the applicable LBT rates on local sales:
Locality A - 75% of 1%
Locality B - 50% of 1%
Locality C - 30% of 1%
Question 46
How much is the LBT payable to Locality B?
a. P42,000.
b. P70,000.
c. P18,000.
d. P28,000.
e. None of the choices
a
Context for Questions 47 to 49
Mr. Logrono acquired a residential land located in Metro Manila on October 1, 2023. Its fair market value is P10,000,000. The LGU imposes the maximum real property tax (RPT) rate prescribed under the LGC. The related ordinance provides that the assessed level of residential properties is 20%.
Question 47
How much is the basic real property tax (RPT)?
a. P20,000.
b. P200,000.
c. None of the choices
d. P60,000.
e. P40,000.
e
Context for Questions 47 to 49
Mr. Logrono acquired a residential land located in Metro Manila on October 1, 2023. Its fair market value is P10,000,000. The LGU imposes the maximum real property tax (RPT) rate prescribed under the LGC. The related ordinance provides that the assessed level of residential properties is 20%.
Question 48
How much is the Special Education Fund (SEF)?
a. P20,000.
b. P100,000.
c. P30,000.
d. None of the choices
e. P10,000.
a
Context for Questions 47 to 49
Mr. Logrono acquired a residential land located in Metro Manila on October 1, 2023. Its fair market value is P10,000,000. The LGU imposes the maximum real property tax (RPT) rate prescribed under the LGC. The related ordinance provides that the assessed level of residential properties is 20%.
*Question 49
Until when should Mr. Logrono pay the initial RPT on the said land assuming that the said tax is paid lump-sum?
a. None of the choices
b. January 1, 2024
c. October 31, 2023.
d. December 31, 2023.
e. March 31, 2024.
e
Context for Questions 50 to 51
Naflion Manufacturing Company sold goods to its local customers, which are domestic buyers, export-oriented enterprise (EOEs), registered export enterprises (REEs) which are registered with Investment Promotion Agencies (IPA), and non-resident buyers for the year ended December 31, 2025, as follows (exclusive of VAT, if applicable):
Domestic buyers - P30,000,000
Export-oriented enterprise (non-IPA registered) - P15,000,000
Registered export enterprises - P25,000,000
Non-registered (typo for resident) buyers - P80,000,000
Naflion is located in a city where sales of goods are subject to local business tax (LBT) of 75% of 1%.
*Question 50
How much is the LBT of Naflion for the above sales transactions? (Hint: Consider all VAT zero-rated sales as export sales.)
a. P562,500.
b. P225,000.
c. P1,125,000.
d. P675,000.
e. None of the choices
d
Context for Questions 50 to 51
Naflion Manufacturing Company sold goods to its local customers, which are domestic buyers, export-oriented enterprise (EOEs), registered export enterprises (REEs) which are registered with Investment Promotion Agencies (IPA), and non-resident buyers for the year ended December 31, 2025, as follows (exclusive of VAT, if applicable):
Domestic buyers - P30,000,000
Export-oriented enterprise (non-IPA registered) - P15,000,000
Registered export enterprises - P25,000,000
Non-registered buyers - P80,000,000
Naflion is located in a city where sales of goods are subject to local business tax (LBT) of 75% of 1%.
Question 51
When is the due date of LBT of Naflion on the above sales transactions, if it will pay the said tax lump-sum?
a. March 31, 2026.
b. January 20, 2025.
c. January 20, 2026.
d. December 31, 2025.
e. None of the choices
c
Context for Questions 52 to 53
Poitiers Broadcasting Company owns certain specialized machinery with fair market value of P10,000,000. These were acquired on April 10, 2023 and declared on April 30, 2023. These properties are located in Metro Manila and have assessed level of 80%.
Question 52
How much is the annual basic RPT and SEF on the specialized machinery?
a. P240,000.
b. P300,000.
c. None of the choices
d. P-0-.
e. P160,000.
a
Context for Questions 52 to 53
Poitiers Broadcasting Company owns certain specialized machinery with fair market value of P10,000,000. These were acquired on April 10, 2023 and declared on April 30, 2023. These properties are located in Metro Manila and have assessed level of 80%.
Question 53
When will Poitiers RPT accrue on the special machinery?
a. January 1, 2024.
b. None of the choices
c. January 1, 2023.
d. April 30, 2023.
e. March 31, 2024.
a
*Question 54
Mr. Joaquin owns a residential house with an assessed value of P300,000 and residential lot with a fair market value of P800,000. The province where the real property is located levies the maximum taxes prescribed under the Local Government Code of 1991. How much would the required payment per installment of basic (typo for total) real property tax be if the real property tax will be paid in installments?
a. 3,450
b. 11,500
c. 17,250
d. None of the choices
e. 2,300
e
*Question 55
A house and lot was sold on March 20, 2023 for P2,000,000. The market values of the house and lot in the tax declaration are P1,155,600 and 1,000,000, respectively. The zonal value of the lot is P1,890,200. assuming that the transfer tax rate in the city is fixed at the maximum allowed by law, the transfer tax payable to transfer the title in the name of the buyer is
a. 15,229
b. None of the choices
c. 16,167
d. 22,843
e. 10,778
d
Context for Questions 56 to 58
Jackienema Inc. reported the following financial figures for the applicable years:
20x7 | 20x8 | 20x9 | |
Gross Receipts from Tickets | 3,100,000 | 2,100,000 | 3,800,000 |
Sales from Popcorns and Snacks | 200,000 | 50,000 | 300,000 |
Royalties to Film Owners | 1,200,000 | 1,600,000 | 1,800,000 |
Cost of Food Sales | 120,000 | 30,000 | 250,000 |
Non-Tax Operating Expenses | 1,100,000 | 800,000 | 1,000,000 |
Question 56
How much is the local amusement tax payable for 20x7?
a. 310,000
b. 0
c. 330,000
d. 210,000
e. None of the choices
a
Context for Questions 56 to 58
Jackienema Inc. reported the following financial figures for the applicable years:
20x7 | 20x8 | 20x9 | |
Gross Receipts from Tickets | 3,100,000 | 2,100,000 | 3,800,000 |
Sales from Popcorns and Snacks | 200,000 | 50,000 | 300,000 |
Royalties to Film Owners | 1,200,000 | 1,600,000 | 1,800,000 |
Cost of Food Sales | 120,000 | 30,000 | 250,000 |
Non-Tax Operating Expenses | 1,100,000 | 800,000 | 1,000,000 |
Question 57
How much is the local amusement tax payable for 20x8?
a. 410,000
b. 215,000
c. None of the choices
d. 210,000
e. 380,000
d
Context for Questions 56 to 58
Jackienema Inc. reported the following financial figures for the applicable years:
20x7 | 20x8 | 20x9 | |
Gross Receipts from Tickets | 3,100,000 | 2,100,000 | 3,800,000 |
Sales from Popcorns and Snacks | 200,000 | 50,000 | 300,000 |
Royalties to Film Owners | 1,200,000 | 1,600,000 | 1,800,000 |
Cost of Food Sales | 120,000 | 30,000 | 250,000 |
Non-Tax Operating Expenses | 1,100,000 | 800,000 | 1,000,000 |
Question 58
How much is the local amusement tax payable for 20x9?
a. 380,000
b. 410,000
c. 210,000
d. 215,000
e. None of the choices
a
Context for Questions 59 to 60
Jackie, an owner of an agricultural land in a rural area in the province, promptly paid the real property taxes prior to the start of the new calendar year 2026 for P34,560.
Question 59
Assuming that Jackie forgot to pay the tax and was only able to do so on September 30, 2026, how much is the interest penalty?
a. None of the choices
b. 9,720
c. 3,110
d. 6,221
e. 7,776
e
Context for Questions 59 to 60
Jackie, an owner of an agricultural land in a rural area in the province, promptly paid the real property taxes prior to the start of the new calendar year 2026 for P34,560.
*Question 60
Assuming it was paid on January 5, 2026 and the land is instead located in an urban area in NCR, how much is the total amount due?
a. None of the choices
b. 64,800
c. 54,000
d. 60,480
e. 75,600
b