Econ Exam Studying
 Call Kai
 Learn
 Practice Test
 Spaced Repetition
 Match
 Flashcards
 Knowt Play
1/63

There's no tags or description
Looks like no tags are added yet.
Name | Mastery | Learn | Test | Matching | Spaced | Call with Kai | Chat |
|---|
No analytics yet
Send a link to your students to track their progress
64 Terms
The Cost Benefit Principle
Costs and benefits are the incentives that shape decisions. You should evaluate the full set of costs and benefits of any choice, and pursue only those whose benefits are at least as large as their costs.
The Opportunity Cost Principle
The true cost of something is the next best alternative you must give up to get it. Your decisions should reflect this opportunity cost, rather than just the out-of-pocket financial costs.
The Marginal Principle
Decisions about quantities are best made incrementally. You should break “how many” decisions down into a series of smaller, or marginal, decisions.
The Interdependence Principle
Your best choice depends on your other choices, the choices others make, developments in other markets, and expectations about the future. When any of these factors change, your best choice might change.
framing effect
small differences in how alternatives are described, or framed, can lead people to make different choices
sunk costs
when the time, effort, an other costs you put into the project cannot be reversed (good decision makers ignore sunk costs)
production possibility frontier
maps out different sets of outputs that are attainable with scarce resources. moving along prouction possibility frontier highlights opportunity cost.
the rational rule
if something is worth doing, keep doing it until your marginal benefits equal your marginal costs
order of principles when making decision
mmarginal principle, cost-benefit, opportunity cost, interdependence
law of demand
tendency for the quantity demanded to be higher when the price is lower
rational rule for buyers
buy more of an item if the marginal benefit of one more is greater than or equal to the price. to maximize your economic surplus, keep applying the rational rule for buyers until price = marginal benefit. your demand curve is also your marginal benefit curve
the market demand curve
plots the total quantity of a good demanded by the market (across all potential buyers at each price).
market demand
the sum of the quantity demanded by each person
4 steps for market demand curves
1) survey customers
2) add up total quantity demanded in survey
3) scale up quantities to represent the whole market
4) plot total quantity demanded at each price point
who do prices change the quantity demanded for? explain
for both new and old customers. changes in price can change who your customers are.
what shifts the demand curve
happens when factors other than price change. rightward shift of the demand curve = increase in demand, bc at each and every price, the quantity demanded is higher
6 factors that shift demand curve
income
preferences
prices of related goods
expectations
congestion and network effects
the type and number of buyers
normal good
goods for which your demand increases when your income is higher
inferior goods
goods for which demand decreases as income increases
complementary goods
when the higher price of one good decreases demand for another, etc (hot dogs and hot dog buns)
substitute goods
Goods that can be used in place of each other. When the price of one good increases, demand for its substitute increases. If the price of coffee increases, consumers may switch to tea, increasing demand for tea.
distinction between movements along demand curve and shift of the curve itself
when the price changes, you are analyzing a movement along the demand curve. when other factors change, the demand curve may shift.
variable costs
costs of production that change depending on how much a firm produces.
When production increases → total variable costs increase.
When production decreases → total variable costs decrease.
example: Raw materials: A bakery needs more flour and sugar to make more cakes.
fixed costs
costs that dont vary when you change the quantity of output you produce. example: Rent: A bakery pays $2,000 per month for its storefront, regardless of how many cakes it sells.
rational rule for sellers in competitive markets
sell one more unit if the price is greater than (or equal to) the marginal cost
market supply
the sum of the quantity supplied by each seller. illustrates the total quantity supplied by the market.
how to find total quantity supplied at a given price
add up the quantity supplied by each individual supplier
which way oes supply curve vs demand curve slope?
demand curve is downwards sloping, and supply curve is upwards sloping
which principle of economics relates to the shift of actual curves?
interdependence principle
why is the market curve upward sloping (2 reasons)
1) a higher price leads individual sellers to increase supply
2) a higher price means it’s more profitable to be a supplier —> a lower price means it’s less profitable
5 factors that shift supply curve
1) input prices
2) productivity and technology
3) prices of related outputs
4) expectations
5) the type and number of sellers
goal of demand
to maximize economic surplus: the difference between the benefit you get and the price you pay
the goal of supply
to maximize profits: the difference between your revenues and your costs
equilibirum
the point at which every seller who wants to sell an item at the current price can find a buyer, and every buyer who wants to buy at the current price can find a willing seller (where the curves cross)
how do shortage and surplus affect the price
shortage causes the price to rise, surplus causes the price to fall
GDP
stands for gross domestic product. the market value of all final goods and services produced within a country in a year.
how to calculate GDP
GDP = C + I + G + NX. (consumption + investment + gov purchases + net exports (imports-exports).
investment
spending on goods that will be used to produce other goods and services in the future. Business equipment:
examples:
A bakery purchases a new oven to make more cakes.
Factories and buildings: A company builds a new factory or warehouse.
Machinery: A car manufacturer purchases new robots for its assembly line.
what does gdp miss
1) prices dont equate to values
2) leaves out nonmarket activities
3) shadow economy is missing
4) environmental degradation isn’t counted
5) leisure doesnt count
nominal GDP (and downside of it)
The total value of all final goods and services produced within a country, calculated using prices from the current year. Nominal GDP does not adjust for inflation.
Current Prices × Current Quantities
Real GDP
The total value of all final goods and services produced within a country, calculated using prices from a fixed base year.
Real GDP adjusts for inflation, allowing us to measure changes in actual production.
Base-Year Prices × Current Quantities
how to calculate growth rate
(new value - old value)/(old value) x 100
how to calculate the percent change in real gdp
percent change in nominal gdp - percent change in prices
working age population
The civilian noninstitutional population ages 16 and older, used for standard U.S. labor statistics
unemployed
A person who does not have a job, is available to work, and has actively looked for work in the past four weeks (or is on temporary layoff).
not in the labor force
People who are neither employed nor officially unemployed, such as retirees, full-time students who aren't working or seeking work, and people who have stopped looking for work.
labor force
empoyed + unemployed
unemployment rate
unemployed/labor force x 100
Labor Force Participation Rate
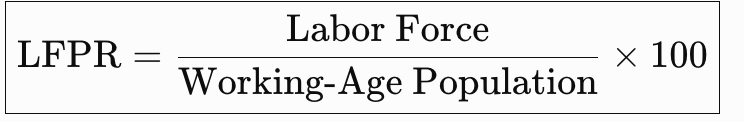
Employment-Population Ratio
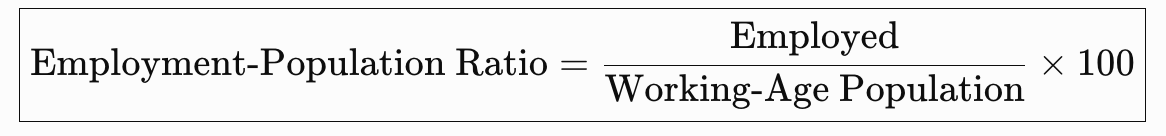
frictional unemployment
Unemployment caused by the time it takes workers and employers to find a suitable match. | A college graduate searching for their first job. |
structural unemployment
Unemployment caused by structural barriers or mismatches in the labor market that prevent available workers from obtaining jobs. | Workers unable to find jobs because their skills no longer match employers' needs, or because wages are held above equilibrium. |
cyclical unemployment
Unemployment caused by a temporary downturn in economic activity. | A restaurant lays off employees because customers spend less during a recession. |
equilibrium unemployment rate
The long-run unemployment rate toward which the economy tends to return. Your notes describe it as approximately 4–5%. It is not necessarily zero because workers are continually entering, leaving, and changing jobs.
inflation
A sustained increase in the overall price level of goods and services in an economy.
inflation rate
The percentage change in the overall price level over a period of time.
Consumer Price Index (CPI)
A measure of the cost of a fixed basket of goods and services purchased by a typical consumer, relative to its cost in a base year.
market basket
A collection of goods and services used to measure changes in consumer prices, such as food, housing, transportation, and clothing.
base year
The reference year used to compare prices over time. The CPI is set to 100 in the base year.
CPI calculations
(cost of basket in current year/cost of basket in base year) x 100
inflation rate calculation

adjusting prices for inflation calculation

real wage calculation

real interest rate calculation
nominal interest rate - inflation rate