Chapter 13: Current Liabilities and Contingencies
Characteristics of Liabilities
Probable, future sacrifices of economic benefit
Arise from present obligations
Result from past transactions or events
Funds can be provided by owners or must be borrowed.
When businesses issue notes and bonds, their creditors are:
Banks
Individuals
Organizations that exchange cash for securities
Most common type of liability - one to be paid in cash and for which the amount and timing are specifies by a legally enforceable contract
Liability: to be reported as a liability, an obligation needs to not be payable in cash
May require the company to transfer other assets or provide services
Doesn’t have to be represented by a written agreement or be legally enforceable
Time and payment does not need to be known
Characteristics of Current Liabilities
Obligation payable within one year or firm’s operating cycle
Satisfied from current assets
Satisfied by creation of other current liabilities
Liabilities should be recorded at their present values
Except liabilities payable within one year which are ordinarily recorded at maturity amounts
Most common obligations reported as current liabilities:
Accounts payable
Notes payable
Commercial paper
Income tax liability
Dividends payable
Accrued liabilities
Other
Current portion of long-term debt
Accounts Payable - are obligations to suppliers of merchandise or of services purchased on open account
Credit instrument: invoice
Short duration (30,45,60 days)
Non interest-bearing and reported at face amounts
Key accounting considerations
Determining existence
Recording in the appropriate accounting period
Trade Notes Payable - differ from accounts payable in that they are formally recognized by a written promissory note
Longer duration
Bear interest
Short-Term Notes Payable Characteristics (Bank Loan)
Temporary financing from bank
Promissory note is signed (like an IOU)
Lower interest rates than long-term debt
Companies have flexibility while selecting financial alternatives
Line of credit - is an agreement to provide short-term financing, with amounts withdrawn by the borrower only when needed
Can last several years
Non committed line of credit
Informal agreement
Permits a company to borrow up to a prearranged limit without formal loan procedures and paperwork
Borrower may be required to maintain a compensating balance in the bank (5% of the credit line)
Committed line of credit
Formal agreement
Requires the company to pay a commitment fee to the bank to keep a credit line amount available to the company
Typical commitment fee is ¼ % of the total committed funds and may also require compensating fee
Interest (“rent” paid for using money)
Paid by borrowing company during the loan term
Return for using lender’s money
Stated in terms of a percentage rate to be applied to the face amount of the loan
Interest = Face amount x Annual rate x Time to maturity
Non interest bearing note - interest is deducted from the face amount to determine the cash proceeds made available to the borrower
When interest is discounted from the face amount of a note, the effective interest rate is higher than the stated discount rate.
“being discounted at issuance at a 12% discount rate”
700,000 × 12% x 6/12 = 42,000
Amount borrowed is 658,000, so effective interest rate is higher than the 12% stated
42,000 for 6 months/658,000 = 6.38%
To annualize: 6.38% x 12/6 = 12.76% EIR
Secured loans - loan made by pledging a specified asset of the borrower as collateral or security
Pledging accounts receivable: When accounts receivable serves as a collateral
Factoring receivables: When the receivables actually are sold outright to a finance company
Commercial paper - unsecured notes sold in minimum denominations of 25,000 with maturities ranging from 1 - 270 days
Beyond 270 days the firm would be required to file a registration statement with the SEC
Interest often is discounted at issuance
Usually commercial paper is issued directly to the buyer (lender) and is backed by a line of credit with a bank
This allows the interest rate to be lower than in a bank loan
In a statement of cash flows, the cash a company receives from using short-term notes to borrow funds as well as the cash it uses to repay the notes are reported among cash flows from financing activities.
Total Short-Term Borrowings: secured by financing receivables (retail notes) on the balance sheet.
Accrued liabilities (accrued expenses): represent expenses already incurred but not yet paid
Recorded by adjusting entries
Usually combined and reported under a single caption in the balance sheet
Common examples:
Salaries and wages payable
Income taxes payable
Interest payable
Issuance of note Dr. Cr.
Cash xx
Notes payable xx
Accrual of interest Dr. Cr.
Interest expense xx
Interest payable xx
Note payment Dr. Cr.
Interest expense xx (NP x % promissory note x months)
Interest payable xx
Notes payable xx
Cash xx
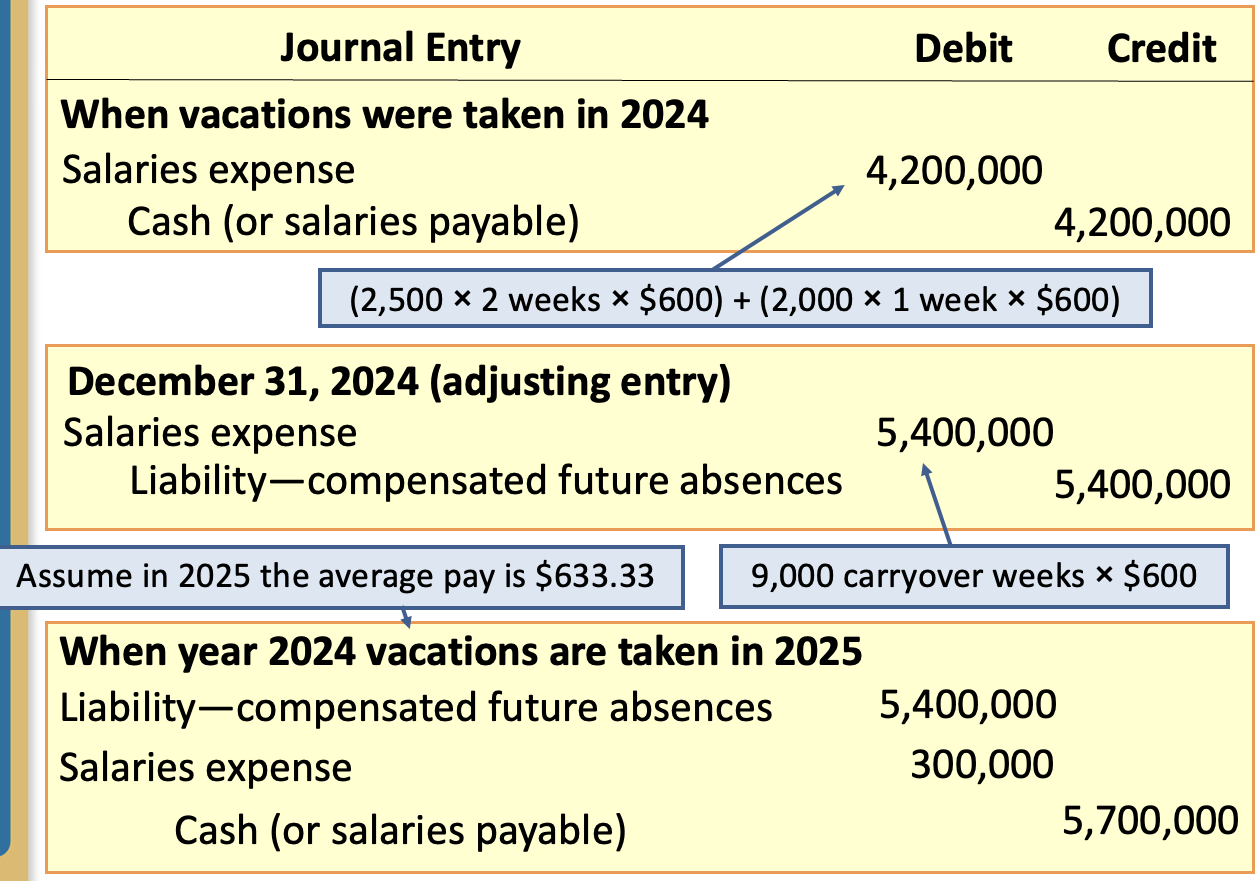
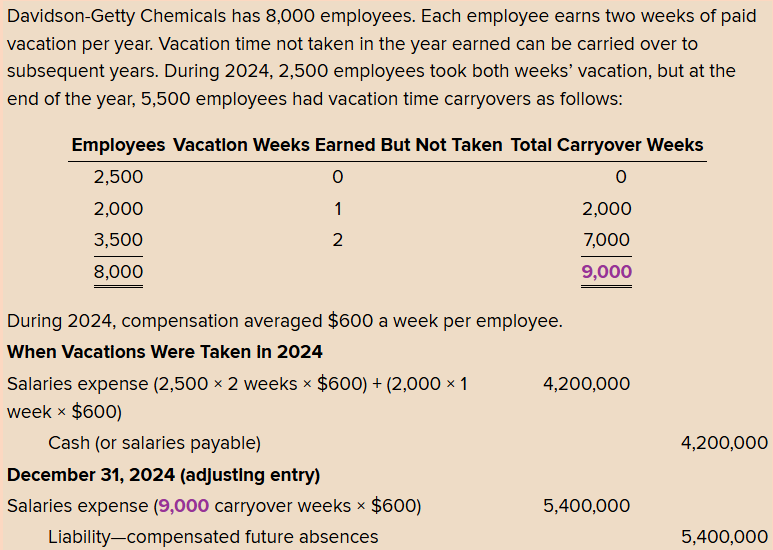
Four conditions for accrual of paid future absences:
1. The obligation is attributable to employees’ services already performed
2. The paid absence can be taken in a later year—the benefit vests or the benefit can be accumulated over time
3. Payment is probable
4. The amount can be reasonably estimated
Annual Bonuses
Tied to performance objectives to provide incentive to executives
Are compensation expense of the period in which they are earned
Financial measures
Earnings per share
Net income
Operating income
Non financial measures
Customer satisfaction
Product or service quality
Liabilities are created when deposits and advances are received from customers.
Advance collections
Deposits and advances from customers
Refundable deposits
Advances from customers
Gift cards
Collections for third parties
Refundable deposits:
When deposits are collected Dr. Cr.
Cash xx
Liability - refundable deposits xx
When containers are returned
Liability - refundable deposits xx
Cash xx
When deposits are forfeited
Liability - refundable deposits. xx (90% x 300,000)
Revenue - sale of containers xx
COGS xx (300,000 - 270,000)
Inventory of containers xx (300,000/2)
Advances from customers represent liabilities until the product or service is provided or the advance is collected.
Examples:
Gift certificates
Magazine subscriptions
Layaway deposits
Special order deposits
Airline tickets
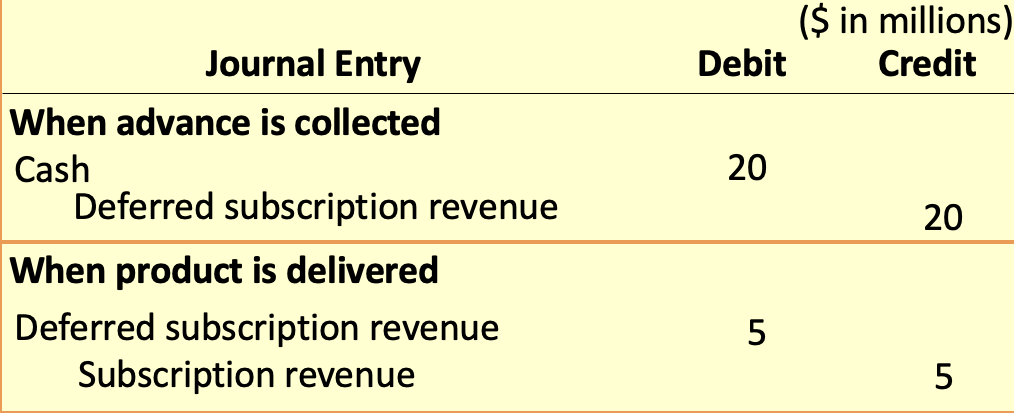
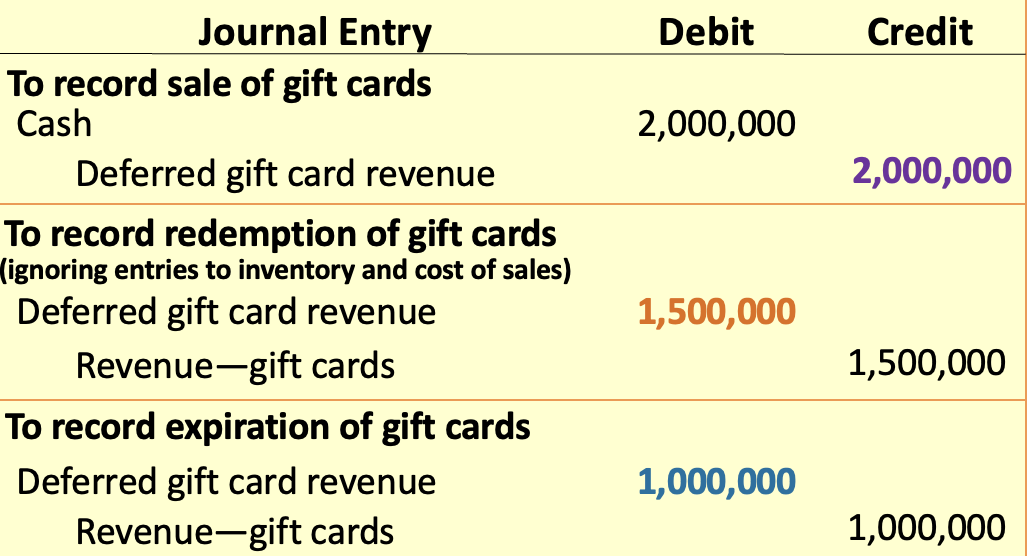
Gift cards (gift certificates): Cash received for sale of gift card recorded as deferred revenue
Later recognition of revenue
on redemption
on breakage (“remote probability of redemption”)
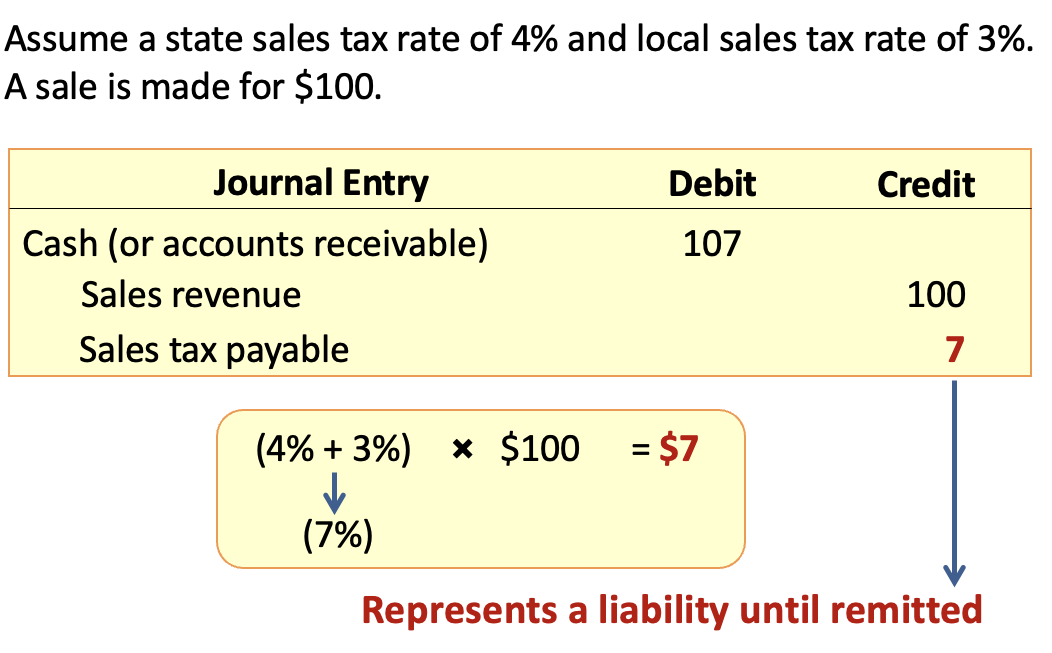
Collections for third parties: Collections made from customers or employees and remitted periodically to the appropriate third parties
Most Common Examples
Payroll-related deductions such as:
Withholding taxes
Social Security taxes
Employee insurance
Employee contributions to retirement plans
Union dues
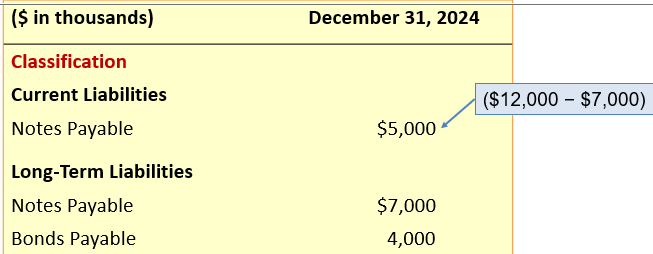
Companies typically prefer to report an obligation as noncurrent rather than current.
Noncurrent classification results in higher working capital and a higher current ratio
Long-term obligations are usually reclassified and reported as current liabilities when they become payable within the upcoming year (or operating cycle, if longer than a year).
bonds
notes
lease liabilities
deferred tax liabilities
Example: 20-year bond issue is reported as a long-term liability for 19 years but normally is reported as a current liability on the balance sheet prepared during the 20th year of its term to maturity.
The requirement to classify currently maturing debt as a current liability includes:
Debt that is callable (due on demand) by the creditor in the upcoming year/operating cycle, even if the debt is not expected to be called
When the creditor has the right to demand payment because an existing violation of a provision of the debt agreement makes it callable
Debt is not yet callable but will be callable within the year if an existing violation is not corrected within a specified grace period
Short-term obligations that are expected to be refinanced on a long-term basis can be reported as noncurrent liabilities if two conditions are met:
The company must intend to refinance on a long-term basis, and
The company must actually have demonstrated the ability to refinance on a long-term basis
This is demonstrated by an existing refinancing agreement or actual financing prior to the issuance of financial statements.
U.S. GAAP: liabilities payable within the coming year are classified as long-term liabilities if refinancing is completed before the date of issuance of the financial statements
IFRS: refinancing must be completed before the balance sheet date
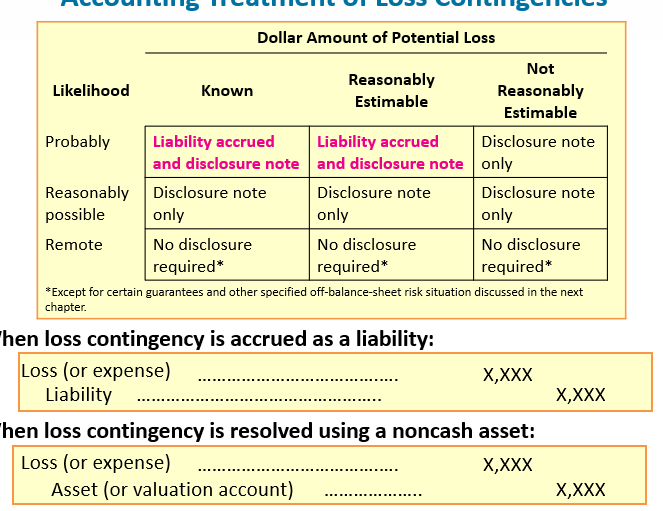
Loss contingency: an existing, uncertain situation involving potential loss depending on a future event
Whether a contingency is accrued and reported as a liability depends on:
The likelihood that the confirming event will occur
What can be determined about the amount of loss
U.S. GAAP requires that the likelihood that the future event be categorized as probable, reasonably possible, or remote.
Probable: confirming the event is likely to occur
Reasonably possible: the chance the confirming event will occur is more than remote but less likely
Remote: the chance the confirming event will occur is slight
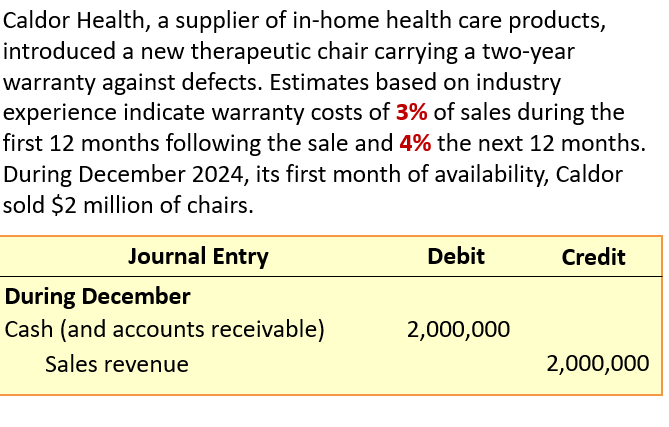
Most consumer products are accompanied by a guarantee, such as a quality-assurance warranty.
Loss contingency: costs of satisfying guarantees should be estimated and recorded as expenses in the same accounting period the products are sold
The criteria for accruing a contingent loss almost always are met for product warranties or guarantees
While we usually can’t predict the liability associated with an individual sale, prior experience makes it possible to predict reasonably accurate estimates of the total liability for a period
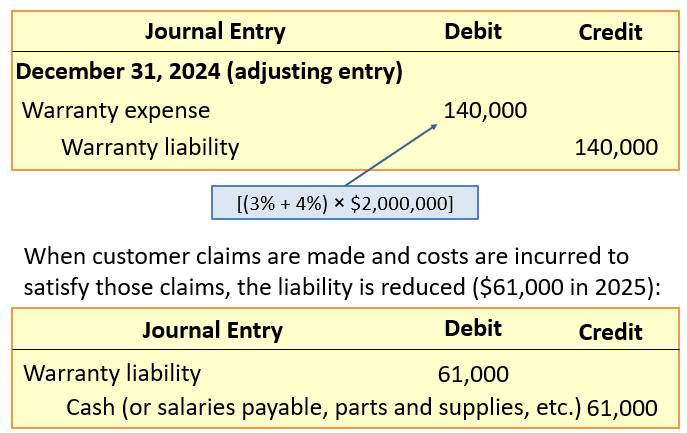
The traditional way of measuring a warranty obligation is to report the “best estimate” of future cash flows
The method ignores the time value of money
An alternative expected cash flow approach is described by SFAC No. 7
Incorporates specific probabilities of cash flows into the analysis
Required conditions:
When the warranty obligation spans more than one year and
We can associate probabilities with possible cash flow outcomes
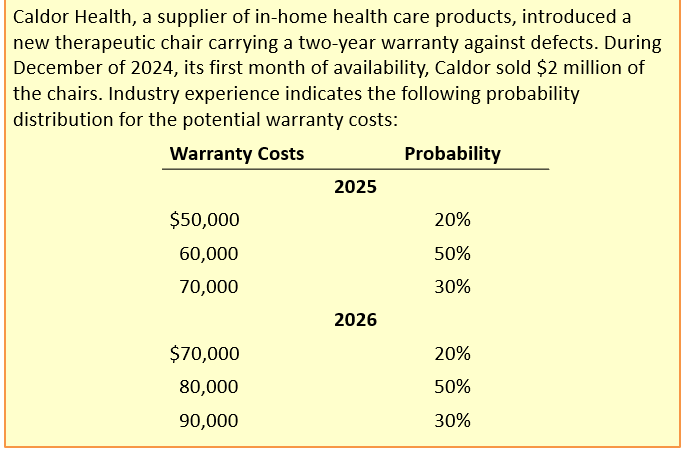
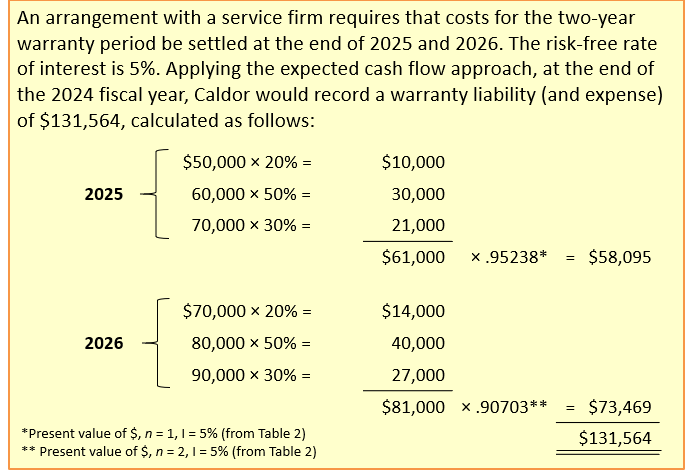
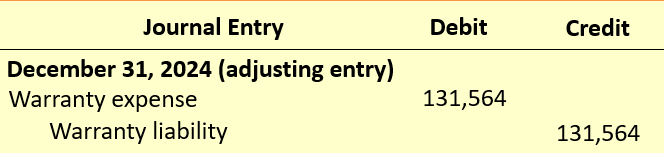
Extended warranty: provides warranty protection beyond manufacturer’s original warranty
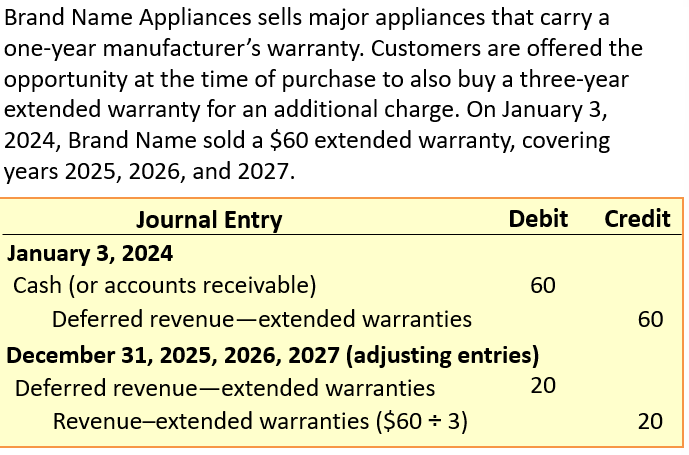
Because an extended warranty is priced and sold separately from the warranted product, it constitutes a separate performance obligation.
Revenue Recognition:
Recorded as a deferred revenue liability at the time of sale
Recognized as revenue over the contract period
Straight-line basis
Pending litigation is not unusual.
Accrual of a loss from pending or ongoing litigation is rare
Outcome of litigation is highly uncertain
Loss is usually not recorded until after ultimate settlement
While companies should provide extensive disclosure of these contingent liabilities, they do not always do so.
Even after a firm loses in court, it may not make an accrual.
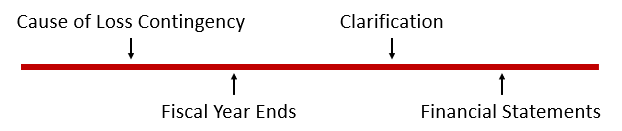
Subsequent events can clarify a pre-existing claim’s
Probability that a loss will occur
Estimated amount of loss
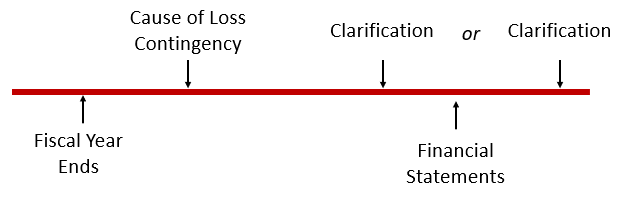
If contingency comes into existence after fiscal year-end
No liability accrues, but description provided in notes
Even if a claim has yet to be made when the financial statements are issued, a contingency may warrant accrual or disclosure.
A two-step process is involved:
Is it probable that a claim will be asserted? If the answer is “no,” stop. If “yes,” go on to step
Treat the claim as if the claim has been asserted.
U.S. GAAP:
All accrued and possible obligations are referred to as “contingent liabilities”
Higher threshold for “probable”
Uses the low end of the range to estimate the expenditure required to settle present obligation
Loss contingencies are not typically discounted for time value of money
No disclosures or loss recognition on “onerous contracts”
Gain contingencies are never accrued
Disclose when gain realization is “probable” but uses a higher threshold for “probable”
IFRS:
All accrued liabilities are referred to as “provisions” and possible obligations are referred to as “contingent liabilities”
Lower threshold for “probable”
Uses the midpoint of the range to estimate the expenditure required to settle present obligation
If material, liabilities to be stated at present value
Recognizes provisions and contingencies for “onerous contracts”
Gain contingencies are accrued if future realization is “virtually certain” to occur
Disclose when gain realization is “probable” but uses a lower threshold for “probable”
Gain contingency: uncertain situation that might result in a gain
Gain contingencies are not accrued
This is an example of conservatism—we record uncertain losses but not uncertain gains
Material gain contingencies are disclosed in the notes to the financial statements
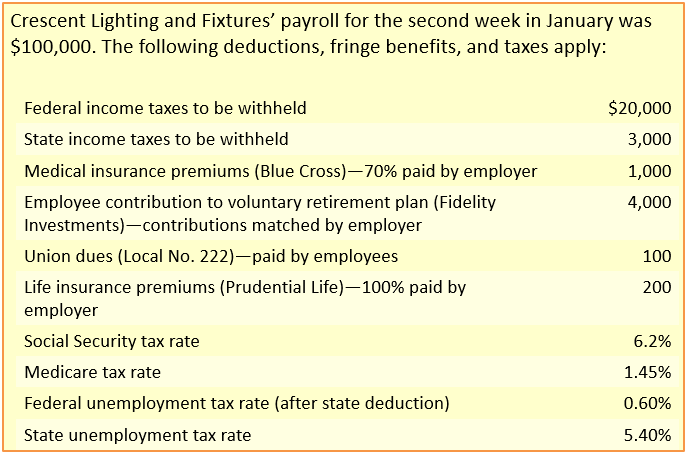
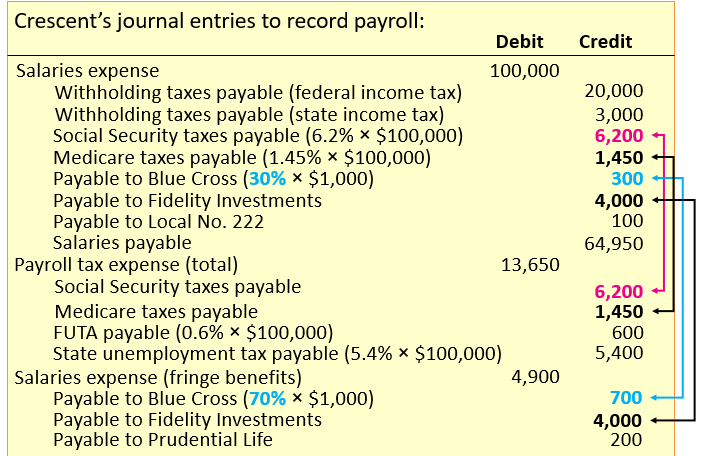
Payroll related liabilities:
Legal requirements to withhold taxes from employees’ paychecks
Legal requirements of the payroll taxes on firms
Voluntary payroll deductions of amounts payable to third parties
Employers are legally required to withhold:
Federal and state income taxes
Social Security taxes
Withholdings from employees’ paychecks
Remitted to taxing authorities
Amount withheld varies with:
Amount of earnings
Amount of exemptions claimed by employee
Federal Insurance Contributions Act (FICA): requires employers to withhold a percentage of each employee’s earnings up to a specified maximum
Employer pays matching amount on behalf of employee
Self-employed persons pay both the employer and employee portions
Voluntary deductions
Include union dues, contributions to savings or retirement plans, and insurance premiums
Represent liabilities until paid to appropriate organizations
Employers’ payroll taxes
Employer’s matching amount of FICA taxes
Employer pays federal and state unemployment taxes on behalf of employees
Fringe benefits
Payment of employees’ insurance premiums and/or contributions to retirement income plans by employer