IFRS 16 - Leases (Lessor)
Lessor Classification
Two major factors for Lessors
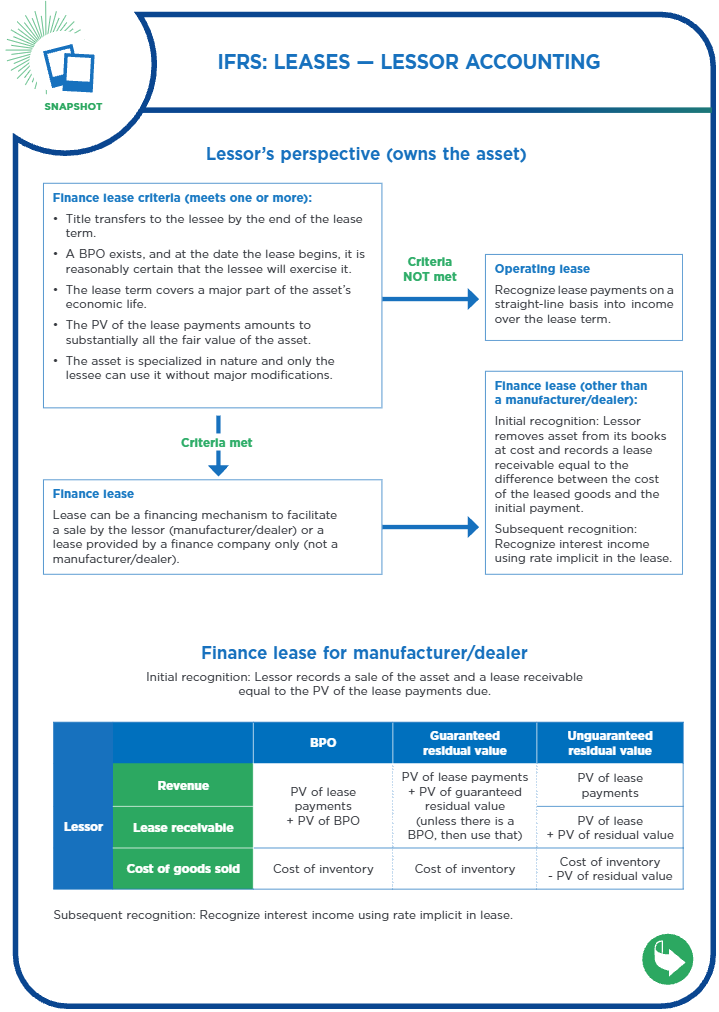
Finance Lease
Transfers substantially all risks and rewards of ownership to lessee
irrespective of whether legal title is transferred or not
Primary Criteria:
Title transfers to lessee by the end of the lease term
BPO exists, ,and at the date the lease begins, it is reasonably certain that the lessee will exercise it
The lease term is of such a duration that the lessee will receive substantially all the economic benefits expected to be derived form the use of the lease property over its economic life
The PV of the lase payments amounts to substantially all the FV of the asset
The asset is specialized in nature and only the lessee can use it without major modifications
Operating Lease
Finance Leases
Manufacturer or Dealer lease
Offered by manufacturer or retailer as financing mechanism to facilitate sale of its own products
Lease Payments

INITIAL MEASUREMENT
Lessor records sale of asset
Sets up lease receivable for the PV of the payments due
Gross investment in the lease
Total of the lease payments receivable under a finance lease and any unguaranteed residual value accruing to the lessor
Net investment in the lease
PV of lease payment amounts and any unguaranteed residual value, each discounted by the interest rate implicit in the lease
Net investment in lease for manufacturer/dealer type leases:
PV of each lease payment, discounted back to inception of the lease using implicit rate in the lease; +
PV of unguaranteed residual value, discounted using the implicit rate in the lease; =
Net investment in lease
Leases offered by Financial Institutions
Lease payments calculated to provide lessor with market rate of return for investments of the risk level inherent in the lease
initial direct costs (lessor) of the lease contract are then capitalized and increase the net investment in the lease, the implicit rate in the lease is reduced and must be recalculated
Calculation:
FV of asset under lease; +
Initial direct costs; -
Lease payments made on or before the commencement date; =
Net investment in the lease at initial recognition
Manufacturer or dealers
JE:
DR Lease receivable, DR COGS; CR Revenue, CR Equipment (Inventory)

SUBSEQUENT MEASUREMENT
Measured at amortized cost
If payment is due at the beginning of the year:

DERECOGNITION
IFRS 9 when derecognizing the investment in the lease
IAS 16 when receiving PP&E back and disposing of the asset
Presentation and disclosure
Should include:
Lease income for the period arising from operating leases
Maturity analysis
For Finance leases:
lease income for the period
Maturity analysis
Reconciliation of total undiscounted payments
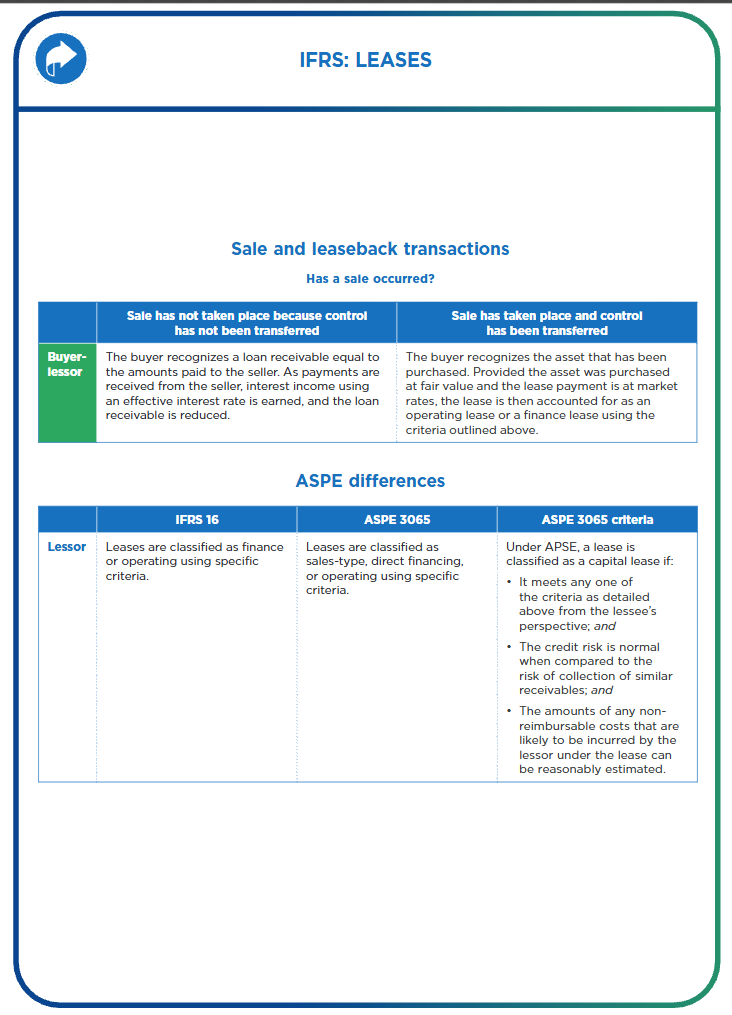
SALE-LEASEBACK TRANSACTION
Same as lessee accounting, just from the other side
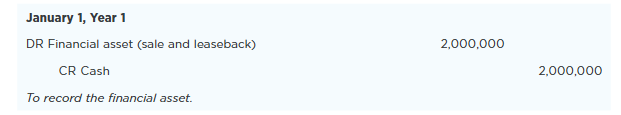

If it is a sale, IFRS 15 - Revenue
Differences of IFRS and ASPE
ASPE term for “Finance Leasing - IFRS” is “Direct Financing or Sales-type lease”
Under ASPE
Direct Financing Lease
financing mechanism provided by finance company or other lender
Sales-type lease
Lease that transfers substantially all the risks and benefits of ownership to the lessee and, at commencement of the lease, the FV of the leased property is greater or less than the lessor’s carrying amount
Significant difference under ASPE, criteria for direct financing or sales-type lease:
Meets anyone of:
Reasonable assurance ownership transfers by the end of the term
Term covers substantially all economic benefits (generally >= 75% of asset’s useful life)
PV of minimum lease payments >= 90% of asset’s fair value
Credit risk is normal when compared to risk of collection of similar receivables
Amounts of any non-reimbursable costs that are likely to be incurred by the lessor under the lease can be reasonably estimated