Chaper 8 Notes ( 8.3 - 8.9 )
Economic Role of Costs
The demand for a product represents the voice of consumers telling firms to produce a good
A firms cost represents the desire of consumers not to sacrifice good that could be produced if the same resources were employed elsewhere
(Demand is the benefit of making a product, while cost is the hidden sacrifice of what could have been made instead.)
Calculating Economic Costs and Profits
Profit: Total Revenue - Total Costs
Total Product (output): Total quantity of output produced with a given amount of resources
Marginal Product of Labor (MPL) =▵Q/▵X
I.E.
Remaining Blanks: 10,15,20,10,0,-15

Explicit Costs: Payments by a firm to purchase the services of productive resources
Fixed: Costs that don’t change with the amount of output produced
i.e. rent, purchases of land, etc.
Variable: Costs that change with the amount of output produced
i.e. # of workers, inputs to the good, etc.
Implicit Costs: Hidden opportunity cost of using resources you already own instead of using them for their next best alternative
Economic & Accounting Profits
Accounting Profit: Revenue - Explicit Costs
Economic Profit: Revenue - Explicit + Implicit Costs
I.E.

Accounting Profits: 8,000-7500 = 500
Economic Profits: 8,000-8200 = -200
Average Costs: The cost per unit of output
Average fixed costs (AFC) = Fixed costs / Quantity
Average variable costs (AVC) = Variable costs / Quantity
Average total costs (ATC) = Total Costs / Quantity = (FC+VC)/Q
Marginal Cost (MC): The additional cost associated with 1 more unit of production; ▵TC/▵Q
When MC is below AVC, AVC must be decreasing
When MC is above ATC, ATC must be increasing
MC will cross AVC AND ATC directly at their minimum
Opportunity Cost of Equity Capital: Rate of return that must be earned by investors to induce them to supply financial capital to the firm
Short-Run & Long-Run Time Periods
Short Run: The time period in which at least one input of production cannot be changed
Long Run: The time period in which all inputs of production can be changed
Categories of Costs
Total fixed cost (TFC): sum of the costs that do not vary with output; will remain unchanged when output rises or falls in the short run
Average fixed cost (AFC): TFC/ # of units produced; always ↓ as output ↑
Total variable cost (TVC): sum of the costs that rise as output increases
Average variable cost (AVC): TVC/ # of units produced
Total cost (TC): sum of fixed and variable costs
Average total cost (ATC): TC/ # of units produced; also called per-unit cost; also = to sum of AFC & AVC
Marginal Cost (MC): ▵TC required to produce an additional unit of output
Diminishing Returns & Production in the Short Run
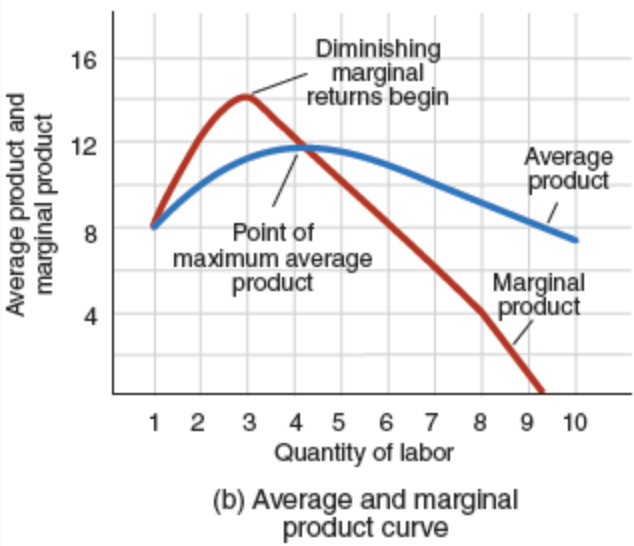
Law of diminishing returns: Adding more of one input while keeping other inputs fixed will eventually lead to smaller and smaller increases in output
Total Product: total output of a good that is associated with each alternative utilization rate of a variable input
Marginal Product: Extra output gained by adding one more unit of an input while keeping all other inputs the same
Average Product: Total product/ # of units of the variable input required to produce that output level
As units of labor are added to a fixed input total products will ↑, first at an ↑ rate and then a ↓ rate.

This will cause both marginal and average product curves to ↑ at first and then ↓.
Economies & Diseconomies of Scale
3 reasons why planning a larger volume of output usually reduces (initially) unit costs
Economies accompanying the use of mass production
Typically economical only when large volumes of output are planned because they tend to involve larger development and setup costs
Once production methods are established, marginal costs are low
High-volume methods typically require high fixed costs and cause unit costs to be far higher for low volumes of production
Higher productivity as a result of specialization (“learning by doing”)
Economies in promotion and purchasing
Economic theory explains why initially larger firms have lower unit costs than comparable smaller firms
Economies of Scale: cost of making each individual item goes down as a company produces more of them
Diseconomies of Scale: a company grows so much the AC to produce each unit goes up
Alternative Shapes of the LRATC