Unit 3 Econ Micro
Basic Accounting:
Revenue- money you take in (P X Q)
Costs- what you pay
Profit- what you keep
Fixed v Variable costs:
Fixed costs- do not change with production ex.) rent
Variable costs- change with products ex.) raw materials
*Total costs= Fixed + Variable
Explicit v implicit costs:
Explicit costs- out of pocket costs (the bills you paid)
Implicit costs- opportunity costs (what you could have been doing with your resources instead)
Accountants v Economists:
Accounting profit= Total Revenue - Explicit costs
Economic profit= Total Revenue - explicit costs - implicit costs
Films Production:
Total Physical production: (TP) total output or quantity produced
Marginal Product: (MP) additional output generated by input (workers)
Average Product: (AP) output per unit of input
Average product: Total product/ units of labor
Stages of products:
Increasing returns- MP is increasing
Diminishing returns- more input are added, total output keeps rising, but at a slower rate.
Negative returns- too much of one input. TP declines
Law of diminishing marginal returns- as you added input, to a fixed amount of resources eventually marginal product declines.
Long run v Short run
Short run: not enough time to change plant size. Some costs are fixed
Long run: can change plant size. All costs are variable
Perfect Competition:
Many firms
Identical product
Easy to enter
Price taker
4 possibilities:
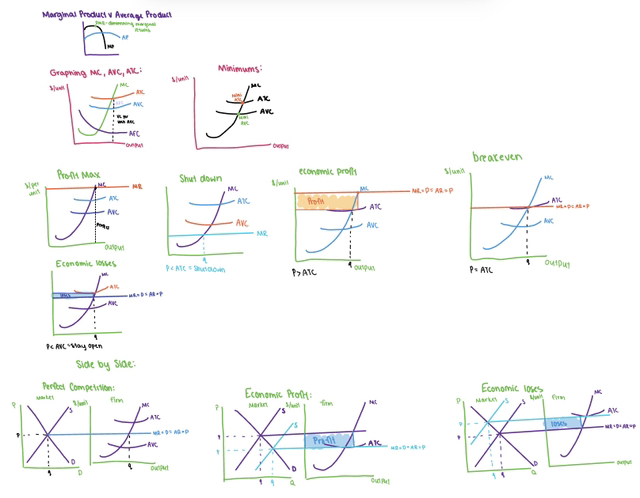
Price > Average total costs= Economic profit
Price = Average total costs = breakeven
Price < Average total costs= economic loses (AVC < P < AVC = stay open)
P < Average Variable costs= Shutdown
Profit Maximizing rule: Marginal costs = Marginal Revenue
MC < MR = produce more, MC > MR = Product less
Side by Side graph;
film takes te price from the market (MR= D= AR= P)
Marginal Revenue = Demand = Average Revenue = Price
Firm faces a 100% elastic demand curve, they can sell as many units as they want at the market price
The firm will produce where MC=MR (profit max)
Long run equilibrium: P=ATC min = MR
Allocative efficiency- P= MC, producing the Q desired by society
Productive efficiency- P= ATC, least cost production (most effective)